Inflection Points in Business and Math — A Practical Breakdown
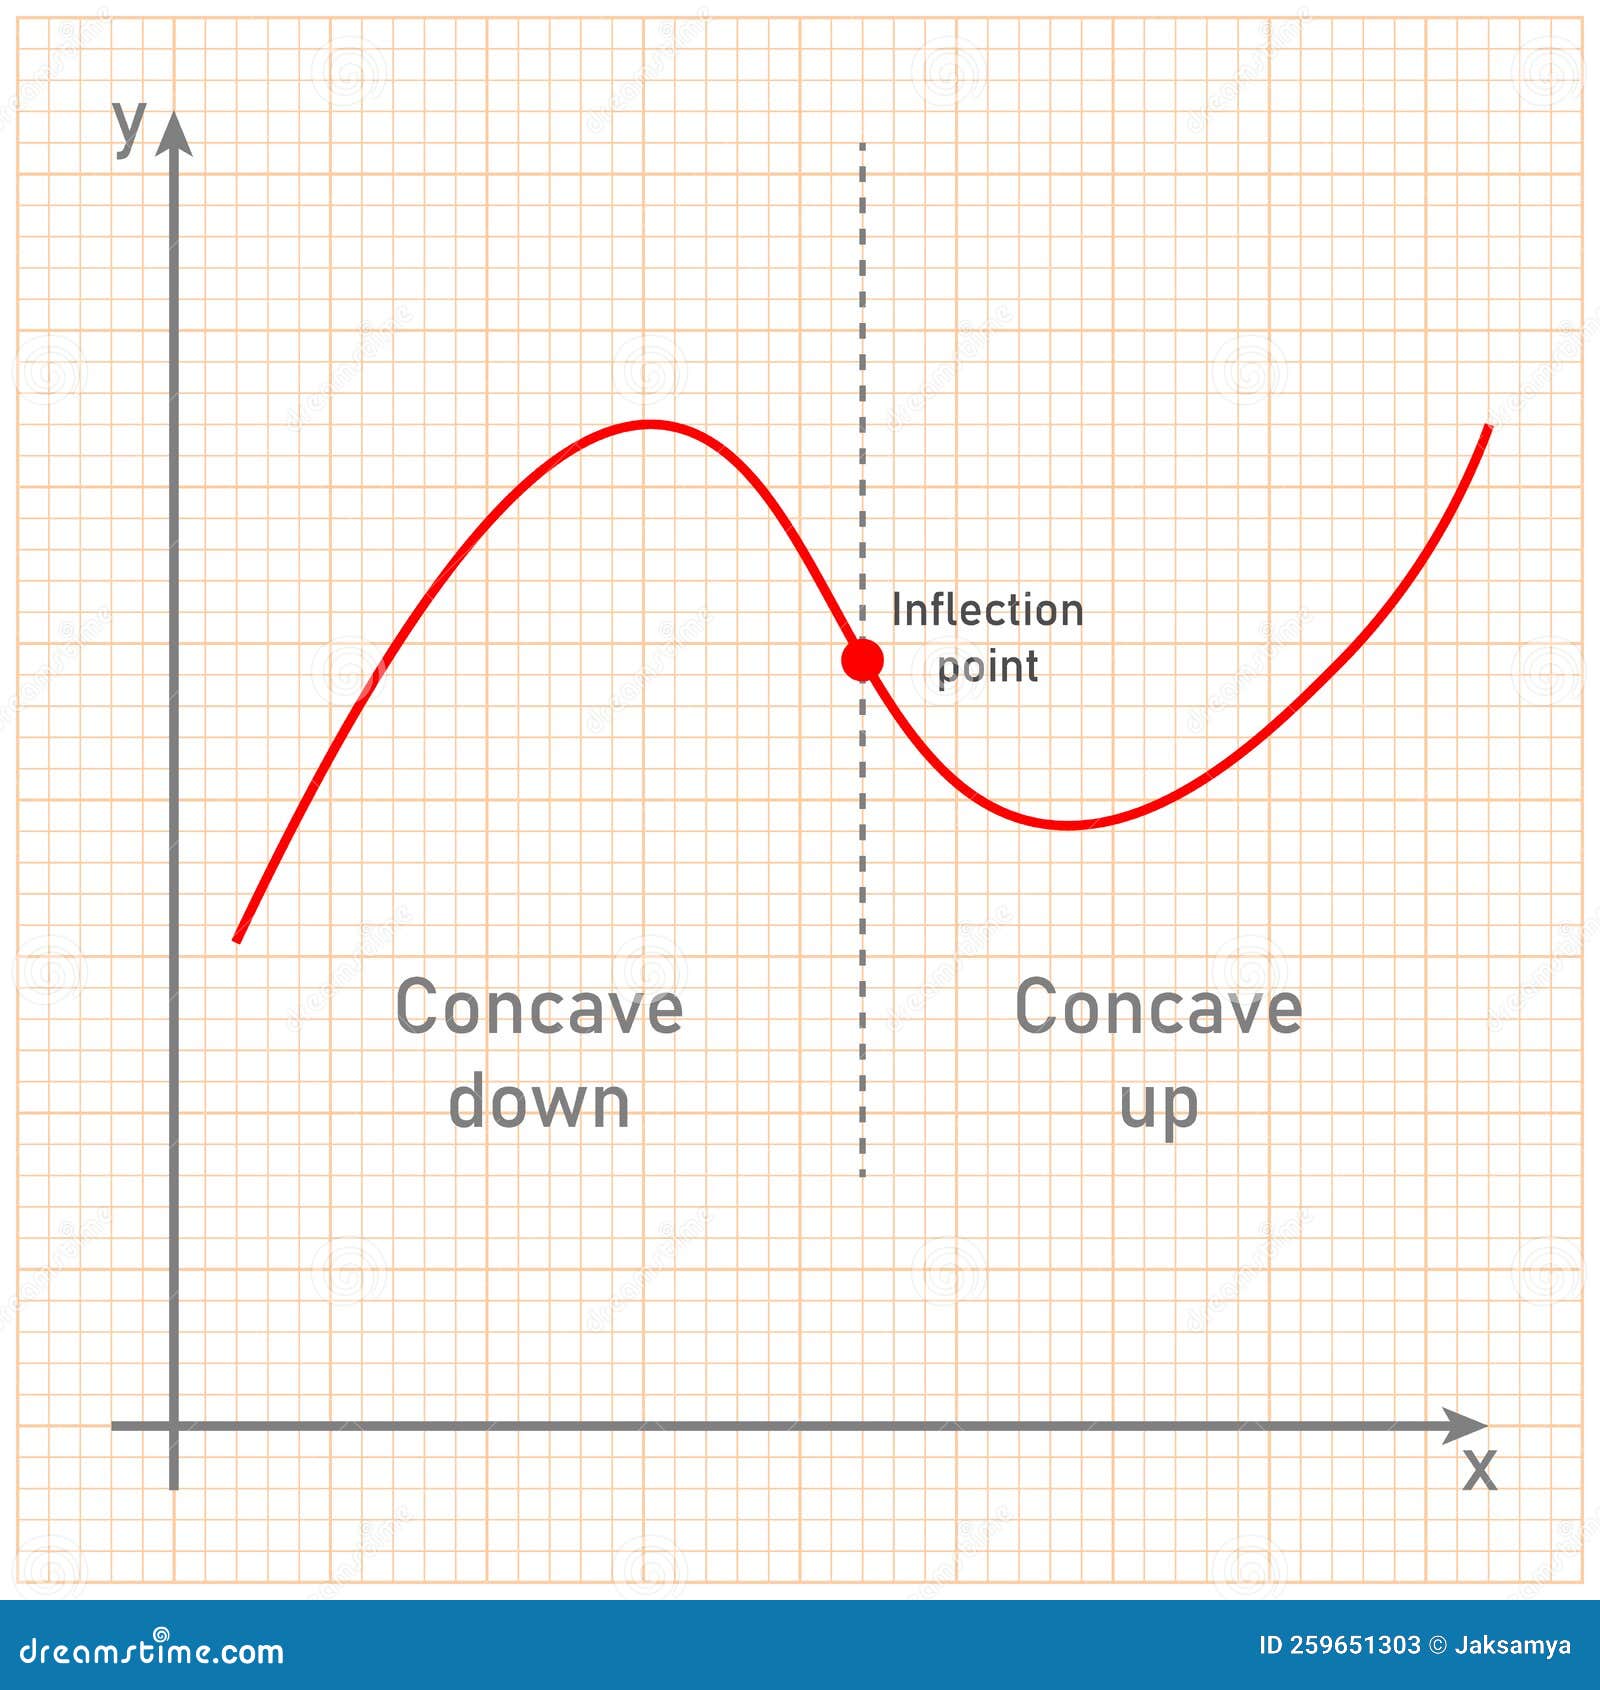
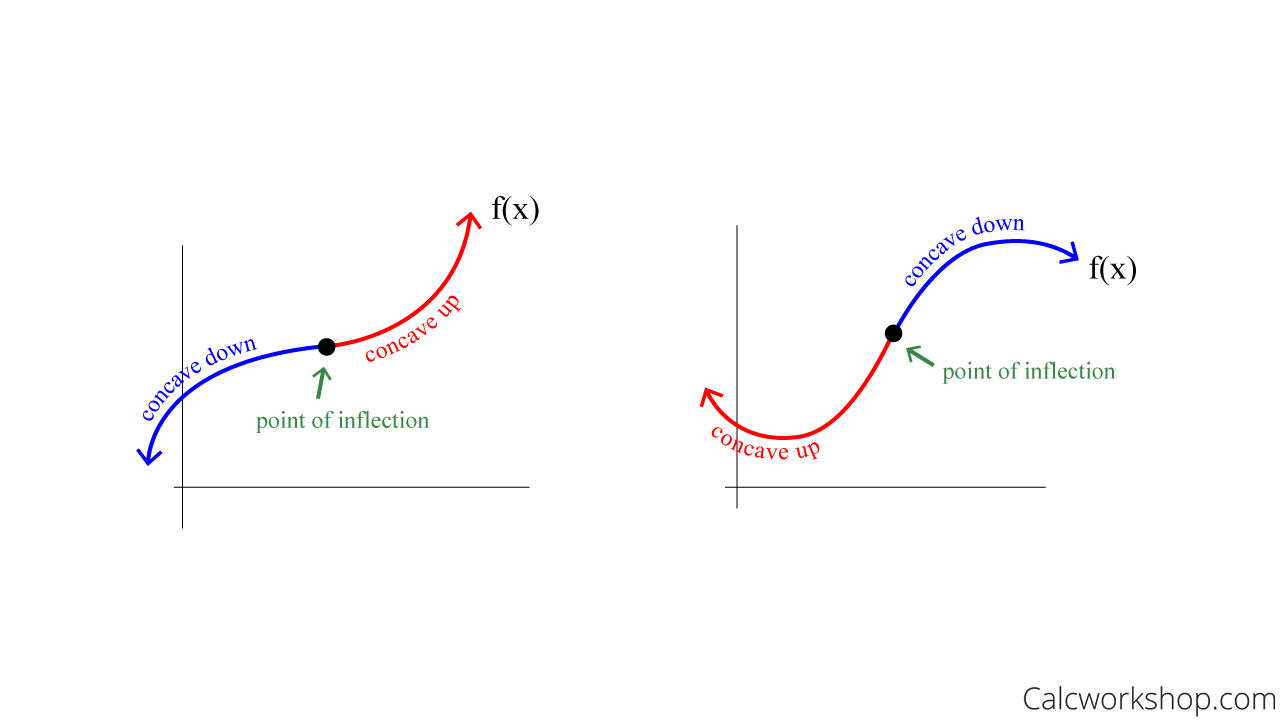
Most people use the term inflection point as a buzzword at strategy meetings without actually knowing what it means. The word comes from calculus, where it has a precise definition: a point on a curve where the concavity changes. That is all it is. The second derivative flips sign. The slope stops getting steeper and starts getting shallower, or vice versa. The business usage borrows from this but gets watered down into anything that looks like a big change. Here is how I actually use the concept, and where it breaks down in practice.
What Are Inflection Points in the Real World
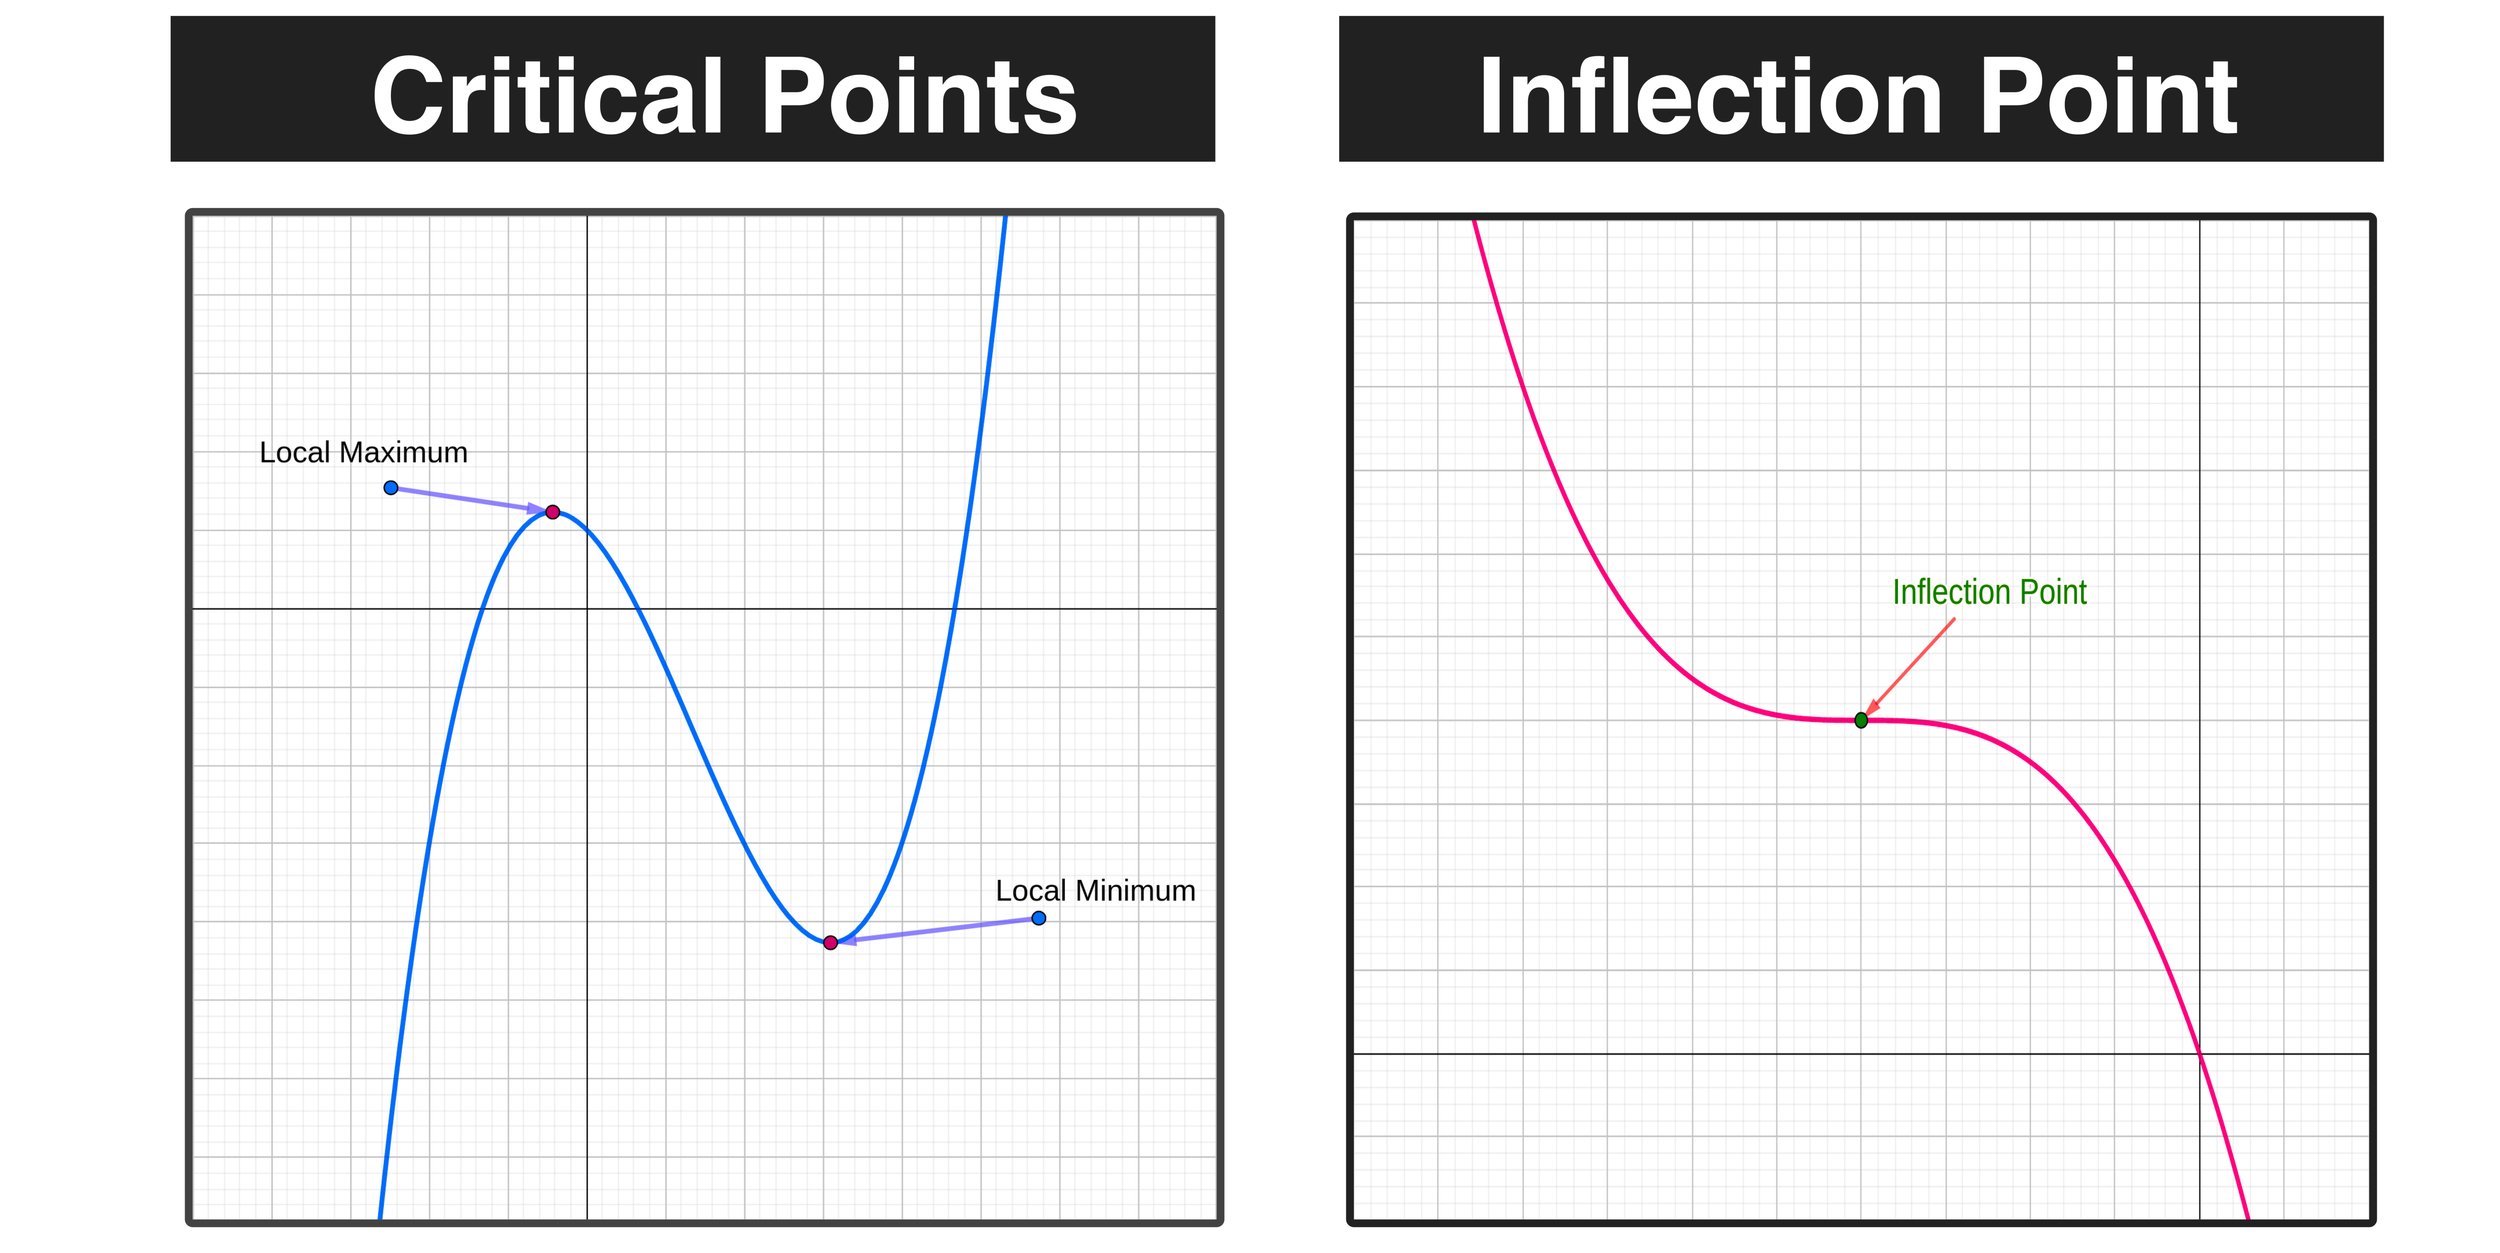
In technical terms, an inflection point is where the rate of change of a rate of change reverses direction. If you are plotting revenue over time and the growth itself is accelerating, then suddenly the acceleration flips to deceleration, that moment — not the peak, not the plateau — is the inflection point. The curve went from holding a bowl shape to an upside-down bowl shape, or the other way around. The common mistake is calling a maximum or minimum an inflection point. They are different things. At a maximum or minimum, the first derivative hits zero. At an inflection point, the second derivative hits zero. A curve can inflect without reaching a peak. A hill can have an inflection point on its way up where the climb feels less steep even though you are still gaining height. That distinction matters when you are analyzing data because confusing the two leads to bad timing decisions. I once worked on a SaaS subscription model where churn rate started climbing slowly, then the climb accelerated past a certain cohort of customers. The inflection point showed up in the data about three months before the actual revenue drop became obvious. The first derivative was still positive — total revenue was growing — but the second derivative told a different story. By ignoring the curvature and only watching the top-line number, my team nearly missed a structural shift in the customer base. The workaround was to fit a cubic spline to the rolling monthly churn data and track where the fitted curve's second derivative crossed zero. Raw counts are too noisy for this. You need smoothing, and cubic splines handle it better than polynomial regression because they do not overshoot at the edges the way high-degree polynomials do.
How to Spot an Inflection Point in Data
Start with the raw series and calculate the first differences. Then calculate the differences of those differences. Where that second-order difference crosses zero, you have a candidate inflection point. This is the discrete approximation of finding where the second derivative equals zero. It sounds straightforward until you deal with real data. Real data has noise. Monthly metrics bounce around. A single outlier can create a false zero-crossing in the second differences that looks like an inflection point but is just statistical garbage. The fix is to smooth the data first. Moving averages work for simple cases, but they lag. Exponentially weighted moving averages reduce lag slightly but still distort the exact location of the inflection. For anything that requires precision, use LOESS regression or a Gaussian process smoother. These preserve the curvature better than linear smoothers because they do not impose a fixed shape on the data. Here is another trap: seasonality. If your data has a quarterly pattern, the second differences will oscillate for reasons unrelated to any structural shift. De-seasonalize first, then look for inflection points. I usually remove seasonality using STL decomposition — seasonal and trend decomposition using loess. It handles non-linear trends better than classical decomposition, which assumes the seasonal pattern stays constant over time. In my experience, classical decomposition broke on a retail dataset where holiday shopping patterns shifted gradually year over year. STL caught the drift; classical did not.
Get the Full Details
When Inflection Points Are Useful and When They Lie
Inflection points work well for identifying regime changes in growth trajectories. Product adoption curves, learning curves in manufacturing, cost curves under economies of scale — these all have natural inflection regions. The point where marginal cost stops declining and starts ticking upward is an inflection point on the average cost curve. Finding it tells you where to stop expanding capacity before diminishing returns bite hard. They also surface in biological and epidemiological models. The inflection point of an epidemic curve is where the number of new infections per day stops accelerating and starts decelerating. That is not when the outbreak ends. That is when the growth rate peaks. Public health teams sometimes confuse these two moments and announce the wrong thing to the public. The inflection point came four weeks before I thought it would in a respiratory virus model I built a few years back. The R value had already crossed below one, but the cumulative case count was still rising fast because the momentum had not caught up yet. This is the classic momentum problem in differential equations. The state variable keeps moving in the same direction for a while after the forcing function changes. The main limitation of inflection point analysis is that it is purely descriptive. It tells you where a change happened, not why it happened. Two datasets can have identical inflection points for completely different reasons. Correlation with external variables is necessary but not sufficient for causation. I have seen teams treat an inflection point as a prediction tool and place bets on future movements based solely on its position. That is a mistake. The inflection point is a backward-looking signal. It identifies a threshold that has already been crossed. Using it to forecast forward without a causal model attached is gambling dressed as analysis.
Another issue is granularity. The location of an inflection point shifts depending on how you aggregate the data. Daily data shows different inflection points than weekly or monthly data. This is not a bug in the method. It is a feature of how discretization interacts with curvature. If you need consistent signals across reporting periods, pick your aggregation level and stick to it. Do not switch mid-analysis and pretend the results are comparable. I learned this the hard way when a stakeholder asked why the inflection point moved three days earlier after we changed from daily to weekly aggregation. It was not moving. The sampling was different. There is also a computational edge case worth mentioning. When working with very flat curves — say, a metric that grows logarithmically over many periods — the second derivative hovers near zero for extended stretches. This makes it nearly impossible to pinpoint a single inflection point. The curve is already past any meaningful inflection and is just drifting. I encountered this with engagement metrics for a legacy product. The curve had flattened two years prior, but the noise floor was still high enough that automated inflection detection kept firing false positives every quarter. The solution was to set a minimum curvature threshold. If the absolute value of the second derivative falls below a certain bound, treat the region as flat and suppress inflection detection. This reduced false positives from roughly one per month to one per year, which was the actual rate of structural change in that product's lifecycle.
Practical Steps for Your Own Analysis
Pull your time series. Apply STL de-seasonalization if there is a repeating pattern. Fit a LOESS or Gaussian process model to capture the underlying trend. Compute the second derivative of the fitted curve numerically using central differences with a small bandwidth. Locate zero crossings. Validate each candidate by checking that the crossing is not driven by a single outlier — re-fit the model with that point removed and see if the crossing persists. If it disappears, it was noise. If it holds, you have a real inflection point. Do not stop at the math. Overlay known events on the timeline. Product launches, policy changes, market shocks. An inflection point that aligns with a documented event is more actionable than one that floats in isolation. The alignment does not prove causation, but it gives you a hypothesis to test against controls or counterfactuals. Inflection points are not magic. They are a tool for detecting changes in acceleration. Use them carefully, respect their limits, and do not confuse a mathematical curiosity with a strategic insight without additional evidence backing it up.