The Seller Side Of Closing Costs
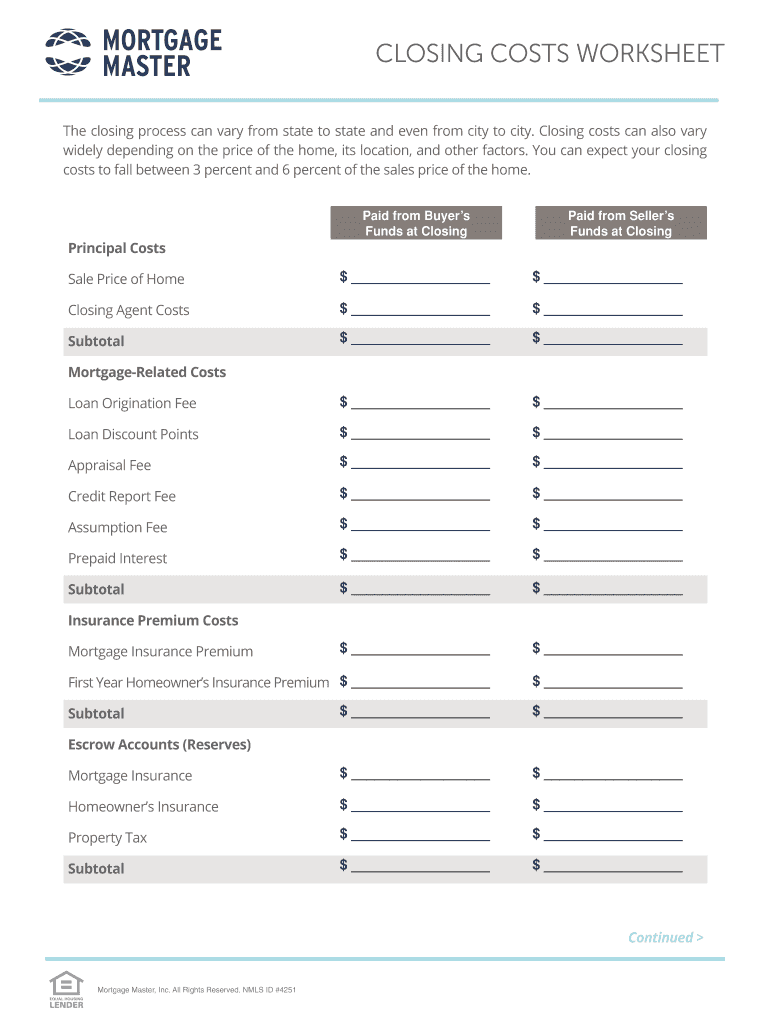
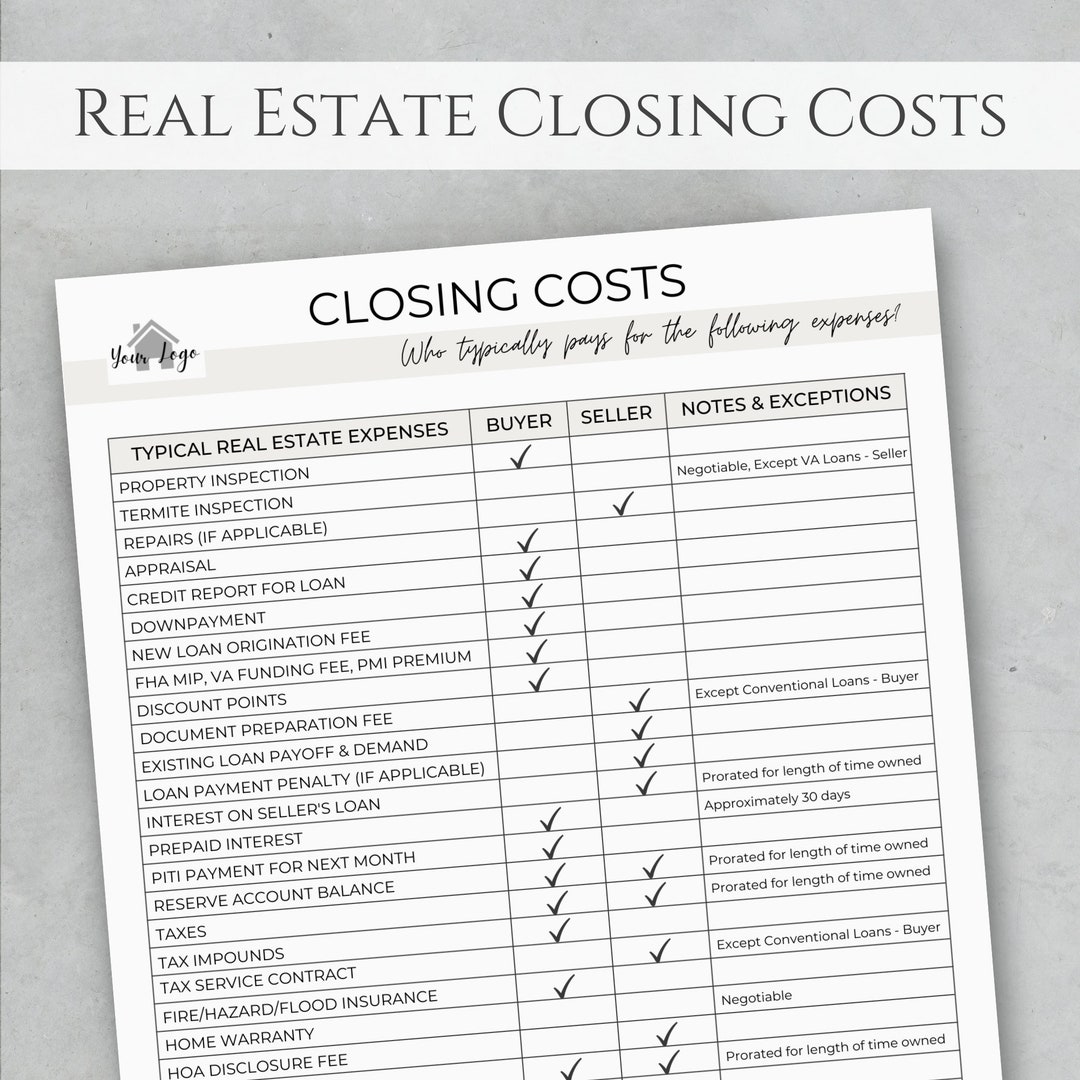
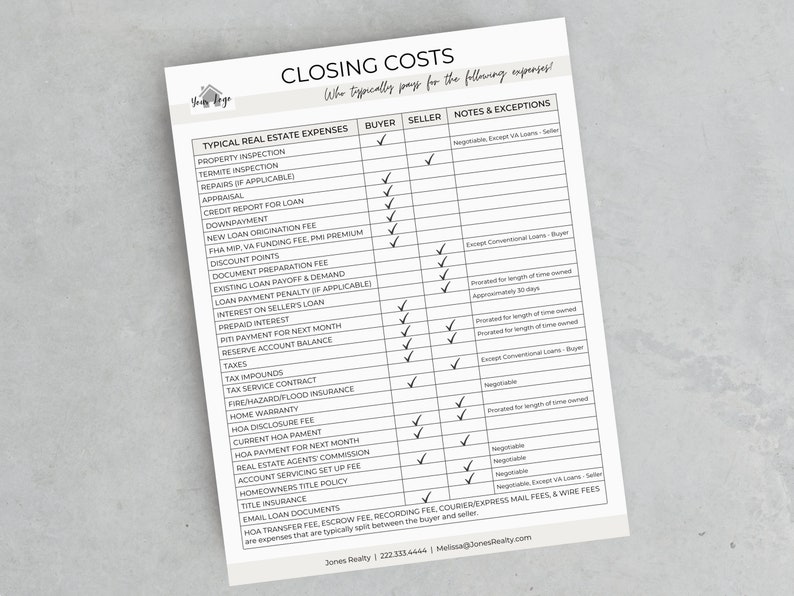
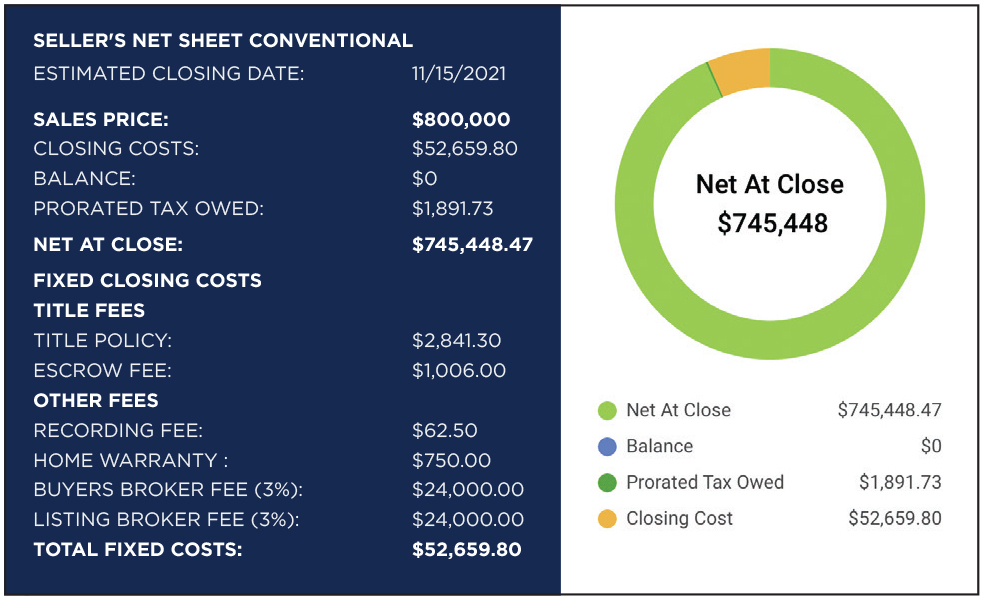
Seller closing costs usually run between 6% and 10% of the sale price, though that range shifts depending on where the property is located and how you structure the deal. I spent years watching people get blindsided by numbers they thought were minor. The title insurance premium, transfer taxes, broker commissions, these all add up in a way that feels surprising until you sit down and do it once. What Are The Closing Costs For A Seller is really just the sum of every fee and tax the seller is contractually responsible for at the end of a transaction. It varies by market, but there are consistent line items you will see almost everywhere.
Broker Commissions
This is typically the single largest expense. The standard rate in most markets sits around 5% to 6% of the final sale price, split between the listing agent and the buyer's agent. I watched a property in suburban Connecticut go under contract at $875,000 and the commission alone came to $52,500 before either agent even paid their office overhead. That number alone wiped out most of the seller's equity gain if they had only lived there a few years and hadn't appreciated much. The workaround I use with clients who want to protect their margins is straightforward: negotiate a lower commission split or a flat-fee listing arrangement when the property price is high enough that even a reduced percentage still generates reasonable income for the agent. A 4.5% total commission on a $1.2 million home still nets the agents more than a standard 6% on a $400,000 home. Agents understand this math, and most will agree to it if you present it professionally before signing the listing agreement.
Transfer Taxes And Recording Fees
Transfer taxes are imposed by state and local governments whenever ownership changes hands. Some states charge nothing. Others, like New York and Illinois, charge significant amounts based on the sale price. In New York State you are looking at 0.4% plus local municipality taxes that can add another 0.25% to 1% depending on the city. I had a client in Syracuse who was absolutely stunned when the transfer tax bill ran over $8,000 on a $550,000 sale. She had no idea her county charged separately from the state. Recording fees are smaller but unavoidable. These are charged by the county recorder's office for logging the new deed. They usually fall in the $100 to $250 range, though some counties charge per page or per instrument, which can push it higher for complex transactions with multiple addenda.
Get the Full Details
Title Insurance And Settlement Fees
In many states the seller pays for the owner's title insurance policy, or at least a portion of it. The premium is a one-time fee calculated on the sale price, and it scales non-linearly, meaning each additional tier of value costs less proportionally. On a $400,000 home the owner's policy might run $1,200 to $1,800 depending on the state. In some markets like Texas and Colorado the seller traditionally covers the owner's policy while the buyer gets their own lender's policy. In other markets the custom flips, and the buyer pays both. I worked a deal in Ohio where the title company discovered an unresolved mechanic's lien from a roof repair the seller had done five years earlier. The lien was for $4,200 and the contractor had never been paid because the homeowner's insurance claim had gone through a dispute. The seller thought the work was done and forgotten. We resolved it by negotiating a partial payment plan at closing where $2,800 was held in escrow and released to the contractor once he provided a signed lien waiver. It added three days to the closing timeline but prevented the deal from falling apart entirely. That kind of issue is exactly why I always recommend ordering a preliminary title report as soon as the property hits the market rather than waiting until the inspection period.
Owner's Payroll And Prorated Expenses
Property taxes, homeowner association fees, and sometimes even utilities get prorated between the buyer and seller based on the closing date. The seller pays for the days they actually owned the property, and the buyer takes over from there. If the seller has already paid the annual property tax bill in full and the closing happens in July, the seller is owed a credit from the buyer for the second half of the year. The reverse is also true, and this is where I have seen the most disputes. I handled a transaction where the seller's property tax bill was $6,800 for the fiscal year and closing happened on March 14. The proration should have credited the seller roughly $4,600 from the buyer. But the county had not yet issued the new tax bill for the upcoming year, so the buyer's side of the calculation was based on the previous year's assessment. The seller ended up shorting about $340 because the new assessment had increased the taxable value. I learned from that one: always request the current year's actual tax bill from the county assessor's office before calculating prorations, and if it is not available, use the prior year's bill with a written acknowledgment from both parties that the numbers are estimates subject to adjustment at the next tax cycle.
Closing Day Fees And Administrative Costs
The settlement agent or closing attorney charges a fee for preparing the closing documents, coordinating the escrow account, and overseeing the disbursement of funds. This is usually a flat fee between $500 and $1,200. Some states require an attorney to conduct the closing, which adds legal review time but also provides a layer of protection that a simple title company abstractor does not. There are also smaller line items that collectively matter: wire transfer fees if the seller needs to receive funds electronically, courier charges for document delivery, and occasionally a fee for providing the payoff statement from the seller's mortgage holder. Mortgage payoff statements are not free, and lenders typically charge $200 to $350 to issue one. I have seen sellers forget this entirely and then get hit with the fee on closing day when they realize their loan needs to be satisfied before the deed transfers.
What The Numbers Actually Look Like
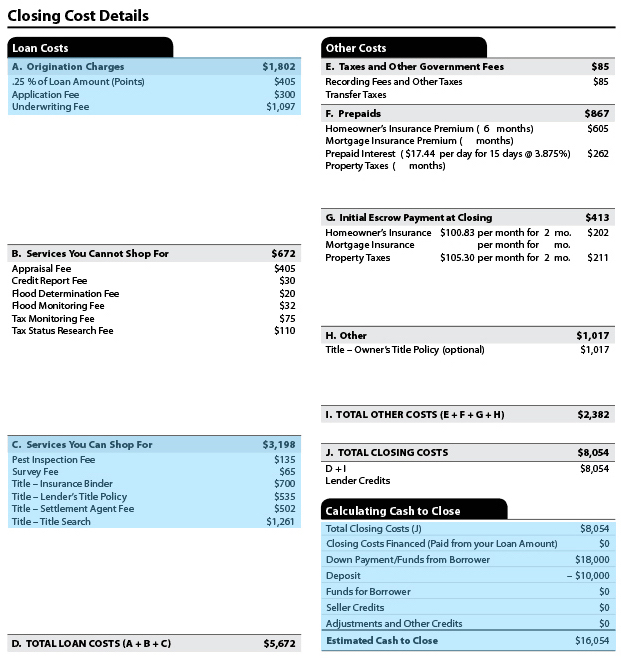
Let me give you a concrete example from a real transaction I managed last year. The property sold for $625,000 in central Florida. The breakdown was: broker commission at 5.5% total ($34,375), county documentary stamp tax at 0.7% ($4,375), title insurance at $1,650, settlement fee at $750, mortgage payoff fee at $275, and prorated property taxes owed to the buyer of $2,100. The seller's total closing costs came to approximately $43,525, or about 6.96% of the sale price. Not unusual for that market, but the seller had budgeted for 5% and was caught off guard by the gap. The takeaway here is not that the system is unfair, it is that people routinely underestimate because they only think about the commission. The commission is the big one, yes, but the transfer taxes and proration adjustments are the silent killers of seller profit margins, especially in high-tax jurisdictions.
When The Math Breaks Down
There are scenarios where the standard closing cost model simply does not apply. Short sales involve lender approval processes that add their own fees, including negotiation costs and sometimes administrative charges from the bank that can total several thousand dollars. Foreclosure properties may have outstanding code enforcement liens that become the seller's responsibility before closing can occur. Manufactured homes that are classified as personal property rather than real estate avoid some transfer taxes but incur different documentation fees that buyers often do not expect. If the property is being sold as-is by an investor who has no intention of using a real estate agent, the commission disappears but the seller still owes transfer taxes, title insurance, and settlement fees. In those cases the total cost percentage climbs closer to 4% to 5% because the commission was doing a lot of the heavy lifting in the traditional calculation. This is counter-intuitive for most first-time sellers who assume that selling without an agent saves them money. It saves the commission, but it does not eliminate the other costs, and it removes the professional guidance that usually catches errors before they become expensive problems.