The Core Building Blocks That Actually Matter
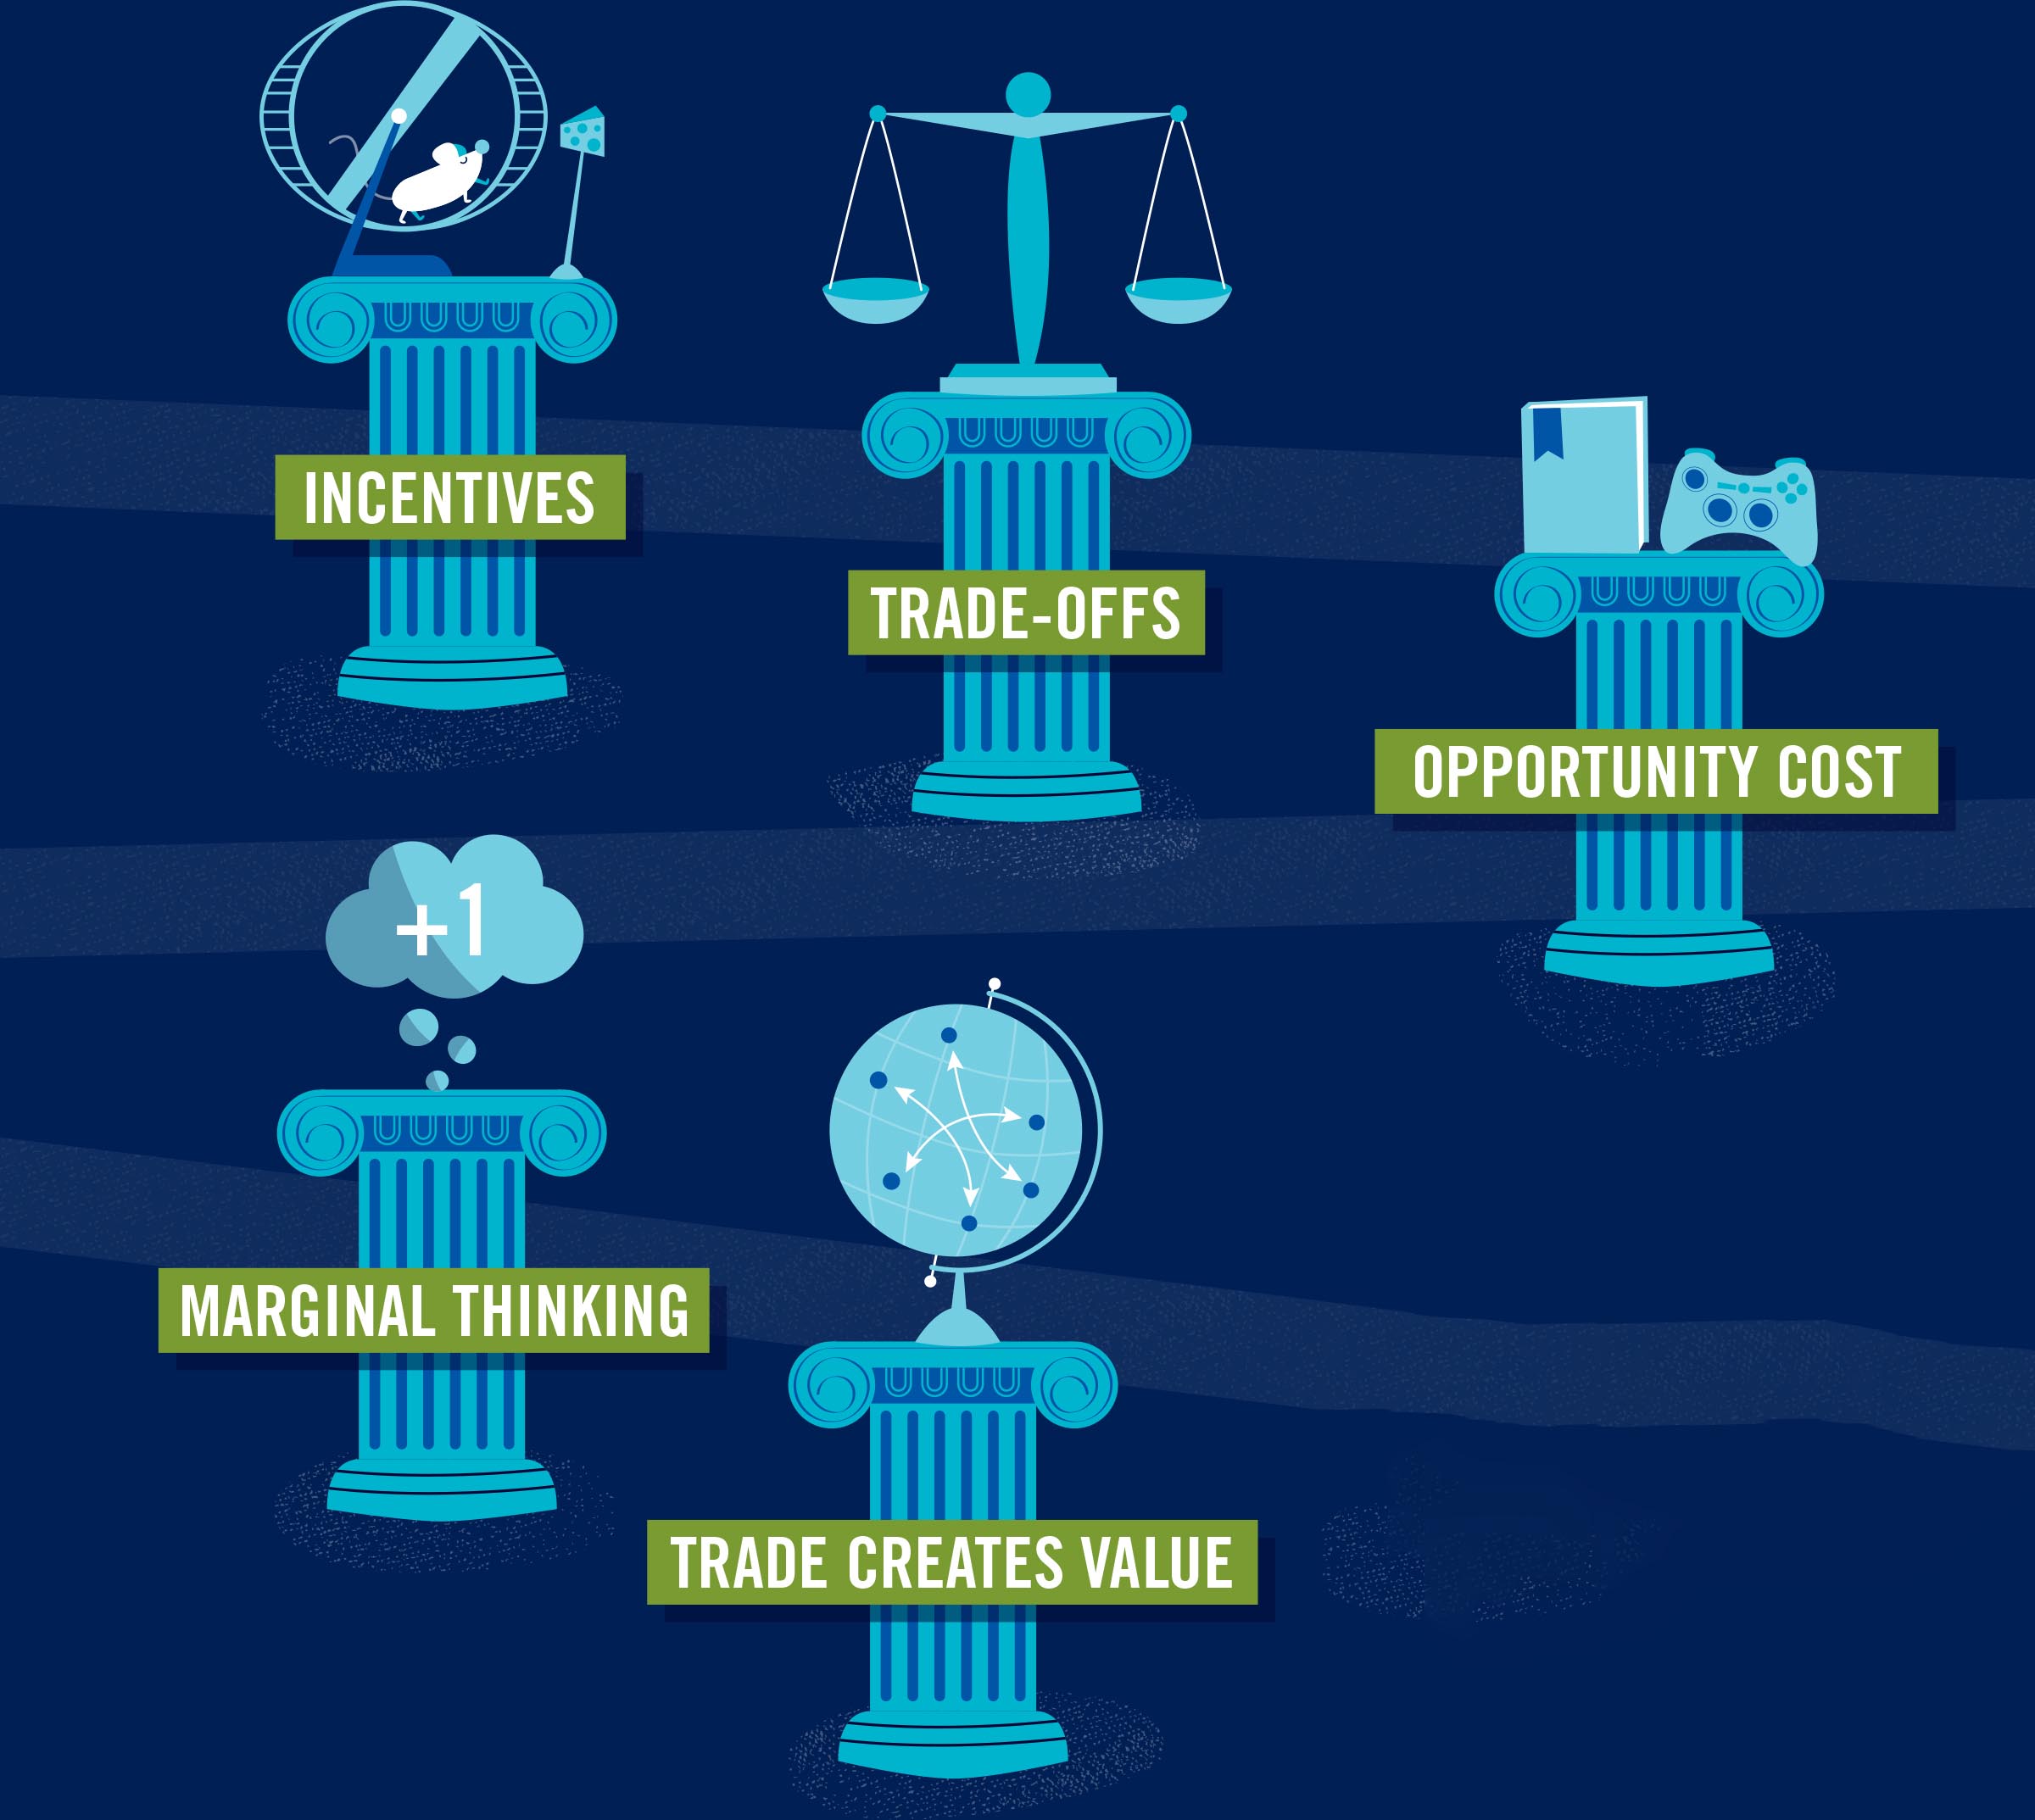
Economics isn't some mysterious discipline reserved for people in suits making decisions on Wall Street. At its base, it's just a framework for understanding how people make choices when they can't have everything they want. I spent years working with economic models and policy analysis, and the truth is, most of what matters comes down to five foundational ideas. Everything else builds on these or is just a variation of them. I ran into a situation last year where a local government wanted to subsidize a new transit route. The proposal looked good on paper, but when I actually mapped out the opportunity costs and marginal benefits against the existing system, the numbers told a different story. The subsidy wasn't the problem, but the analysis framework revealed that the real bottleneck was station placement, not funding. That kind of thing happens when people skip straight to solutions without grounding their thinking in the foundations first. Scarcity is the starting point for everything. Resources are limited. Time is limited. Money is limited. This isn't philosophy, it's just the basic condition of existence. If resources were infinite, economics would cease to exist as a field of study. Every decision you've ever made involved some form of scarcity, whether you realized it or not. The scarcity principle forces trade-offs, and recognizing that upfront saves you from building models that assume infinite capacity or budget.
The second foundation is incentives. People respond to incentives, sometimes in ways that make no sense unless you actually look at what's motivating them. I once reviewed a cost-benefit analysis where the numbers suggested a policy would save money, but it completely ignored the incentive effect on the people it was supposed to help. The policy designers had modeled behavior perfectly, except they assumed humans would act like rational agents. They didn't. The actual uptake was less than a third of projections because the incentive structure was backwards from what anyone expected. Supply and demand is probably the most widely recognized concept, but most people treat it like a diagram they saw in high school rather than a living mechanism. The relationship between supply and demand determines prices, and prices coordinate behavior across millions of transactions without anyone centrally directing it. When you see a shortage, it's usually a price signal being suppressed or distorted somehow. I've seen this play out repeatedly in housing markets where zoning restrictions create artificial scarcity that standard supply-demand analysis flags immediately, but local politics always seems to override the analysis. Marginal analysis is where most people trip up. The question isn't whether something is good or bad overall. It's whether the next unit, the next dollar, the next hour is worth it. Decision-making at the margin is what separates competent analysis from amateur guessing. In practice, this means asking what changes if you go one step further, not whether the entire project is worthwhile. I worked on a project once where the total cost estimate was terrifying, but the marginal cost of the specific expansion being considered was reasonable. The project went forward on those terms and came in under budget because they were thinking at the margin instead of getting paralyzed by the aggregate number.
The fifth foundation is opportunity cost, which is closely related to scarcity but operates at the decision level. Every choice has a cost, and that cost is whatever you gave up to make the choice. This sounds obvious until you actually try to apply it, because the opportunity cost is rarely the most obvious alternative. It's the best alternative you didn't pick. When I evaluate proposals now, I explicitly ask what the opportunity cost is, and more often than not, the people making the proposal haven't clearly identified it themselves. There's a limitation to keeping it this simple. These five foundations work beautifully for introductory analysis and rapid decision-making frameworks, but they break down when you encounter complex systems with feedback loops, behavioral irrationality, or institutional constraints that don't map cleanly onto standard models. I've seen analysts apply these foundations rigidly and miss structural issues that only showed up when they started tracking second-order effects. The foundations are necessary but not sufficient for serious work. If you want to actually use these foundations, start by applying them to everyday decisions before you tackle large-scale problems. Notice the scarcity constraints in your own time allocation. Pay attention to the incentives driving the people around you. Track where supply and demand imbalances show up in your local market. Think about the marginal benefit of each additional hour you spend on something. Name the opportunity cost explicitly every time you commit to a choice. Do this consistently for a few weeks and your analytical instincts will sharpen considerably.
Get the Full Details

The main pitfall I see people fall into is treating these foundations as isolated concepts rather than an integrated system. They're not. Scarcity creates the need for choice, incentives shape how people respond to scarcity, supply and demand coordinate those responses through prices, marginal analysis guides the actual decision at each point, and opportunity cost captures what's being sacrificed in every single one of those steps. They operate together, and pulling them apart weakens the analysis. The real skill is holding all five in your head simultaneously while evaluating a situation.