The Prioritized Checklist That Actually Works
The Money Guy Order of Operations is essentially a ranked checklist for where your extra dollars should go, starting from zero and moving upward. Bryan and Garret Bedford published it on their show years ago. It's become one of the most referenced personal finance frameworks on the internet because it sidesteps the endless debate about whether you should pay off debt or invest first. Instead of a debate, there's a list. You follow it in order until you run out of money, then move to the next item. I've seen people misuse this framework in ways that actually hurt them. The most common mistake is treating the list as rigid when it's supposed to be flexible around your personal situation. Here's how I think it actually works in practice.
What Are The Money Guy Financial Order Of Operations
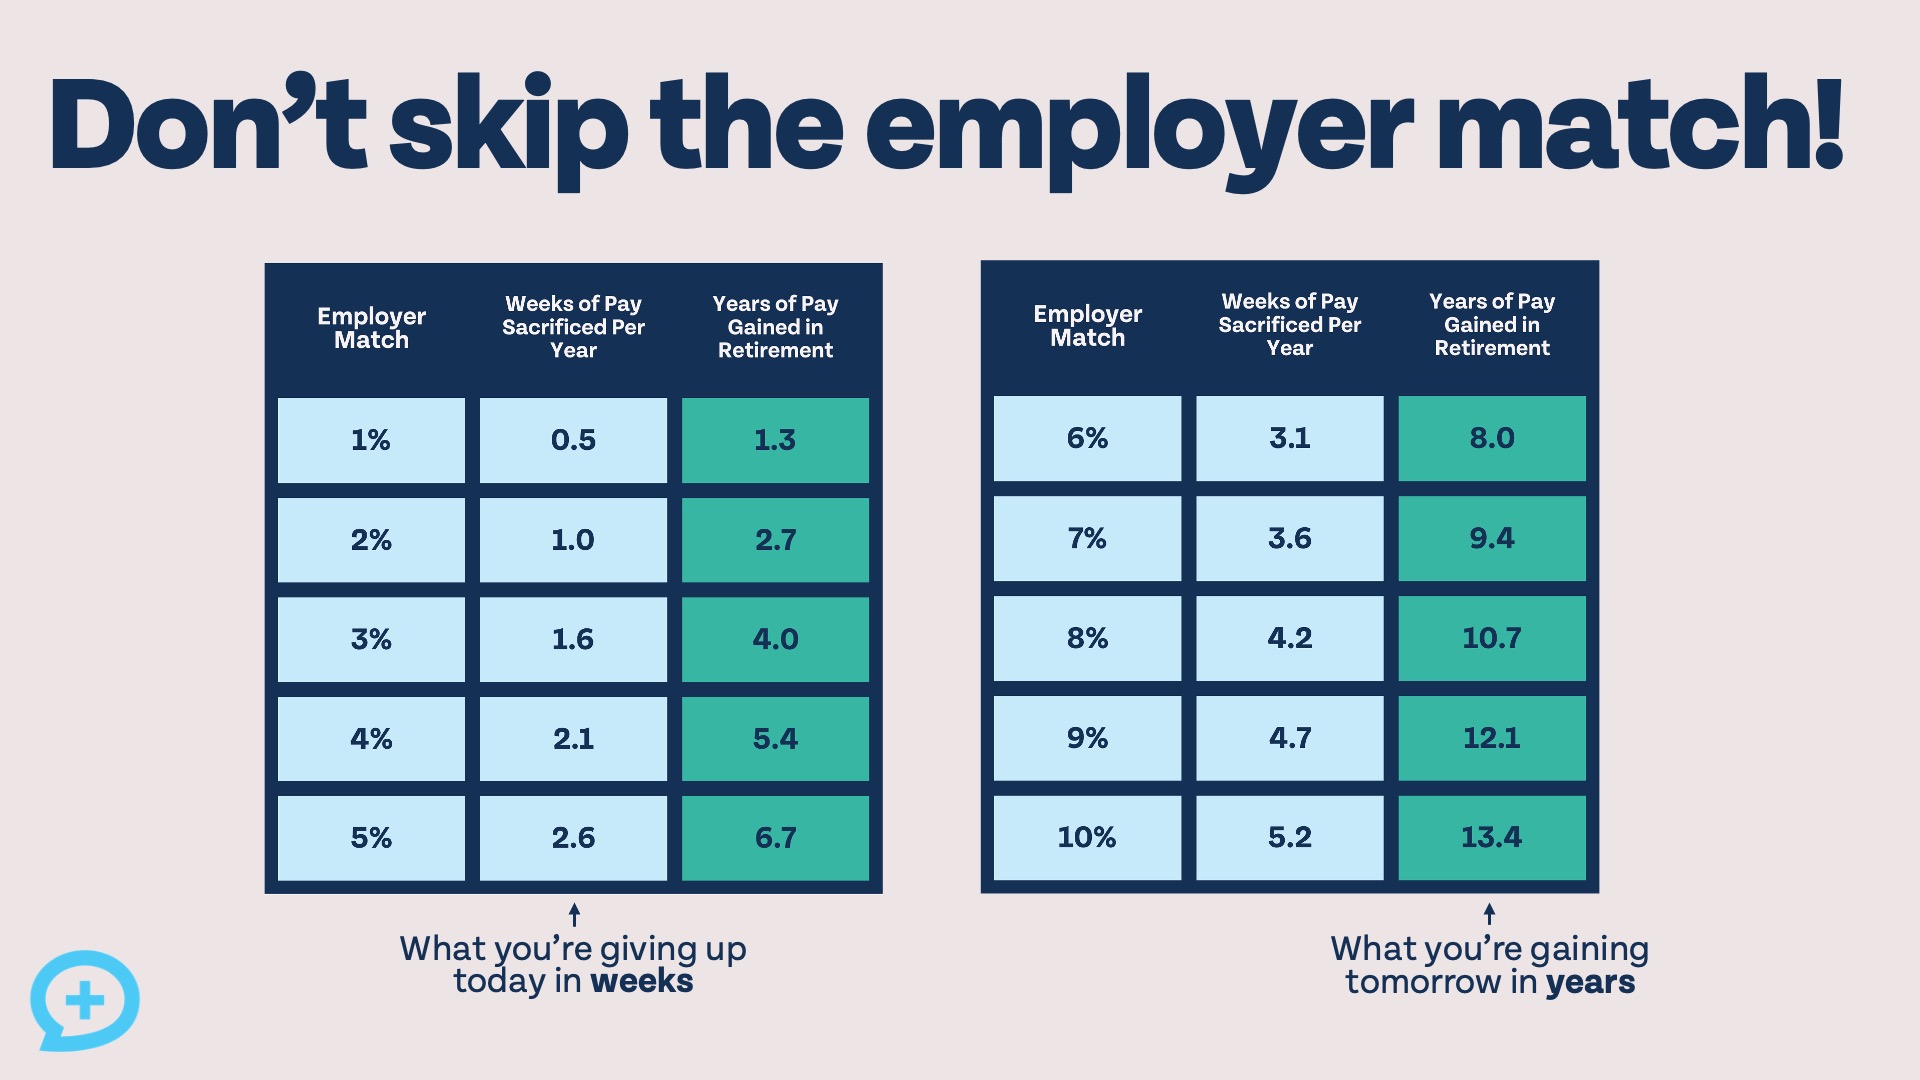
The current version runs about 15 steps. You don't need to memorize all of them. You just need to understand the logic so you can decide where you are and where you're going. The first few items are non-negotiable for almost everyone. After that, the order starts bending around tax situation, age, and employer plan specifics. Step one is getting the employer match. If your job offers a 401(k) match, you contribute enough to get it. This is free money. Not getting it is like working and then voluntarily turning down part of your paycheck. I had a client who was making six figures and not taking the match because he was "saving for a house." The house purchase got delayed by three years because he had less invested early on. The math doesn't work in his favor. Step two is paying off high-interest debt. I define that as anything above roughly 6 percent. Credit cards, personal loans, that sort of thing. The threshold matters because it intersects with step three.
Step three is the emergency fund. One to six months of expenses in a high-yield savings account. The exact number depends on your job stability, health situation, and household income structure. Dual-income households with stable jobs can lean toward three months. Single-income or commission-based households should target five or six. I once worked with someone who had a perfectly good emergency fund but it was sitting in a checking account earning 0.01 percent. We moved it to a HYSA overnight and it started earning meaningful interest within a month. Small change, but it's the kind of thing people overlook. Step four is a Roth IRA. You max it out if you can. Current limits are $7,000 for 2024, $8,000 if you're over 50. Income limits apply, so check those. The Roth is valuable because qualified withdrawals are tax-free. In a rising tax environment, that matters more than it used to. Step five is additional tax-advantaged investing beyond the employer match. This is where things get specific to your situation. Health Savings Account if you have a qualifying HDHP. Flexible Spending Account if your employer offers one. These are all pre-tax or tax-free buckets that reduce your taxable income.
Get the Full Details
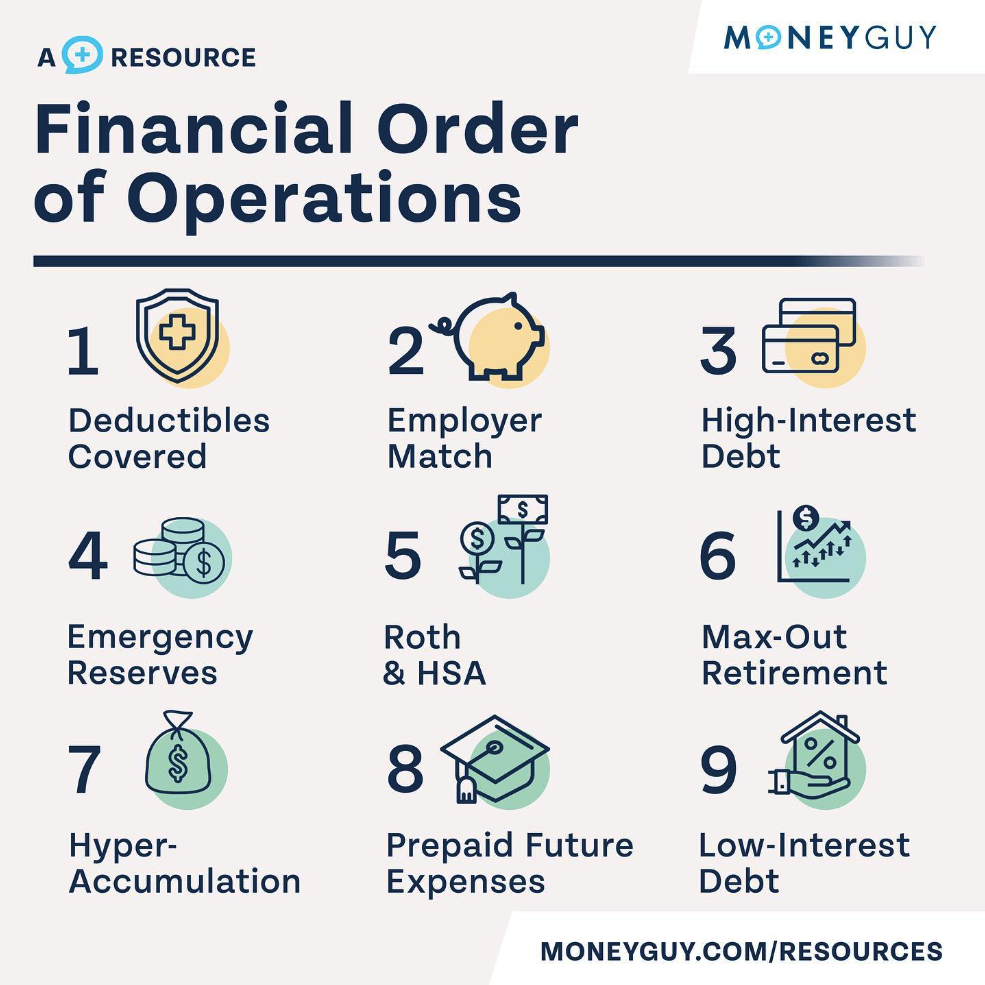
Step six is returning to the employer 401(k) to max it out. The 2024 limit is $23,000, $30,500 if you're 50 or older. Catch-up contributions are available for older workers and they matter significantly over a decade or two. Step seven is low-interest debt payoff. This is the debt below the threshold from step two. Mortgage, student loans at 4 percent, car loans. You can pay these off or carry them while investing elsewhere. The framework says pay them off, but the math often supports carrying them if your expected investment return exceeds the interest rate. The framework isn't mathematically optimal here. It's psychologically optimized. Getting rid of payments reduces stress and simplifies your financial life. Steps eight through fifteen cover things like maxing out a Backdoor Roth, contributing to a 529 plan, taxable brokerage accounts, extra mortgage payments, charitable giving strategies, and then discretionary spending. By the time you reach step ten, you're usually in a position where you've already built solid foundations and you're optimizing around the margins.
The framework has real limitations. It assumes you have enough disposable income to move through the steps in a reasonable timeframe. If you're living paycheck to paycheck, steps four through seven are academic. You work on steps one through three and stabilize. The framework also doesn't account well for high earners who hit income caps on Roth IRAs and need alternative strategies like the Backdoor Roth. It assumes traditional employment with access to employer-sponsored plans. Self-employed people or gig workers need to adapt the steps to SEP IRAs and Solo 401(k)s. One counter-intuitive thing about this framework: following it blindly can be worse than skipping around strategically. A 28-year-old with a 3 percent student loan and a maxed-out Roth IRA is better off investing extra dollars in a taxable account than rushing to pay down the student loan. The framework ranks low-interest debt payoff before taxable investing, but the math often contradicts that ranking. You should use the framework as a starting point, not a law. The underlying principle is tax efficiency and risk management. Once you understand that, you can rearrange the order to fit your actual numbers. Another thing people miss: the emergency fund step is often undervalued. People treat it as a checkpoint to speed past. But an insufficient emergency fund is the single biggest reason people derail this entire framework. A car repair or medical bill hits, you have no buffer, and you put everything on a credit card. Now you're back at step two and you've lost months of progress. Build the fund. Actually build it. Don't just acknowledge it exists and move on.
If you want the official list, it's published on the Money Guy website. I don't have a direct download link handy, but it's straightforward to find. The framework itself is free. The value is in understanding when to follow it and when to bend it based on your specific circumstances. Start at the top. Work downward. Revisit the order every year as your income, debts, and goals change.