Understanding Mortgage Points Before You Buy
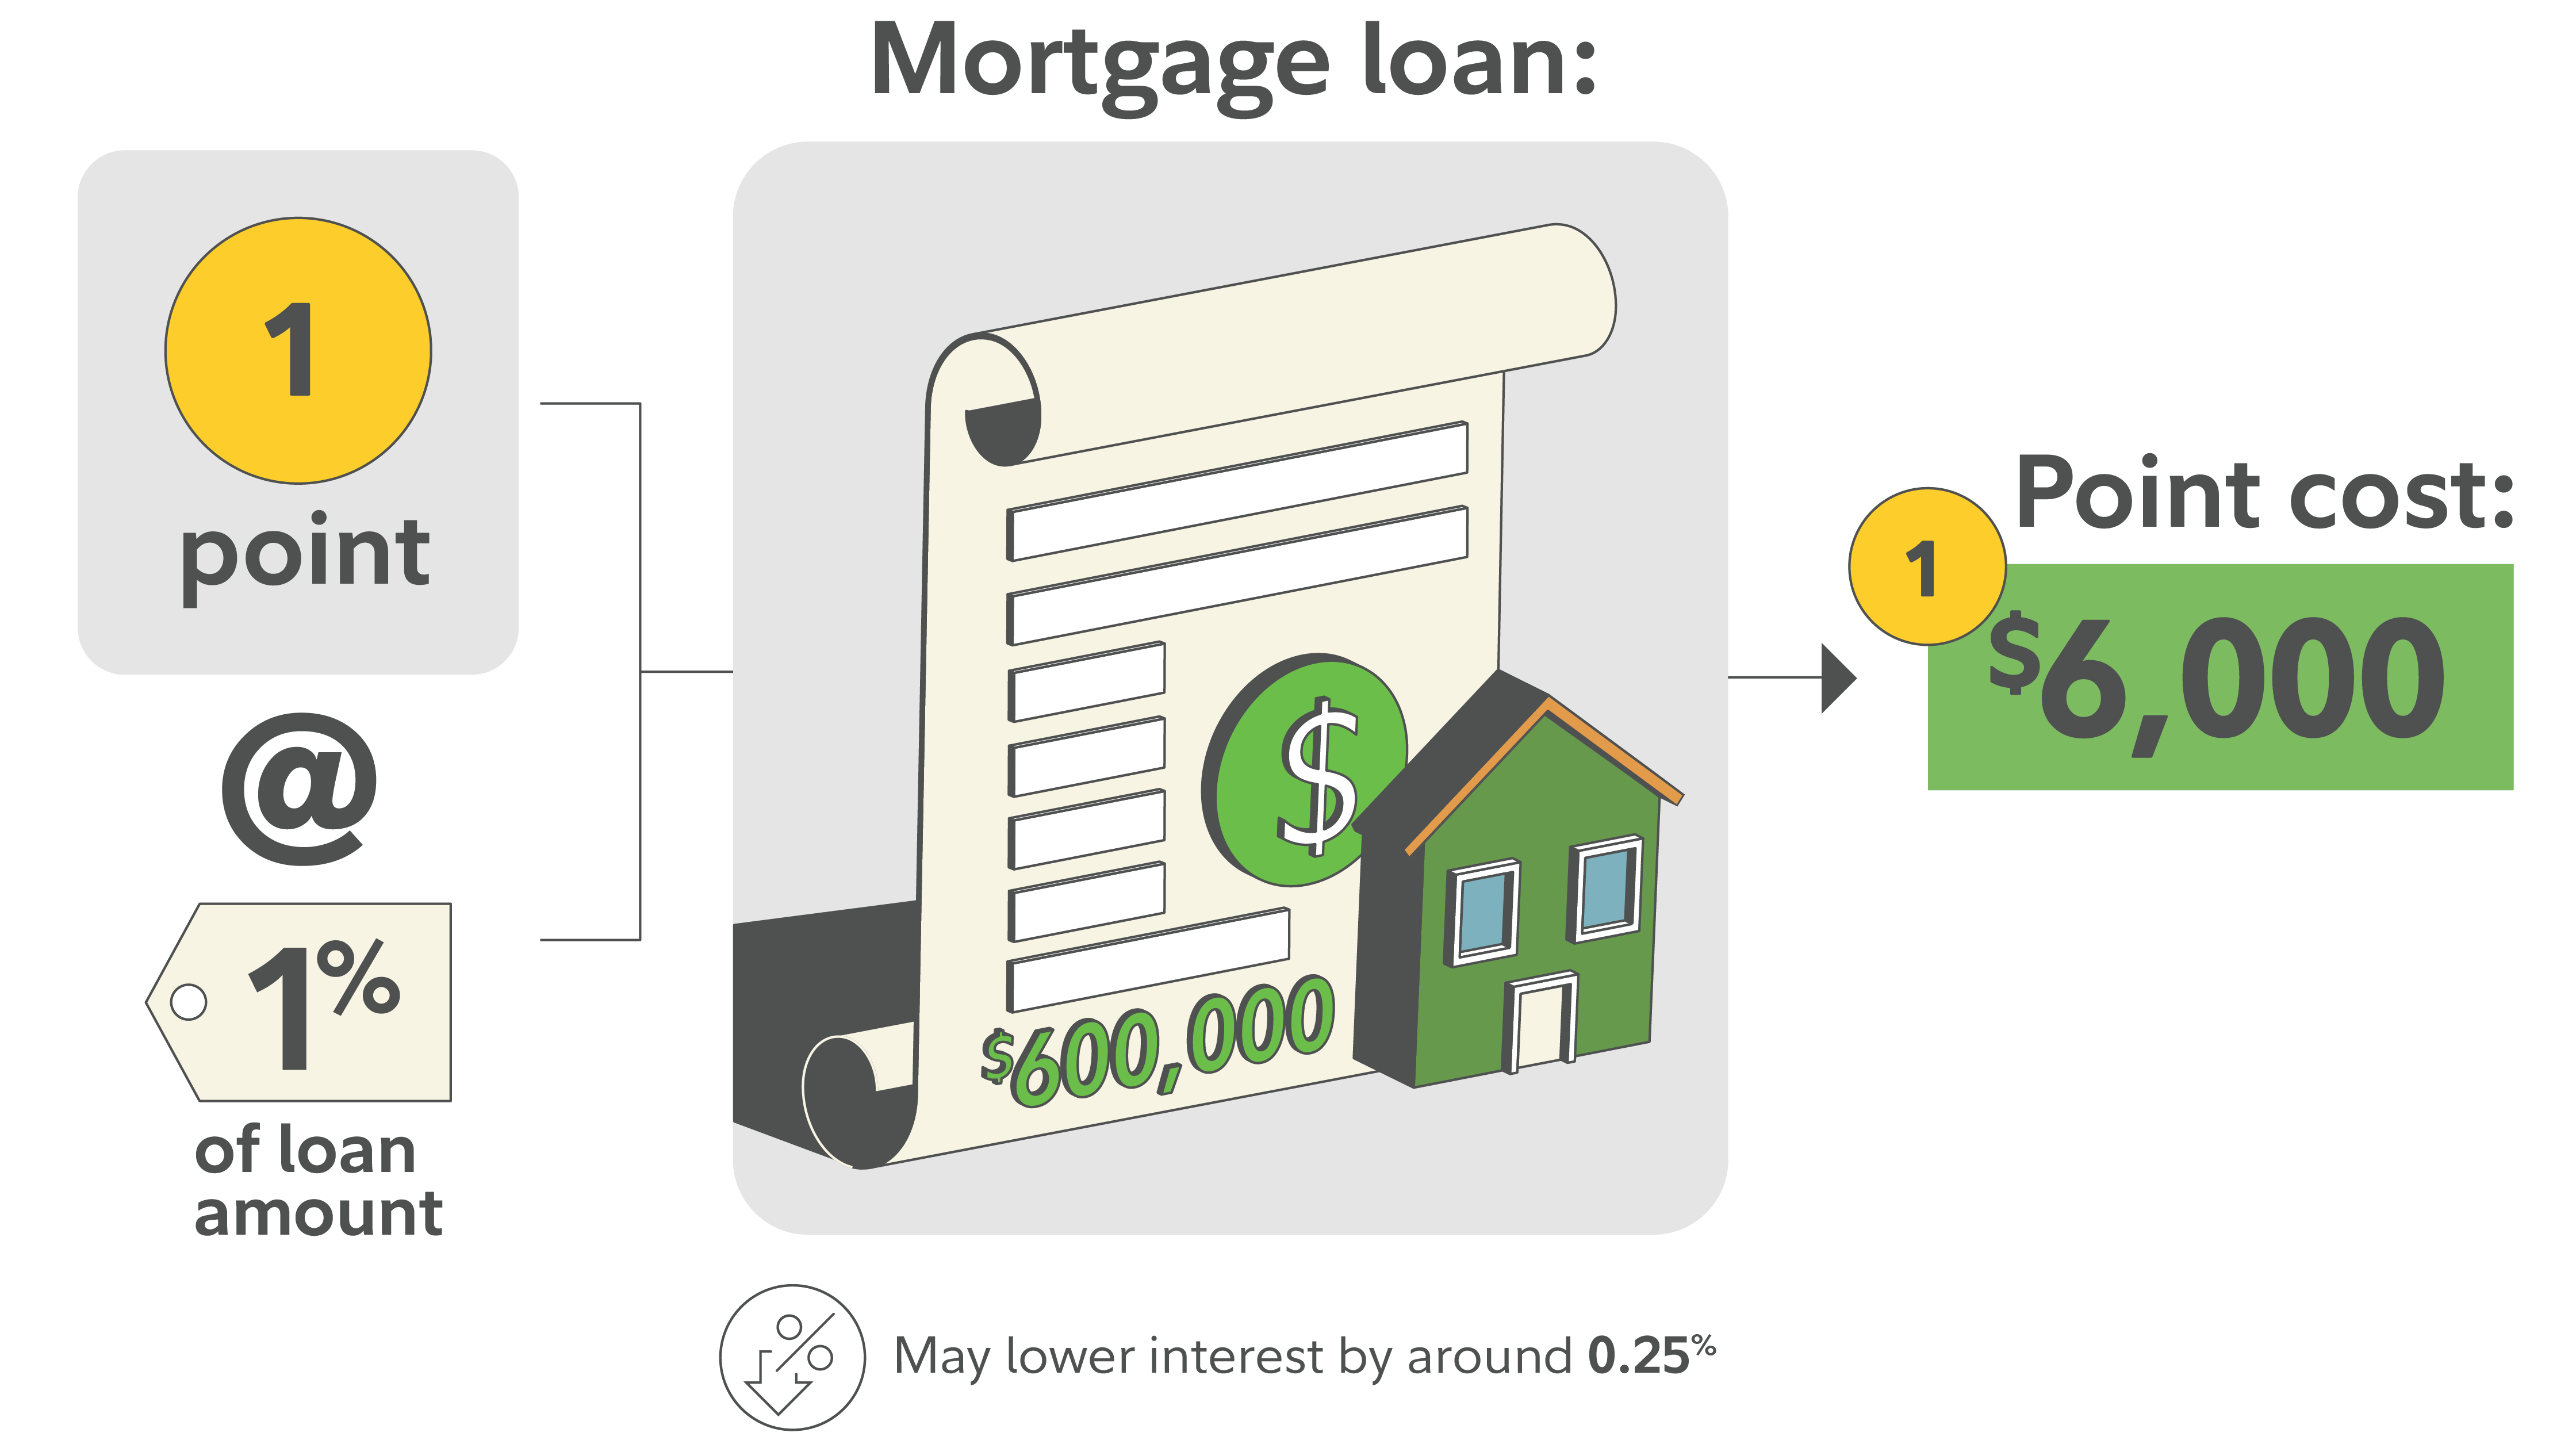
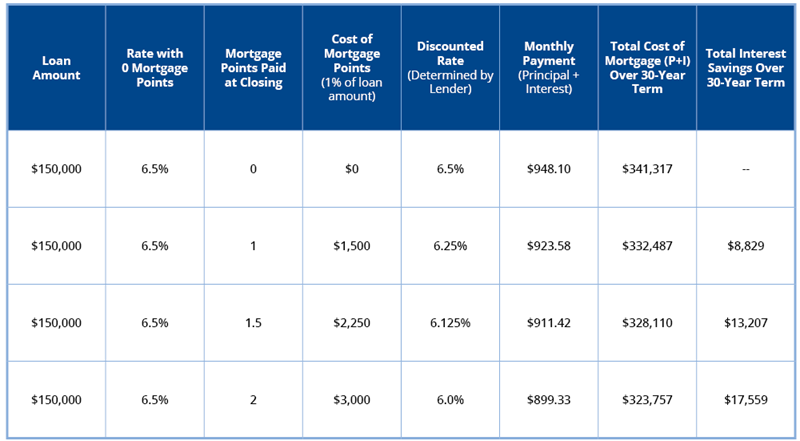
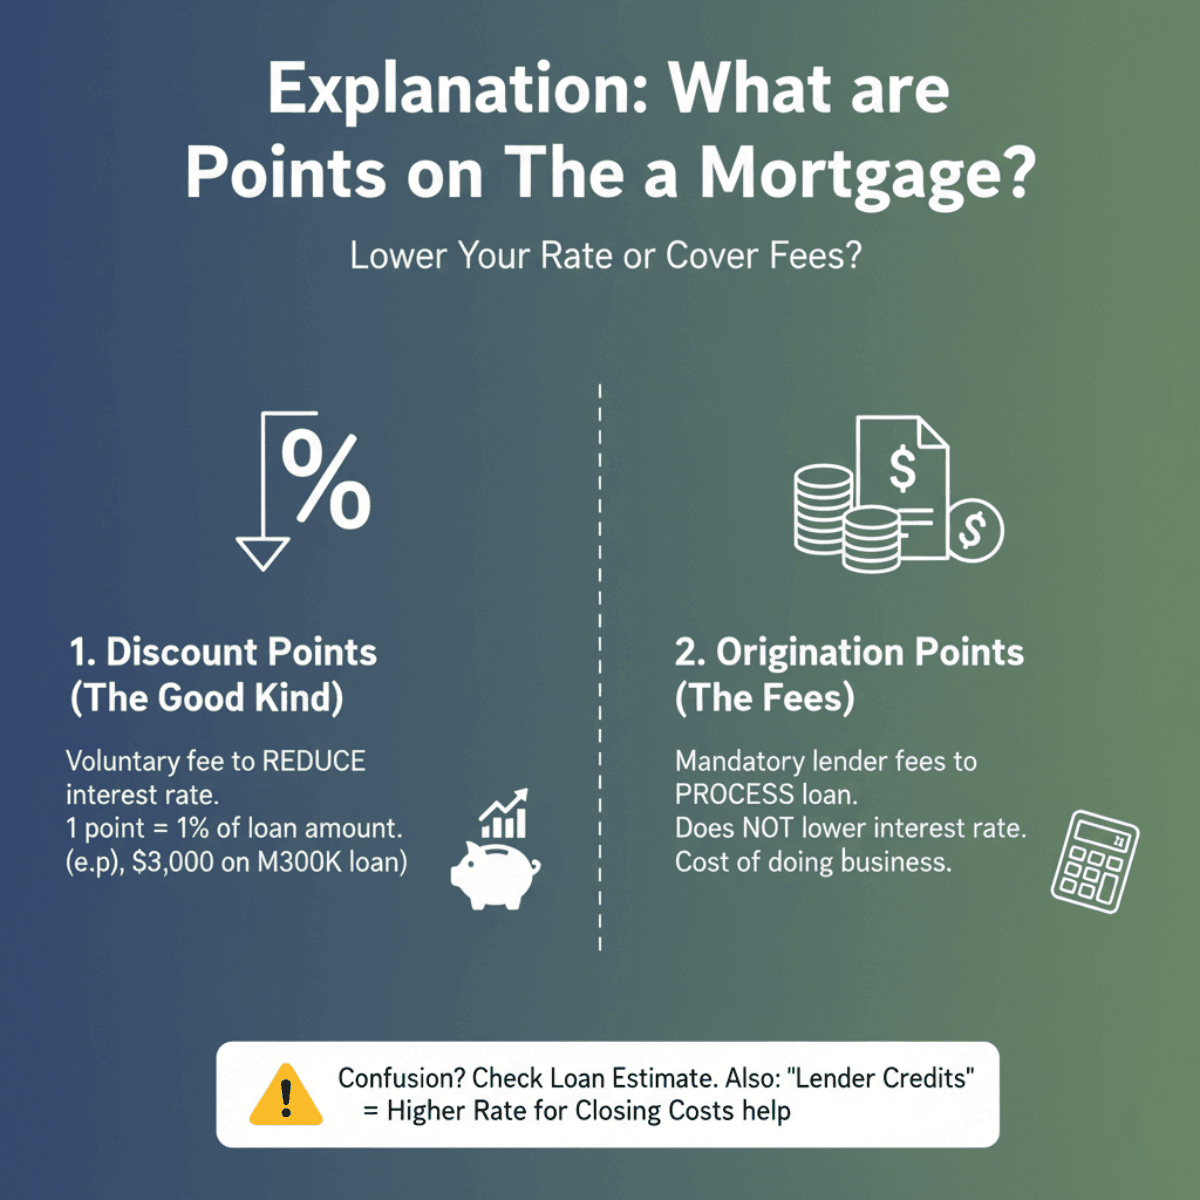
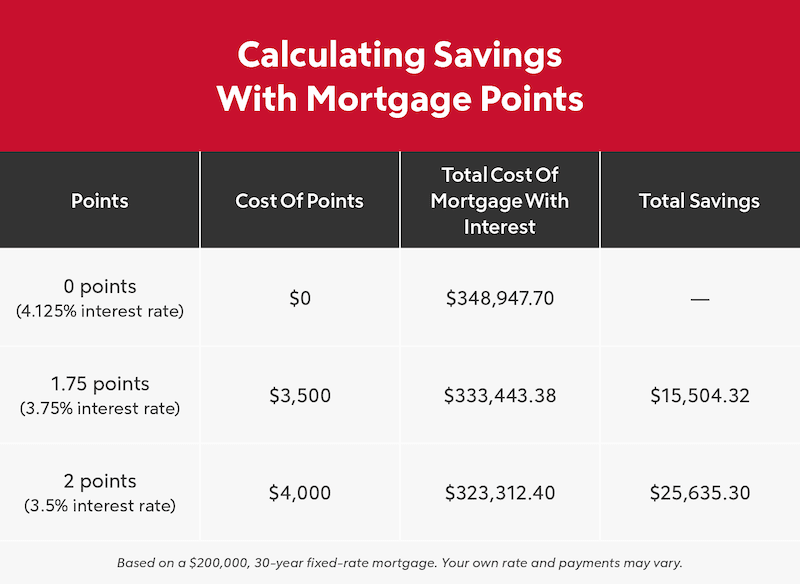
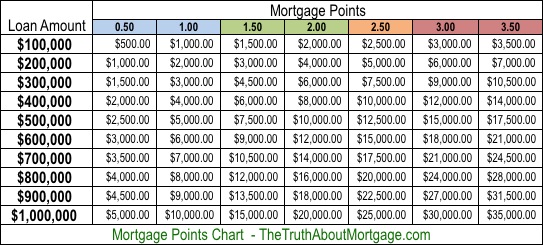
I spent years watching people confuse discount points with origination fees on closing documents. They sit there signing papers they think they understand, then wonder why their rate dropped by half a point when the broker said they'd get one full point off. It happens constantly. The confusion is partly structural — lenders package everything together so the breakdown isn't obvious without reading line by line. Discount points are an upfront payment you make to lower your interest rate over the life of the loan. One point equals one percent of the loan amount. Pay one point on a three-hundred-thousand-dollar loan, you're out three thousand dollars at closing. In return, the lender reduces your rate, usually by a quarter of a percentage point or a bit more, depending on the current market. That's the basic mechanic. The rest is math and timing.
What Are The Points In Mortgage Loans
The term covers two distinct things that most people lump together. Discount points lower your rate. Origination points are just lender fees dressed up to look the same. A legitimate discount point appears as "Discount Points" on your Loan Estimate under Section A, third line. An origination charge shows up under Section A, first line as "Charges for Government Services and Title" or as a separate "Origination Charges" line item. If a loan officer tells you they're charging you one point and it's not labeled clearly as a discount point, verify before you sign anything. The breakeven calculation is straightforward but most borrowers skip it. You divide the upfront cost by the monthly savings. Three thousand dollars in points that knock eighty-five dollars off your monthly payment breaks even in about thirty-five months. If you plan to move or refinance before month thirty-five, buying that point costs you money. I had a client who bought two points on a refi in 2019, moved to another state in 2021, and never recovered the cost. She asked me about it after the fact and the answer was exactly what I just described.
How Points Actually Work in Practice
Points are tax-deductible if you use them to buy down the rate on a primary residence, but that deduction has limits. Under current tax rules, you can generally only deduct points in the year they're paid if they meet the standard tests: the loan is for your main home, the points are clearly stated on the settlement statement, the charge follows local business practice, the amount doesn't exceed what's normally charged, and the points are computed as a percentage of the principal. If you refinance, points are amortized over the life of the loan instead of taken all at once. That's a detail people miss repeatedly. Here's a nuance nobody talks about enough. Points don't just affect your rate. They also change how the lender prices the loan in the secondary market. A lower rate with points means the loan is cheaper for an investor to buy. Some lenders will offer you a significantly better rate if you buy points because it makes their delivery easier, while other lenders actually prefer no points because they earn income from origination fees instead. You'll see different price sheets from the same lender depending on whether you're a cash buyer, a refinancer, or purchasing a second home. Points work differently across those scenarios. I ran into a specific edge case last year with a VA loan refi. The borrower wanted to buy two points to drop the rate, but the VA funding fee was already baked into the loan amount. The lender's calculator showed a negative break-even at eight years because the funding fee inflated the principal beyond what the rate reduction justified. The workaround was switching to a cash-out refi structure where the points were paid separately from the VA funding fee calculation. That changed the amortization entirely and dropped the breakeven to forty-two months instead of making the whole purchase nonsensical. It's the kind of thing that only shows up when you're dealing with government-backed loans and points simultaneously.
Get the Full Details
When Points Make Sense and When They Don't
Points make sense when you're staying in the home longer than the breakeven period plus a buffer. Thirty-six months is a comfortable minimum. Anything less and you're gambling that you won't sell, refinance, or face a life event that changes your plans. Rates also matter. If you're already getting a competitive rate without points, buying down further gets expensive quickly because each additional point gives you a smaller percentage reduction than the last. The first point typically buys you more basis points of reduction than the second or third point does. The opposite problem is also worth noting. There are situations where points do nothing for you because the rate you're quoted already includes a point buydown built in by the lender's pricing engine. I've seen this on jumbo loans where the advertised rate looks great but the Lock Commitment later reveals a point charge that was never discussed upfront. Always compare the interest rate plus points against the closing cost disclosure, not just the headline rate. The difference between an apparent two hundred dollar monthly savings and an actual thirty dollar savings is usually a hidden point charge. If you're buying a flipper property or investing in a rental, points are almost never the right move. You're holding for a short period, the debt service calculation favors keeping cash available, and the tax treatment changes entirely since investment property interest deductions operate under different rules. A portfolio lender with a higher base rate and no points often beats a conventional lender offering points on a rental property, simply because you preserve liquidity and avoid the long breakeven timeline.
Working with Lenders on Points
You can negotiate points the same way you negotiate rate. Ask for a Good Faith Estimate on two different scenarios: one with points, one without. Most lenders will give you both. If one scenario looks better than the other, tell them. They might adjust the or find a different program. I regularly see borrowers accept the first price sheet because they assume it's fixed. It's not. Lenders have pricing floors and they know you won't always check. Another practical tip: don't lock in a rate with points unless you've calculated the breakeven yourself. Lenders aren't obligated to explain the math to you. They'll hand you a disclosure and ask for a signature. Do the division before you commit. Three thousand dollars divided by however much your monthly payment actually drops. That number tells you everything you need to know about whether the purchase is worth it. The market shifts fast. A point that was a steal in March might be a waste by June if rates move the other direction. I had a borrower lock at 6.5 percent with one point in early 2024, then rates dropped to 5.75 percent before closing. He walked away from the points because the new rate at origination beat his locked rate even without the buydown. Worth checking if the market has moved between your lock and your closing date before finalizing whether you keep the points or drop them entirely.