Manual Underwriting Is Just Underwriting Without the Robot
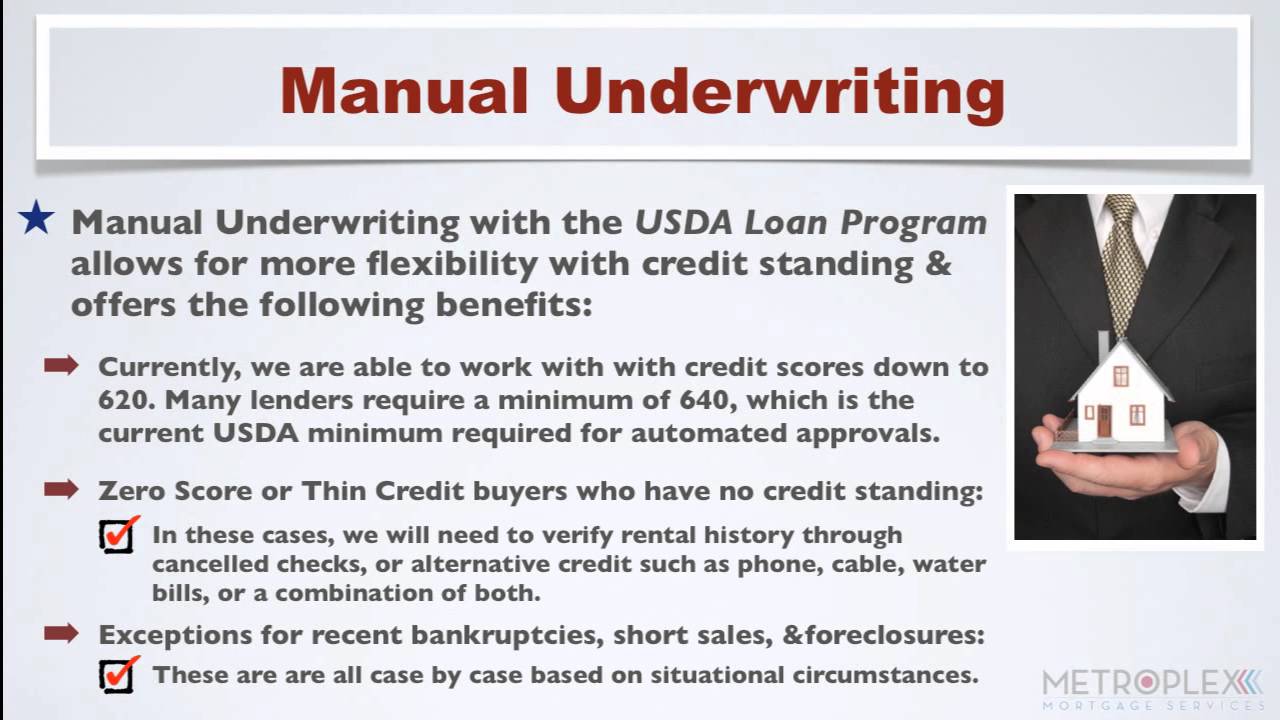
Pooled Mortgage Securities (PMS) and Fannie Mae/Freddie Mac sell-side guidelines dictate whether your loan gets run through an automated underwriting system or sent to a human. When the algorithm flags something, or when the borrower doesn't qualify under its rigid parameters, the file moves to manual underwriting. It sounds more official than it is. A person looks at the entire file and makes a judgment call instead of running a pass/fail scorecard. I need to clarify something most people get wrong. Manual underwriting is not a different program. It is the same FHA, USDA, or VA loan. The difference is only in how the risk assessment gets done. Conventional loans almost never go manual because Fannie and Freddie have nearly eliminated that path. If someone tells you they can do a manual conventional loan, they are likely selling you something that does not exist. You need government backing for this route.
What Banks Offer Manual Underwriting
Not every bank offers it anymore. I have watched this shrink significantly over the last eight years. Most large banks and many mid-tier lenders now push everything through automated systems. The ones that still maintain manual underwriting capabilities tend to be smaller community banks, credit unions, and some mortgage brokers who specialize in non-qm or government-backed niche lending. The real answer is not about which big bank name you recognize. It is about which lenders still have the staffing and appetite for files that do not fit neat boxes. You can find these lenders through a few practical channels. Mortgage brokers with established relationships underwrite manual files regularly because their job is matching borrowers to the right product. Independent mortgage bankers who do not operate as mega-lenders also tend to have manual teams. Some regional banks like Newtek Small Business, certain state-based housing finance agencies, and a handful of credit unions still advertise or quietly offer manual FHA underwriting. Do not call a national bank's main line and ask for manual underwriting. You will get transferred to someone who has never seen a manual file.
The Documentation Reality
Manual underwriting requires more paper, not less. The algorithm previously handled the verification. Now a human has to do it. Expect to provide explanation letters for every blemish in your credit, every deposit that looks suspicious, every employment gap. The better your documentation, the faster the process. Poor documentation makes a process that already runs 60 to 90 days stretch into months. Standard items include a credit explanation letter, rental history or prior mortgage payment records if you lack a full credit file, two years of tax returns with W-2s or 1099s, recent pay stubs, bank statements for the last two to three months, and sometimes a letter from your employer confirming job stability. For self-employed borrowers, you need the same tax documents plus a year-to-date profit and loss statement that reconciles with your tax return. Here is where I ran into a problem last year with a borrower who had a legitimate employment gap of fourteen months due to a layoff. His automated system would have denied him immediately. The manual underwriter required a solid explanation letter, proof of reemployment, and a letter from his previous employer confirming the layoff was not performance-related. The tricky part was that his previous employer used a third-party payroll system and would not issue anything on company letterhead. The workaround was getting a signed statement from the payroll company itself confirming the dates of employment and the reason for separation. That single document satisfied the underwriter because it came from a neutral third party with verifiable records.
Get the Full Details
The Tradeoffs Nobody Talks About
Manual underwriting is slower. That is the main cost. Automated systems produce decisions in minutes or hours. Manual files take anywhere from six weeks to three months depending on the lender's backlog. Interest rates may be slightly higher too, though not always. Some lenders price manual files at the same rate because the loan product itself has not changed. Others add a quarter point or so for the extra processing risk. There is also a hidden bottleneck. Fewer underwriters handle these files now. The industry has consolidated and many lenders let go of their manual staff. When your file lands with one of those remaining underwriters, you are competing with every other lender's manual backlog. A clear, well-organized file does not speed things up dramatically, but a messy file will delay it significantly. I have seen files sit for four to six weeks simply waiting on a missing document that should have been submitted on day one. The counterintuitive part is that manual underwriting is not necessarily a lower-barrier path. It does not mean easier approval. It means flexible approval. The same guidelines apply. The same minimum credit score and debt-to-income ratios usually still exist. The difference is that the underwriter can make exceptions when there are compensating factors. A strong rental payment history can offset a thin credit file. A large cash reserve can justify a higher debt-to-income ratio. A stable job in a difficult field can compensate for a recent dip in income.
I once worked a file where the borrower had a credit score of 620 with a single late payment from three years ago. The automated system denied it immediately. The manual underwriter approved it at 625 because the borrower had zero revolving debt, maintained six months of reserves, and had a ten-year track record of on-time payments before that one miss. The file was approved in about eight weeks, not because the standards were lower, but because the underwriter had room to weigh the whole picture.
When Manual Underwriting Actually Helps
It helps most when you have legitimate issues that look worse in an algorithm than they are in reality. Non-standard income types like commission-heavy roles, seasonal workers, and recent graduates with limited credit history often get crushed by automated systems. Manual underwriting gives them a fair shot. Borrowers with prior bankruptcies or foreclosures who have since rebuilt their finances also benefit. The algorithm sees the bankruptcy and stops. A human sees the bankruptcy, the five years of clean payments, and the steady income since. It does not help when your financial situation is genuinely distressed. If you have multiple recent delinquencies, a high debt-to-income ratio above 50 percent, or unresolved legal issues like active judgments or tax liens, manual underwriting will not save you. No amount of explanation letters changes the math. In those cases, the better move is to fix the underlying problems before applying. Pay down debts, clear small liens, establish a clean payment history for six to twelve months, and then try again with either an automated or manual path.
How to Actually Get One
Start by finding a lender who explicitly offers manual FHA, USDA, or VA underwriting. Ask them directly whether they have an in-house manual team or if they outsource to a third-party reviewer. In-house teams are generally faster because the file stays in the same system. Outsourced reviewers add a layer of communication delay. Prepare your documentation before you apply. Gather everything I listed above and organize it chronologically. Label each document clearly. A messy PDF with forty unnumbered pages is a file that gets delayed. A clean package with tabs and a cover sheet takes significantly less time to process. I estimate that good organization can cut processing time by two to three weeks compared to a disorganized file, which is meaningful when you are already dealing with a slow process. Do not expect this to be cheap. Processing fees may be higher. Appraisal costs remain the same. Title and closing costs do not change. The main additional cost is time and the potential for a slightly higher rate. Some lenders also charge a manual review fee ranging from five hundred to fifteen hundred dollars, though this varies widely by market and lender.
The worst thing you can do is apply to ten lenders simultaneously with a manual file request. Each application triggers a hard credit pull. Multiple pulls within a short window compound the damage to your score. Pick one or two lenders who you trust and give them your full cooperation. Speed comes from responsiveness, not from shopping around during the process.
A Hard Truth About Outcomes
Manual underwriting approval rates are not dramatically higher than automated ones. The population of borrowers who end up in manual underwriting is already a filtered group. These are the borrowers who did not pass the automated checks. You are not beating the system. You are getting a second look. That second look is valuable, but it is not a backdoor. If the compensating factors are not strong enough, the file gets denied manually just like it was denied automatically. I have seen that happen repeatedly. The rejection letter just comes from a person instead of a computer. There is also the matter of loan limits and product availability. Not all manual underwriters can do USDA or VA. Some only handle FHA. Some cannot do jumbo or non-conforming manual files at all. Verify exactly which programs your chosen lender can process manually before you invest time in the application. Wasting three weeks on a file only to find out the lender cannot do your specific loan type is a common mistake. If manual underwriting is not an option or does not work for your situation, the alternatives are limited but real. You can wait and rebuild your credit profile over six to twelve months. You can look for a co-signer with strong credit. You can explore state housing finance agency programs that sometimes have more flexible guidelines. Or you can consider a rent-to-own arrangement if you are simply trying to get into a home while you fix other issues. None of these are ideal, but they are more realistic than expecting a manual file to rescue a fundamentally unqualified application.