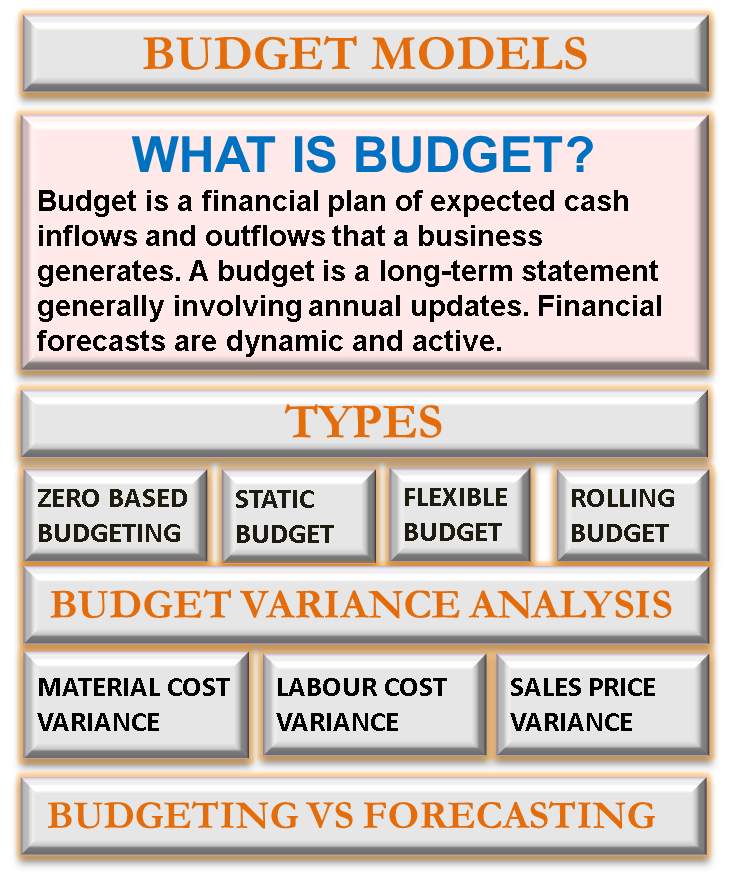
The Practical Reality of Budgeting
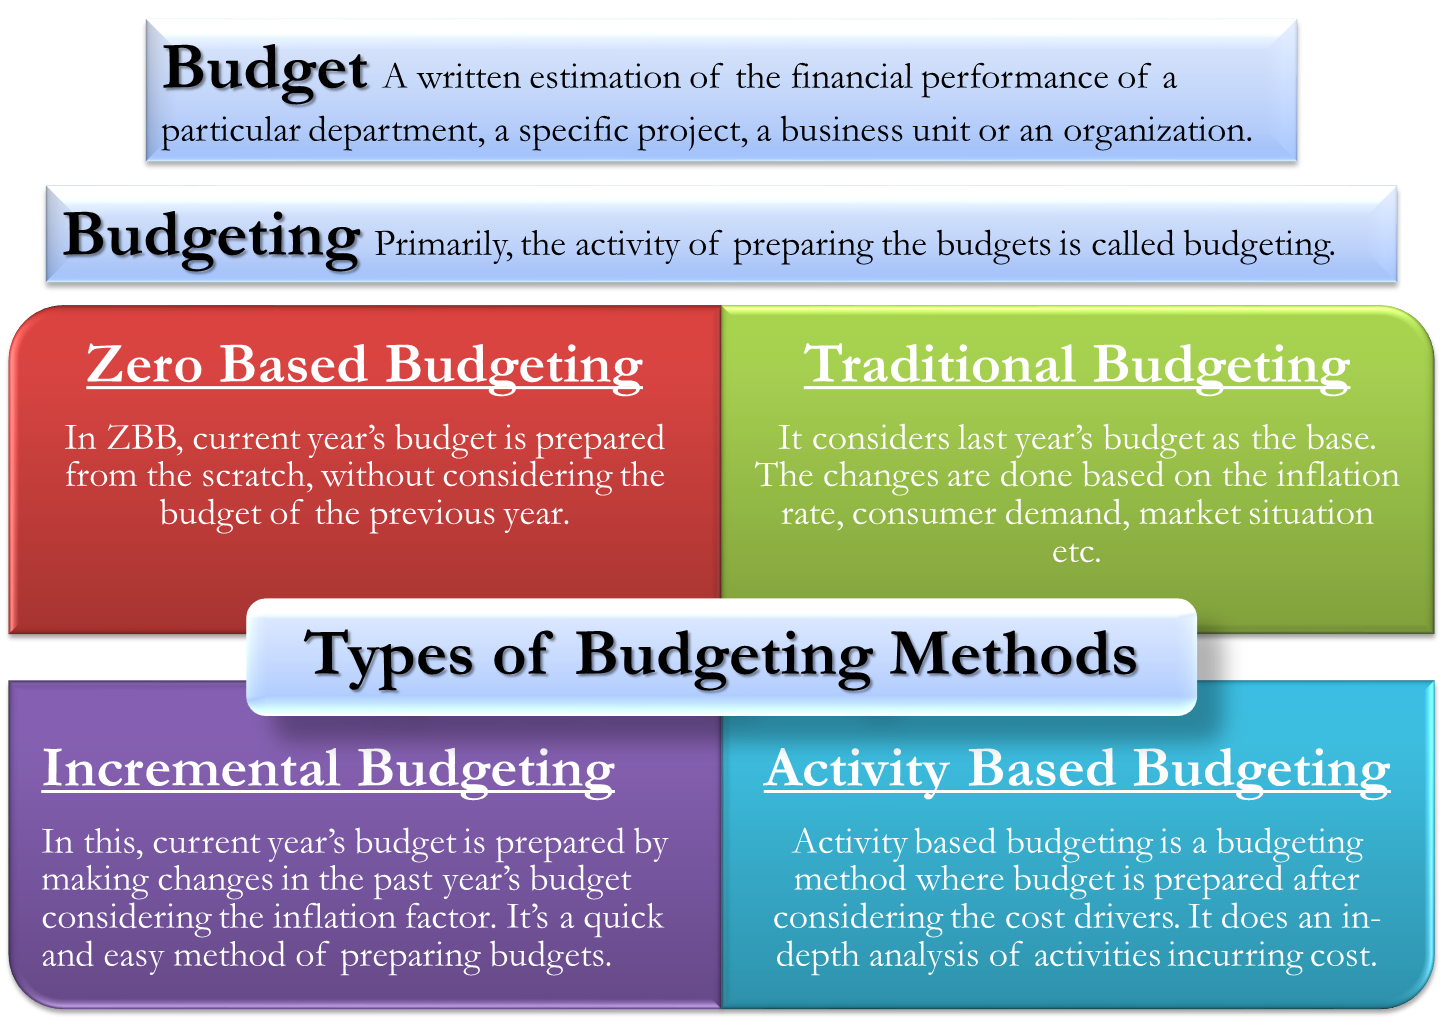
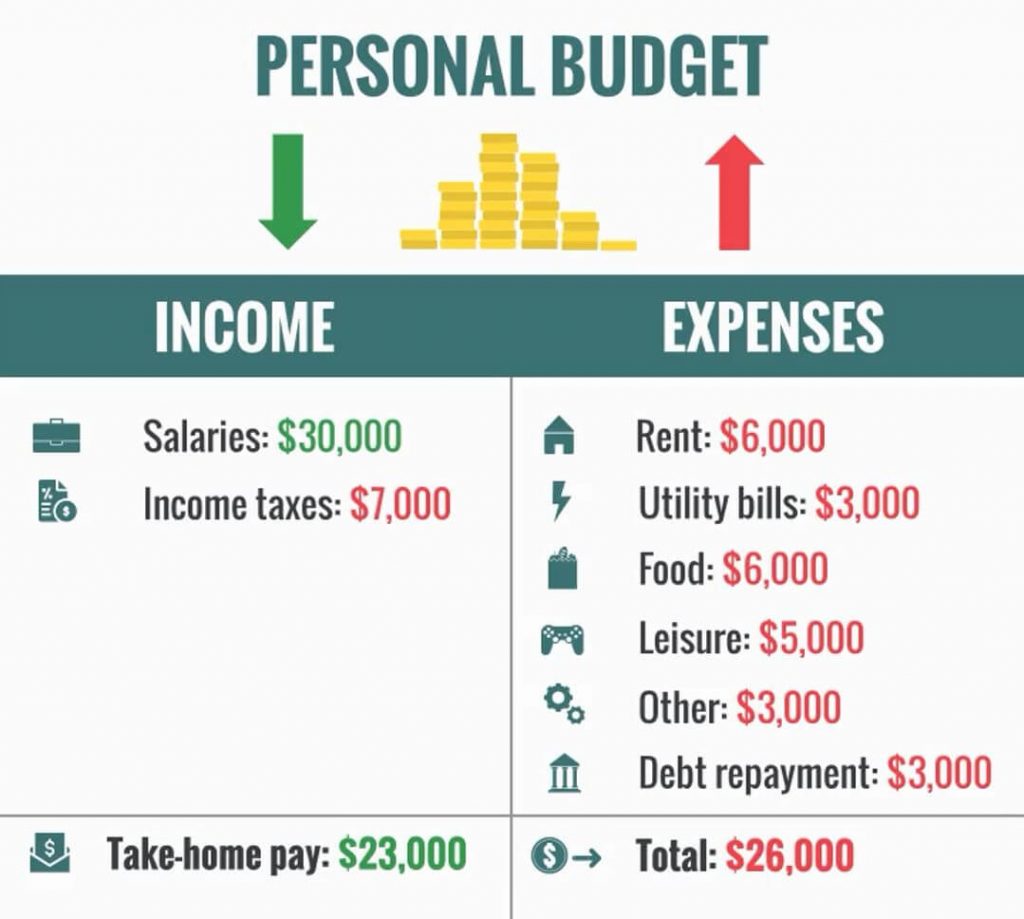
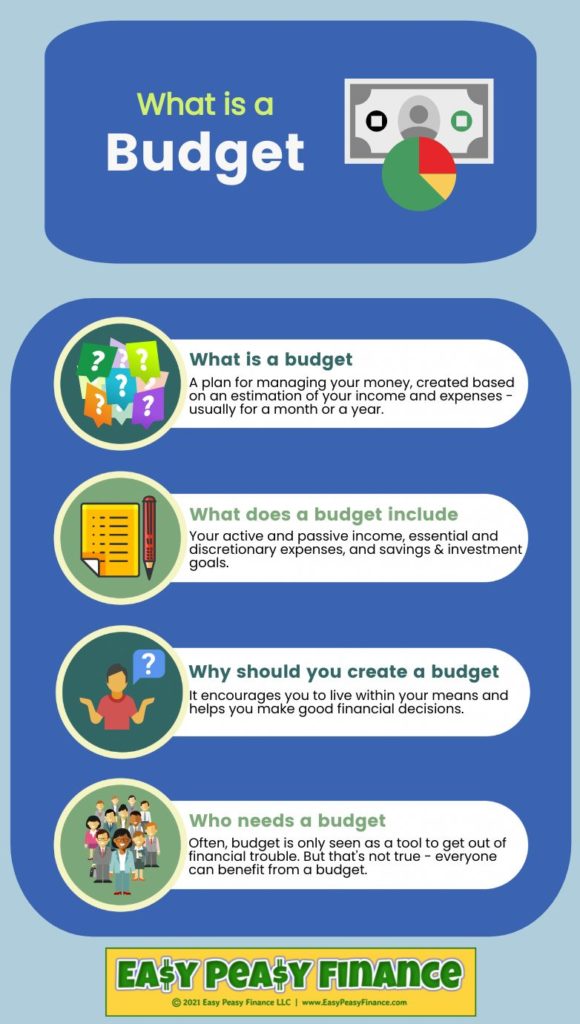
A budget is simply a plan that matches your expected income against your expected spending over a set period. Most people hear "budget" and immediately think of restriction, but in practice it's just giving every dollar a job before the month starts. That's it. The reason it matters is that without one, money leaks everywhere through small unbilled purchases, automatic subscriptions you forgot about, and emergency expenses that have nowhere to come from. Here's what actually happens when you build one. You take your net monthly income, list your fixed obligations—rent, utilities, insurance, minimum debt payments—and then allocate the remainder to variable categories like groceries, fuel, dining out, and savings. The remaining buffer after everything is your margin for error. Most first attempts fail because people underestimate variable costs by 30 to 40 percent. They write down $400 for groceries but actually spend $550. The fix is tracking three months of real receipts before you ever commit to a projected number. I ran into a specific edge case once with a freelance client who had wildly irregular income. Some months brought in eight thousand dollars, other months barely hit two thousand. Standard zero-based budgeting didn't work because there was no stable baseline. What I had them do was average their rolling twelve-month income, divide by twelve to get a "safe monthly income," and build the budget around that lower number. Any surplus in high-earning months went straight into a dedicated buffer account that covered the shortfall in lean months. This approach eliminated the anxiety of living paycheck to paycheck even on an irregular income. The tradeoff is that you always budget for your worst month, which means comfortable months feel artificially tight until the buffer rebuilds.
There are two common pitfalls that catch people off guard. The first is the categorization trap, where you create too many budget buckets and spend more time managing categories than saving money. Twelve categories is plenty. If you're tracking forty line items, you'll abandon it within six weeks. The second pitfall is ignoring recurring subscriptions. A study of personal finance data showed the average households between $300 and $500 annually on forgotten subscriptions alone. Go through your bank statements for the past ninety days and cancel anything you haven't used in thirty days. That alone often frees up enough room to fund the rest of the budget. The tool you use matters less than consistency. Spreadsheets work fine for people who like manual control. Apps like Mint, YNAB, or even a simple Google Sheet with automated bank feeds handle the bookkeeping faster. The ones that actually work are the ones you check weekly, not annually. A budget checked once a year is a museum exhibit. You need to see where the money went before the month ends so you can adjust course. One counter-intuitive thing worth noting: budgets that leave zero room for fun tend to fail faster than budgets with generous entertainment categories. Restriction breeds resentment, and resentment leads to unchecked spending anyway. Allocate a realistic "fun money" category and treat it as non-negotiable. When you allow yourself to spend $200 without guilt each month, you're far less likely to blow $800 on something impulsive later. The numbers work out the same, but the psychological sustainability is completely different.
Budgeting also has hard limitations. It does not protect you from income loss, medical emergencies, or major unexpected repairs unless you've specifically built sinking funds for those events. A budget without an emergency fund is just a fragile plan waiting to break. If you don't have three to six months of expenses saved, the budget should prioritize that over everything else until it's in place. No investment strategy or side hustle discussion matters if a single flat tire wipes out your monthly cash flow. The process itself is straightforward: calculate net income, list fixed expenses, assign variable expenses with a conservative buffer, add savings and debt repayment, verify that everything sums to zero or below, then track actual spending against it every week. Anything consistently over by more than ten percent gets a revised number the following month. After three to four cycles, your budget starts reflecting reality instead of wishful thinking. That's when it actually becomes useful.
Get the Full Details