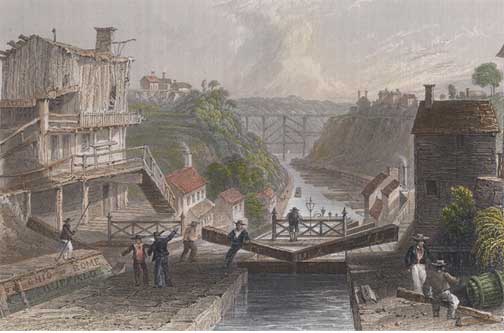The Year That Broke Britain's Economy and Redrew the Map of South America
1825 was a quietly destructive year that most people scrolling through history textbooks skip over. It wasn't marked by wars on the same scale as 1815 or 1826. It had no singular famous battle. But it did something arguably more important: it demonstrated, for the first time in the modern era, how quickly a financial panic could destroy wealth across multiple continents within months. The Panic of 1825 is what I call a textbook failure of speculative mania. It started in Latin American mining stocks and ended with banks collapsing in Glasgow, London, and New York. The mechanism was simple and ugly. British investors had thrown hundreds of millions of pounds into newly independent Latin American governments and mining ventures. When those investments turned out to be largely fraudulent or worthless, the whole structure collapsed. Credit vanished overnight. Bank runs followed. The Bank of England had to print emergency currency just to keep the country from grinding to a halt.
What Happened In 1825
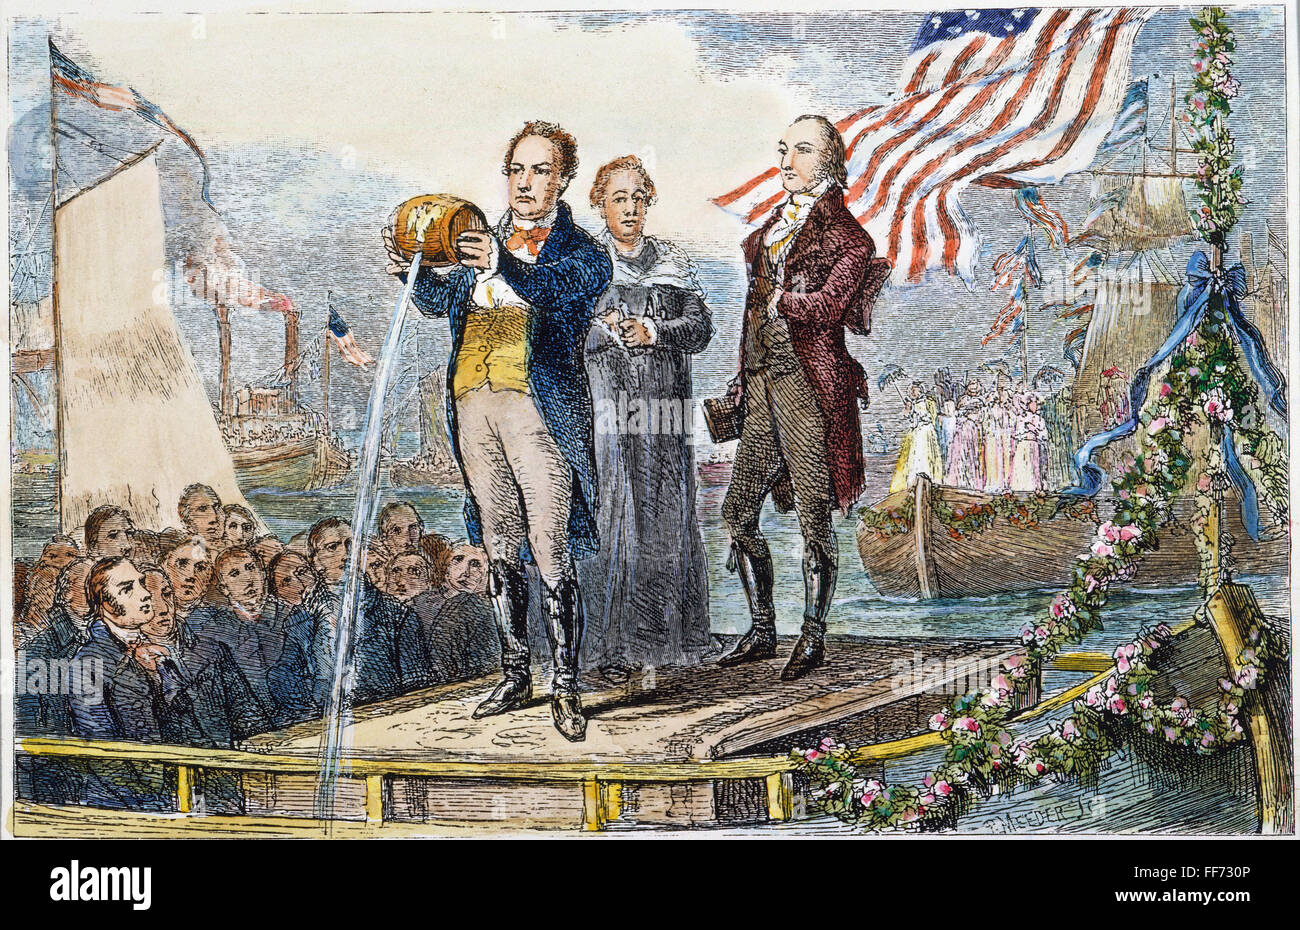
The financial panic dominated the year, but it sat alongside several other events that shaped the modern world. Brazil declared independence from Portugal on September 7, 1825, and by December Portugal formally recognized it. This redrew the map of South America and set the stage for decades of political instability in the region. The Greek War of Independence also saw major developments, with the Treaty of Constantinople in July forcing the Ottoman Empire to accept Greek autonomy under Egyptian and British naval pressure. In North America, the Erie Canal opened in 1825 and immediately changed the economics of the entire continent. Before the canal, shipping goods from Buffalo to New York City took three weeks and cost roughly $100 per ton. After the canal opened, the trip dropped to eight days and $10 per ton. This single infrastructure project shifted the center of American economic gravity toward the Great Lakes and made New York City the dominant port in the country within a decade. There was also the famous eruption of Mount Vesuvius in 1825, which though less devastating than the 79 AD event, produced significant lava flows that destroyed several villages. Scientists at the time used this eruption to study volcanic mechanics in ways that contributed to the emerging field of volcanology. The French government funded an expedition that measured gas emissions and mapped lava channels, which became reference material for decades of geological research.
I remember working through archival material on the Panic of 1825 a few years back, trying to trace how exactly the contagion moved from Glasgow back to London. The specific problem I hit was that most accounts treat the panic as if it happened all at once. It didn't. The first Glasgow bank to fail was the Union Bank in late October. News traveled by ship, so London didn't hear about it until early November. By then, the Bank of England had already started raising its discount rate defensively, which only accelerated the panic. The counterintuitive part is that the Bank of England's attempt to contain the crisis actually made it worse. Raising rates meant borrowers couldn't refinance, which caused more defaults, which caused more bank failures. It's a pattern that shows up repeatedly in financial history, and 1825 is one of the clearest early examples.
Get the Full Details

How the Speculative Bubble Formed
The setup for the panic began during the Napoleonic Wars. British capital had been sitting idle, too scared to invest overseas while the war continued. Once peace arrived in 1815, that capital needed somewhere to go. Low interest rates and a general sense of optimism created fertile ground for speculation. Investors weren't looking for steady returns. They were looking for the kind of windfall that came from betting on distant, exotic markets. Latin America was the target. Spain and Portugal had just lost most of their American colonies. New governments had formed, they needed capital, and they offered bonds at attractive yields. British brokers packaged these bonds and sold them to retail investors who had never thought about international finance before. The problem was that most of these ventures didn't actually generate the returns they promised. Some of the mining companies were shell operations. Several of the new governments had no real taxation infrastructure. A number of the prospectuses were outright fabrications. The bubble inflated through 1824 and peaked in early 1825. Share prices in Latin American mining stocks reached levels that had no rational connection to the underlying assets. Then it popped. The exact trigger is debated among economic historians. Some point to the dismissal of Lord Liverpool's government and the resulting political uncertainty. Others argue it was simply a matter of too many bonds hitting the market at once, overwhelming investor appetite. The result was the same either way.
The Mechanics of the Collapse
When the panic hit, it moved through the financial system the way a disease moves through a crowded city. The first casualties were the smaller provincial banks. These institutions had lent heavily to speculators and hadn't diversified. When the speculators defaulted, the banks couldn't recover anything. Depositors rushed to withdraw their money, which forced the banks to call in loans at fire-sale prices, which destroyed even more value. The Bank of England found itself in an impossible position. It was simultaneously the lender of last resort and a commercial bank with its own profit interests. It tried to stem the bleeding by calling in its own loans, which made things worse. Then it reversed course and started lending freely, but the damage was already done. Over 60 banks failed during the panic. The total value of corporate failures has been estimated at around £40 million, which was a staggering amount for the period. One thing that catches people off guard is how quickly the panic spread internationally. America felt it almost immediately because American banks had invested heavily in Latin American securities too. The collapse contributed to the broader economic downturn that lasted through 1826 and 1827. European markets outside Britain were less affected, but the psychological impact traveled fast. Confidence in joint-stock companies and foreign investment took years to recover.
The Aftermath and Lessons
The Panic of 1825 had real policy consequences. It led to the Select Committee on Joint Stock Companies in 1826, which examined whether the chartering process for banks and corporations needed reform. The recommendations were modest but they planted the seeds for later regulatory frameworks. It also influenced the thinking of economists like David Ricardo and Thomas Tooke, who used the crisis to develop theories about banking and credit that are still studied today. For anyone studying this period, the key insight is that the panic wasn't caused by a single mistake. It was a chain of errors: loose credit, speculative fever, inadequate due diligence, defensive central banking, and a lack of transparency in the markets. Each piece made sense in isolation. Together they produced a disaster. That's the pattern that repeats throughout financial history, from the South Sea Bubble to the 2008 subprime crisis. The Erie Canal's opening later that same year is worth keeping in mind as a contrast. While the financial sector was burning, physical infrastructure was being built that would generate real, measurable economic value. The canal paid for itself within a few years. The Latin American investments paid for nothing. That's the kind of distinction that matters when you're evaluating where capital goes during periods of easy money.