Understanding the basics
A 1065 is the US individual income tax return used by partnerships to report their income, gains, losses, deductions, and credits. It's not a tax form itself — partnerships don't pay income tax at the entity level. Instead, the form flows information through to each partner's individual return via Schedule K-1. I've spent years watching businesses misuse these, and the most common mistake is treating a 1065 like a corporate return. It's fundamentally different. The compliance burden lands on the partners, not the partnership.What Is A 1065 Partnership
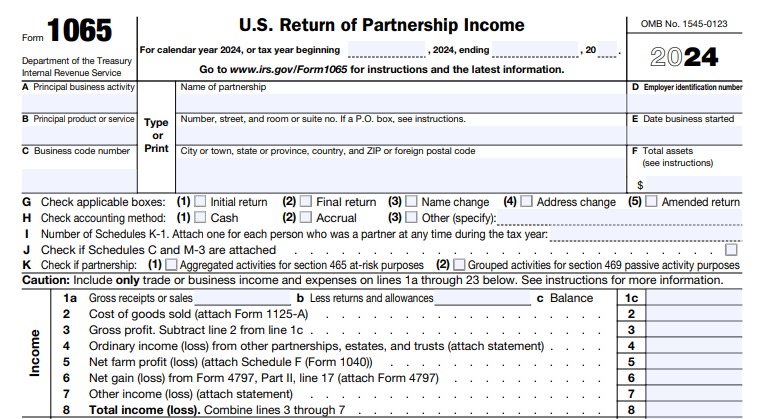
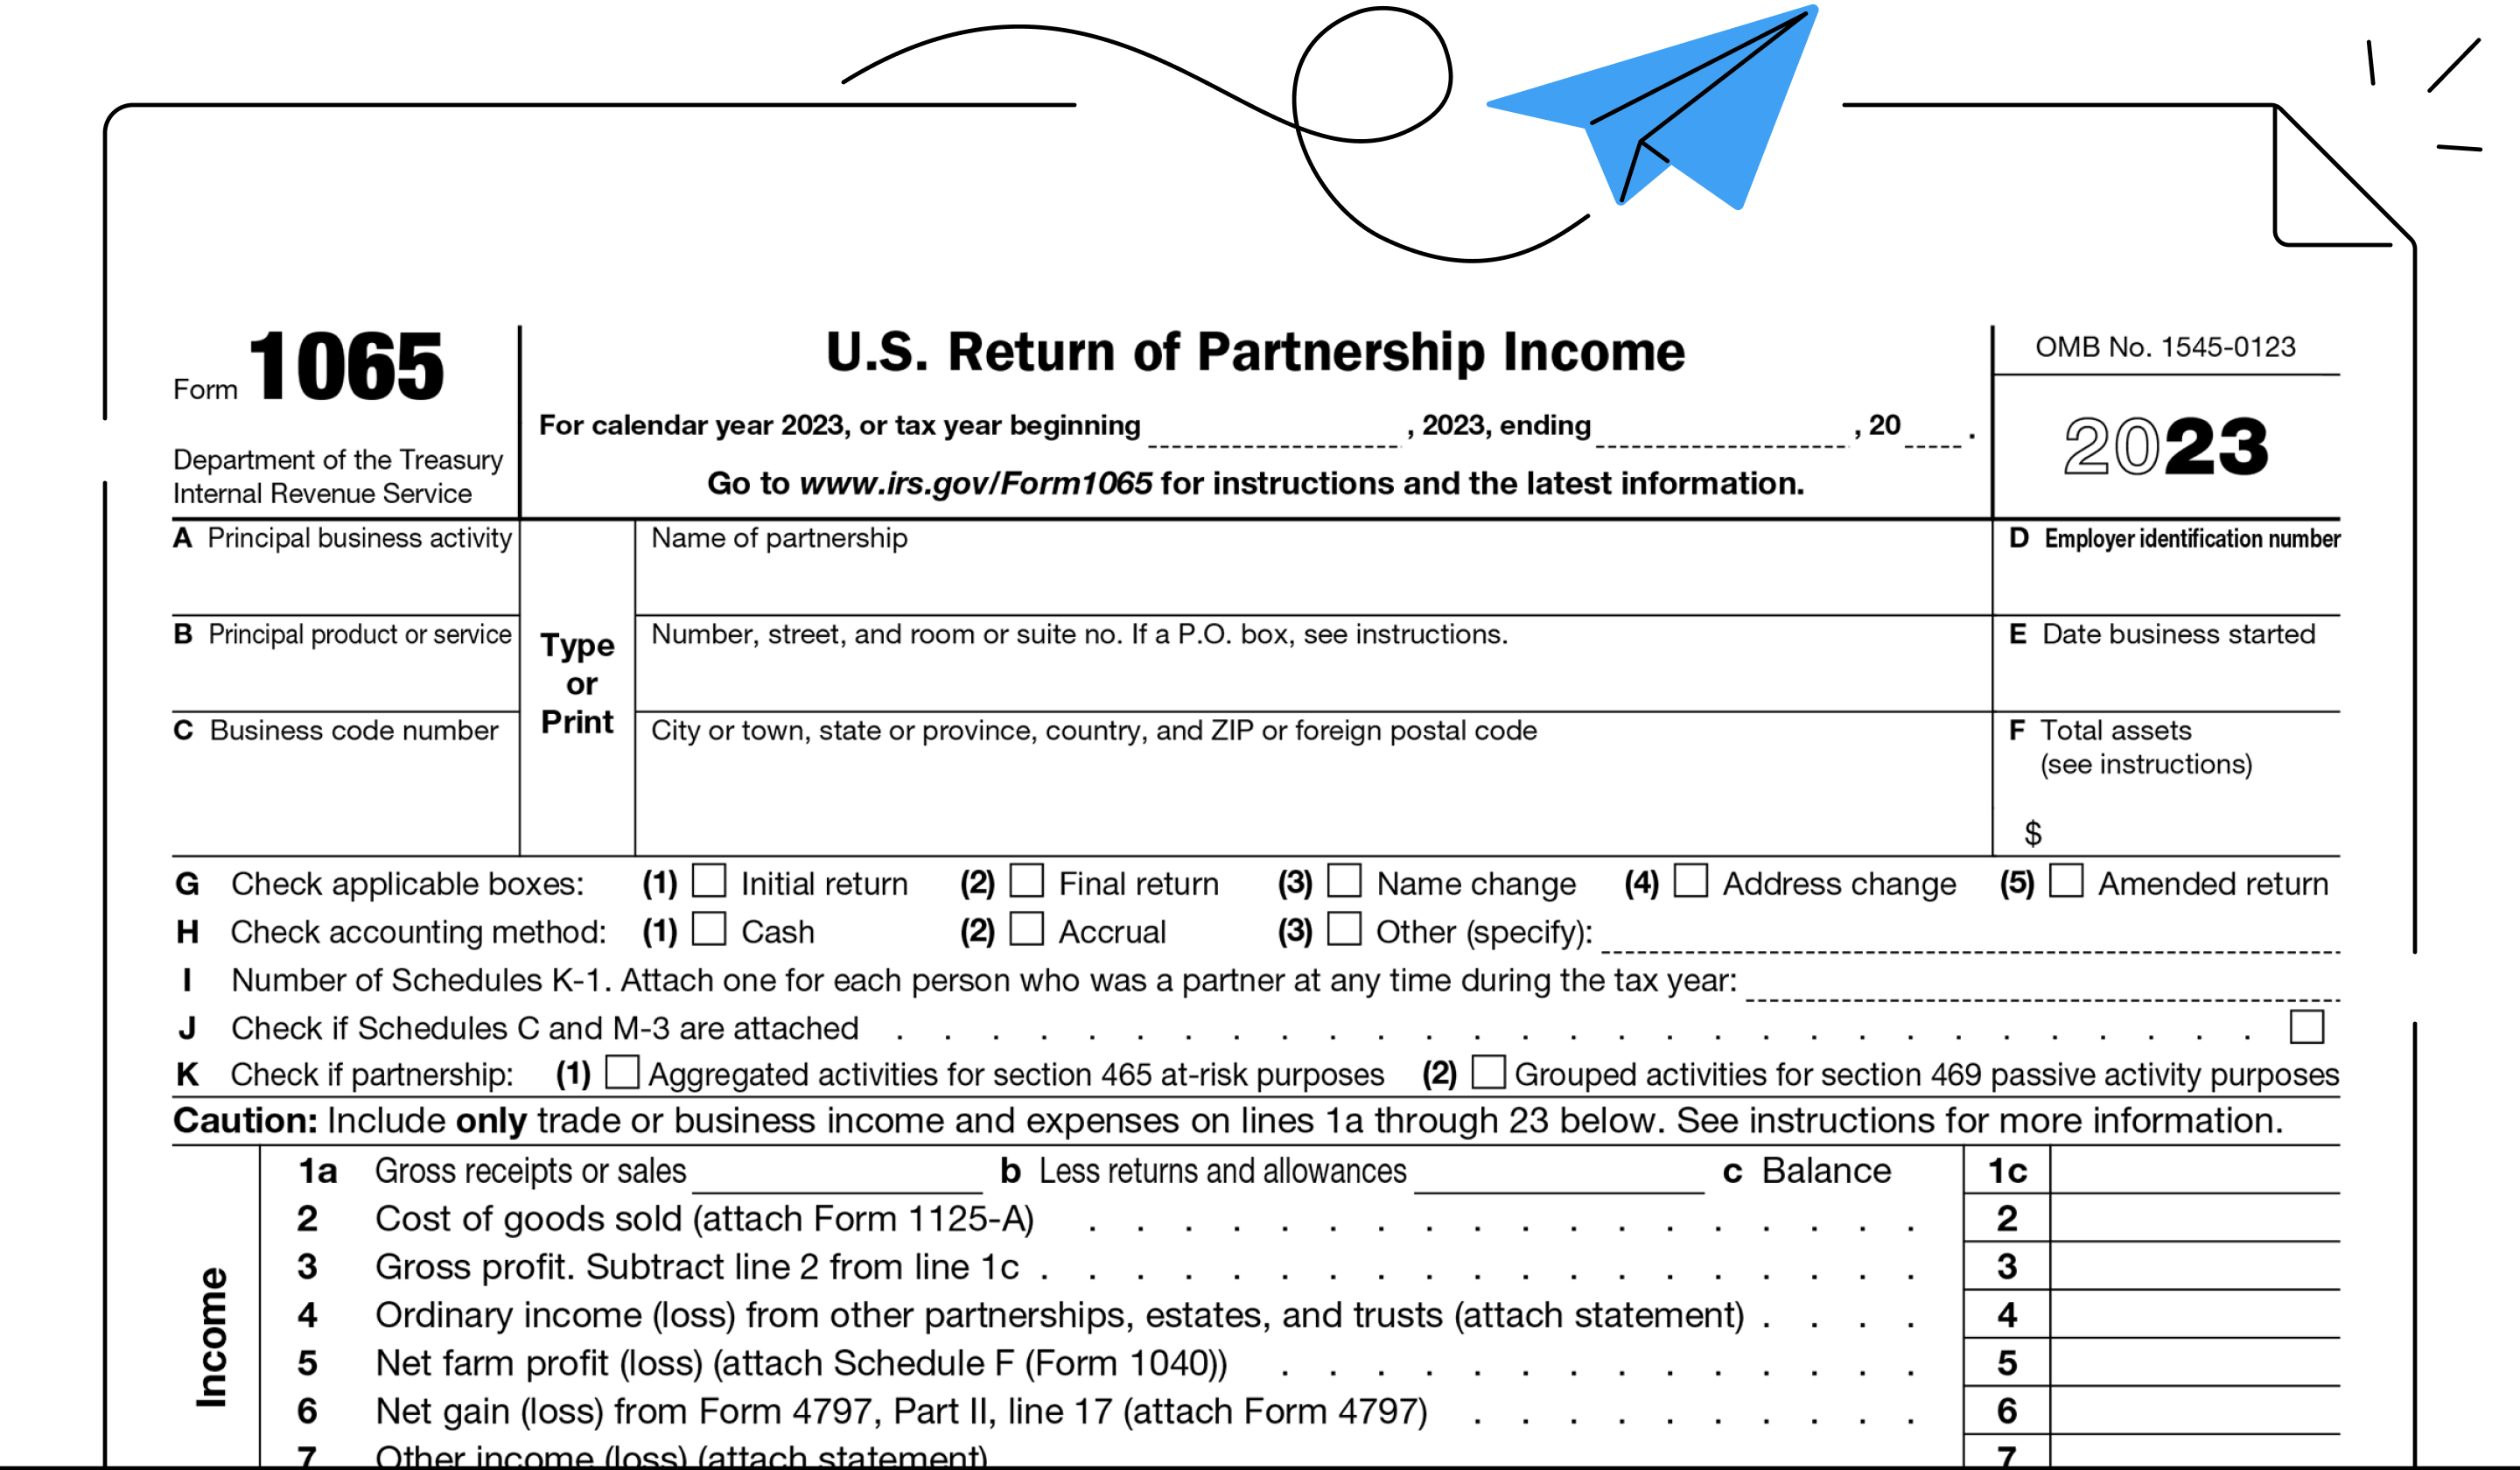
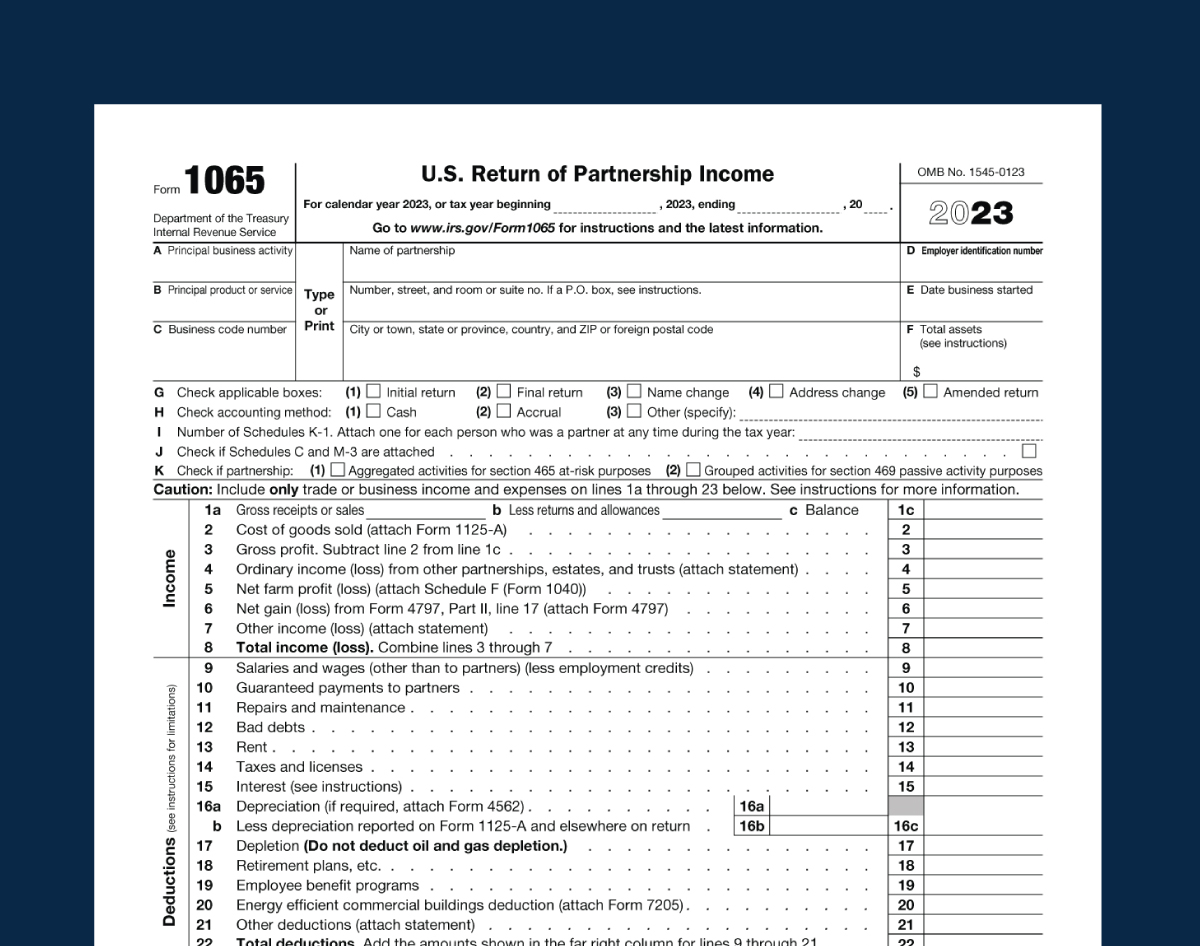
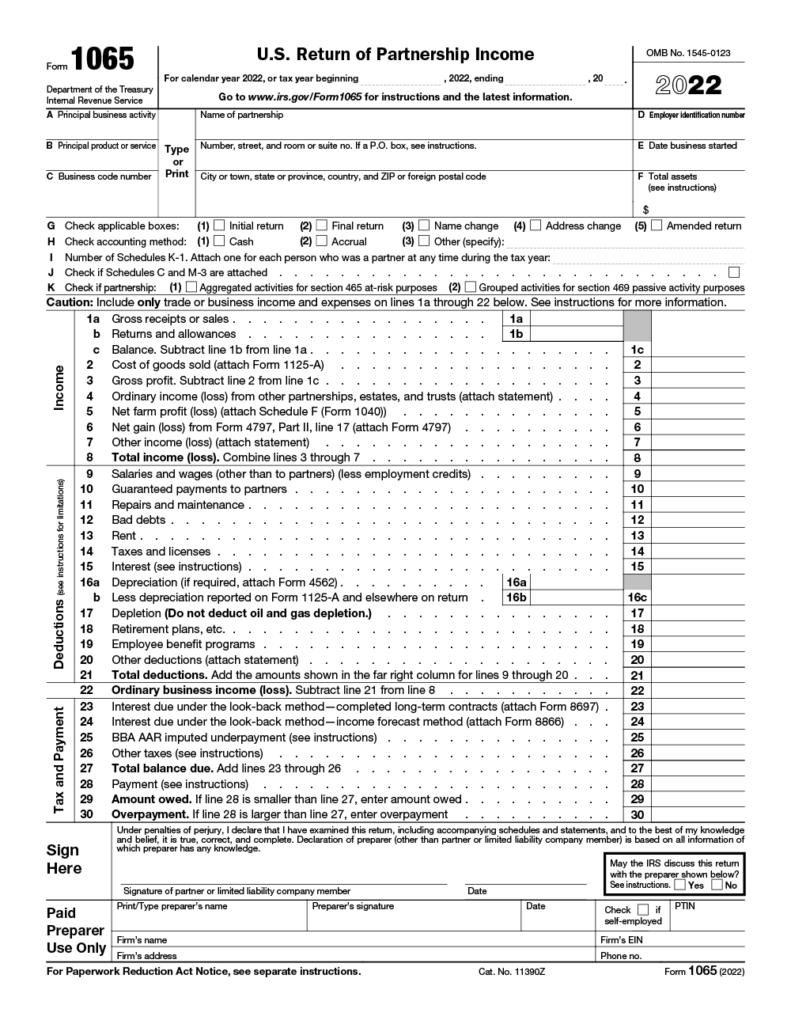
The actual filing form is IRS Form 1065, U.S. Return of Partnership Income. The partnership attaches schedules that break down every dollar — ordinary business income on Line 1, guaranteed payments on Line 4, rental real estate on Line 2, interest on Line 5, and so on. Each partner then receives a Schedule K-1 showing their share of every line item. The K-1 is where most people hit trouble because each box on that form carries different tax implications depending on the partner's situation. I filed my first batch of 1065s back when TurboTax Business was still new and the software had no concept of mixed-use property allocations. I learned quickly that the software won't save you from bad data entry. It will happily produce a PDF with garbage in it and mark it balanced.
How the allocation mechanism actually works
Partnerships allocate income according to the partnership agreement, but the agreement has to hold up under the substantial economic effect test in IRC Section 704(b). This means you can't just assign profits to whoever you feel like. The IRS requires that allocations have real economic meaning, not just tax-driven distortion. If you allocate all the losses to the passive investor while keeping all the income for the active operator, the IRS will recharacterize those allocations and you'll be filing amended returns for three years. Here's a specific edge case I ran into last year that took about six hours to resolve. A client had a multi-member LLC that elected partnership taxation and brought in a new member mid-year through a Section 754 election. The problem was that the existing partners had built-up inside basis differences from prior asset appreciation, and the new member's outside basis didn't reflect those differences. Without the 754 election properly coordinated, the partnership couldn't allocate depreciation correctly between old and new members. The workaround was to file Form 8594 alongside the 1065 and attach a separate computation sheet showing the basis adjustment under Section 743(b), then ensure each K-1 reflected the adjusted depreciation deduction. Most preparers completely miss this and end up with partners reporting wrong basis on their individual returns, which creates a cascade of errors when they eventually sell their interest.
Common pitfalls that cost people money
The biggest trap is the deadline. A standard 1065 is due March 15, not April 15. That's six weeks earlier than individual returns. If you need more time, you file Form 7004 for an automatic six-month extension, pushing the deadline to September 15. But here's the catch that catches everyone off guard: the K-1 deadlines are locked to the original filing date or the extended date, and partners cannot finalize their individual returns until they receive their K-1s. If you're waiting on a K-1 to file your 1040, an extension on the 1065 directly delays your personal tax filing. I've seen clients miss this connection and get stuck in a two-month limbo because the partnership didn't plan ahead. Another counter-intuitive issue: guaranteed payments. These are treated as ordinary income to the recipient partner but are deductible by the partnership on Line 40 of Form 1065. Many partnership owners treat them like owner draws or distributions, which is wrong. Guaranteed payments must be fixed amounts determined without regard to partnership income. If the payment amount fluctuates with profits, the IRS may reclassify it as a distribution, which changes the tax treatment entirely. I had a client who was paying his silent partner a percentage of net profits and calling it a guaranteed payment. We had to restructure that as a proper profit-sharing distribution and amend the prior year's K-1s.
Get the Full Details
When a 1065 isn't the right choice
S-L corporations exist for a reason and sometimes serve the same business structure better. If you're running a single-member LLC, you don't need a 1065 at all — you file Schedule C with your 1040. Multi-member LLCs can choose between partnership taxation and S-corp election. The tradeoff is straightforward: partnerships avoid self-employment tax on distributed profits, while S-corps require reasonable compensation rules and have stricter ownership restrictions. For a typical small business with one or two active owners pulling significant income, the S-corp path often saves money on self-employment tax after accounting for the additional compliance costs. For investment holdings or businesses with passive capital contributors, the 1065 structure is usually cleaner. The 1065 also breaks down if you're dealing with foreign partners. Partnerships with foreign partners must withhold tax on effectively connected income under Section 1446, which adds a whole separate compliance layer. The withholding rate is currently 31% for most situations, and failure to remit on time triggers penalties that compound quickly. I once worked with a firm that forgot about the 1446 requirement for their Chinese-member LLC and ended up owing back taxes plus penalties that exceeded the original tax liability by about forty percent. The lesson was expensive but clear: foreign ownership changes everything about how you handle a 1065. If your partnership has more than fifty members, you should strongly consider whether the administrative burden is worth it. Filing 1065s with complex allocations across many partners becomes increasingly error-prone as the member count grows. Some larger entities switch to corporate taxation or restructure into holding companies just to simplify the annual filing cycle. There's no rule against it. The IRS doesn't care about convenience.
Practical steps for getting it done right
Start with a clean trial balance before you open the tax software. I mean a real general ledger, not just the year-end profit number. You need every revenue account, every expense category, every balance sheet adjustment mapped out. The 1065 asks for line-by-line detail that your chart of accounts probably doesn't capture in the right buckets. I set up a mapping spreadsheet that translates my client's accounting software categories into the exact 1065 line items. It takes about twenty minutes per quarter but saves roughly three hours at filing time when you're trying to figure out why Schedule K has four different rental income lines that don't match the books. Pay attention to the state filing requirements too. Some states require a separate partnership return even if the federal form is handled. California, for example, imposes a $800 annual franchise tax on LLCs taxed as partnerships regardless of income level. Texas has its own margins tax that applies separately. New York requires a separate IT-204 form. These are easy to overlook if you're only focused on the federal filing, and the penalties for missing a state partnership return can be steeper than the federal ones. Keep documentation for every allocation decision. The partnership agreement should specify how profits and losses are divided, and you need a written record of any mid-year changes. If the IRS audits your allocation method, they'll ask for the agreement and evidence that the allocations match the economic arrangement. Verbal agreements don't hold up in an audit. I keep a dedicated folder for each partnership that contains the operating agreement, all amendment documents, meeting minutes where allocation changes were discussed, and the basis computation worksheets for each partner. This folder has saved clients multiple times during IRS correspondence.