The Practical Breakdown You Actually Need
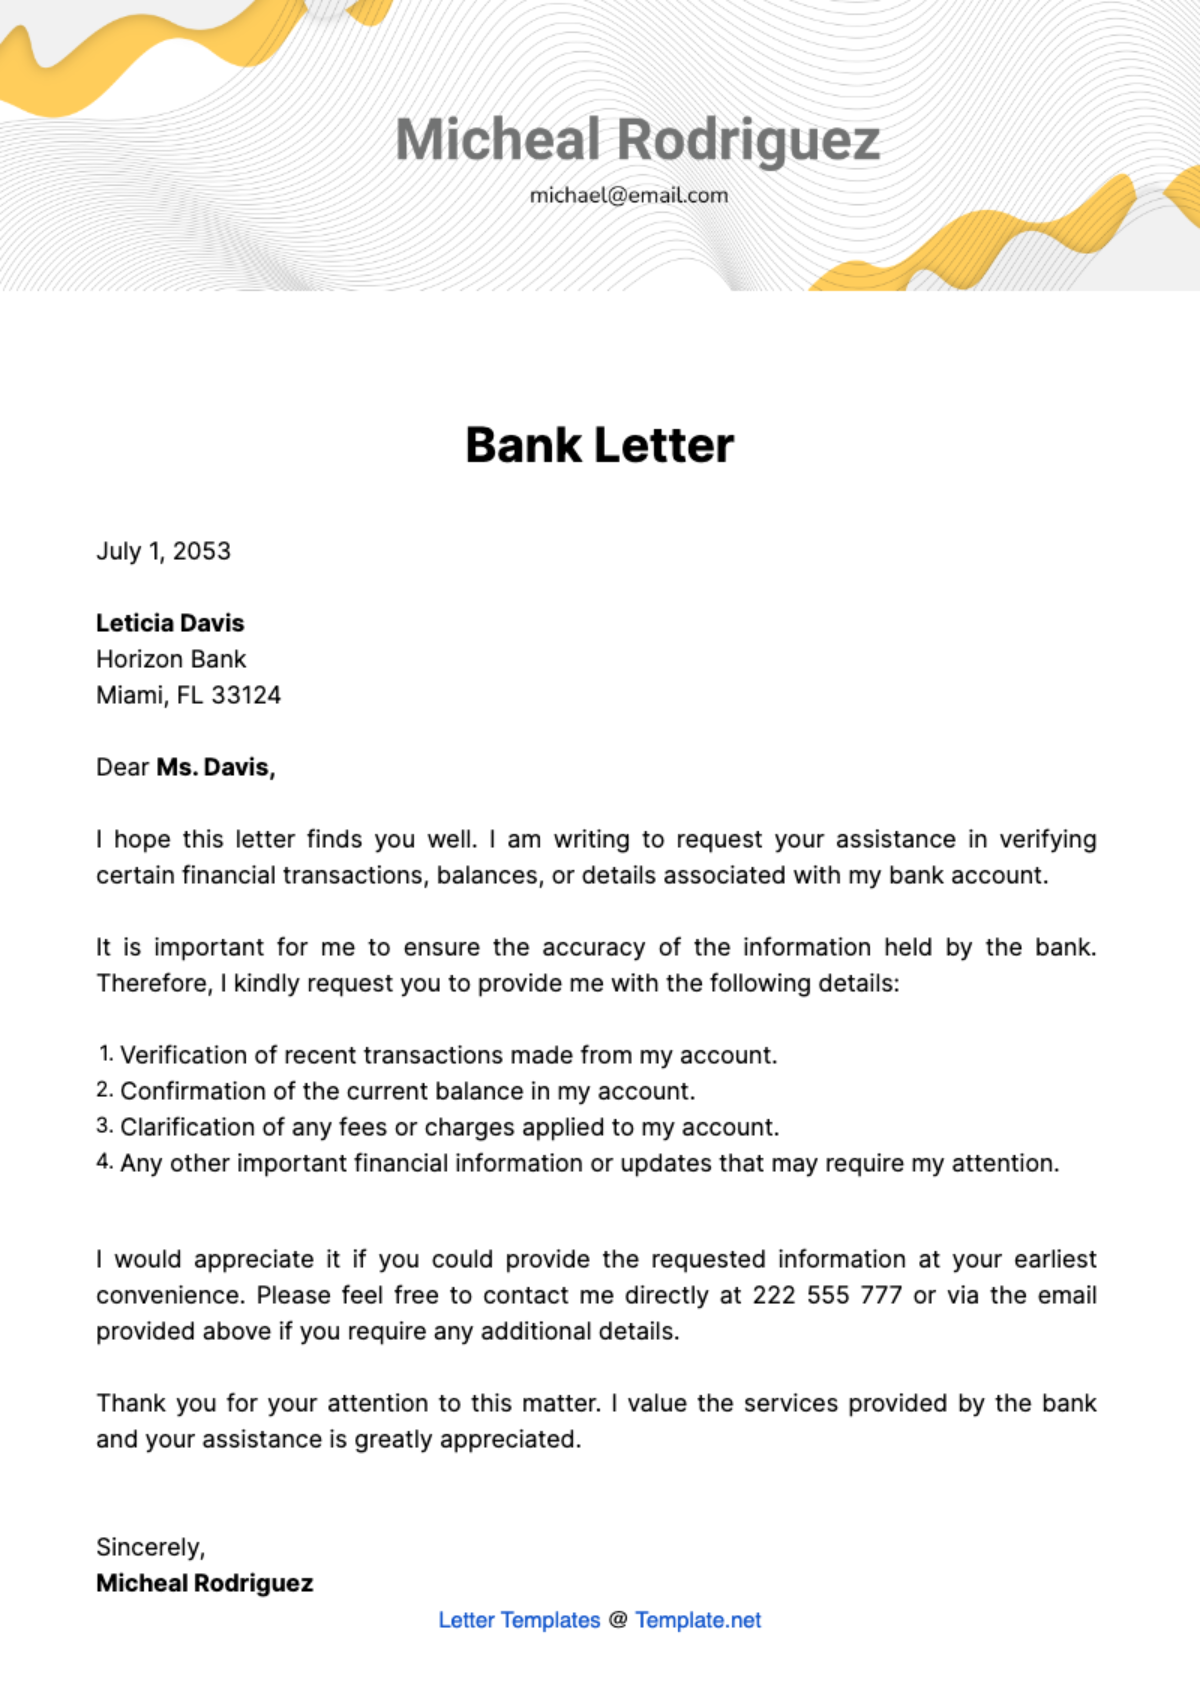
A bank letter is a formal document issued by a financial institution that confirms the existence, status, or details of a banking relationship. That's the simple version. The real version depends entirely on which type you're dealing with, and they all look different on the surface but serve very different purposes. There's a certificate of deposit letter, a balance confirmation letter, a good standing letter, a closure letter, and sometimes a verification letter for employment or visa purposes. Each one carries different weight depending on who's asking for it. I spent years dealing with these during loan processing, and the biggest issue I saw wasn't the letters themselves but the confusion around what each one actually proves. A balance confirmation letter doesn't mean you're creditworthy. A good standing letter doesn't guarantee you can borrow money. People mix these up constantly, and then they get confused when the other party rejects the document or asks for something more specific.
What Is A Bank Letter and Why Does the Type Matter
The term "bank letter" covers several distinct documents, and knowing which one you need before you request it saves you from going back and forth with both the bank and the requesting party. Most people just ask for "a bank letter" and end up with something that's technically accurate but useless for the purpose at hand. The requesting party usually has a specific requirement in mind. A landlord wants to know your account has sufficient funds. A visa officer wants proof of financial stability over time. A mortgage lender wants a certified balance statement with recent transaction history. These aren't interchangeable. The most common pitfall I ran into was people bringing a generic account confirmation to a situation that required a certified letter with a wet signature. Banks will print whatever you ask for on standard letterhead, but not every document they produce carries the same level of authentication. Some require a branch stamp. Some need a specific officer's signature. Some can only be issued at the home branch where the account was opened. Knowing this beforehand prevents a wasted trip.
How to Get One Without Losing Half a Day
The process varies significantly depending on whether you have online banking access and what type of letter you need. For basic balance confirmation or account status letters, most major banks let you generate and download these through their internet banking portal in under five minutes. The document usually comes as a PDF with a digital seal or QR code that the receiving party can verify. This covers maybe sixty to seventy percent of routine requests. Rental applications, basic employment verification, and general financial proof typically fall into this category. For anything requiring certification, physical signature, or official bank stamp, you'll usually need to visit a branch. Bring your account number, a valid government ID, and a clear description of what the letter needs to include. If you don't specify the exact purpose, they'll default to the most basic version, which is rarely what you actually need. I learned this the hard way during a commercial lease negotiation where the landlord rejected my first letter because it lacked a statement about the account being in good standing for the past twenty-four months. I had to go back to the branch, fill out a separate request form, and wait an additional forty-five minutes. Total time spent: about two hours round trip. Getting it right the first time cuts that down to roughly twenty minutes if you visit a branch, or three minutes if you use the online portal. Some banks also offer expedited services for urgent requests. These typically cost between ten and thirty dollars and can deliver a certified letter within twenty-four hours through courier. Not worth it for routine matters, but useful when a closing date is approaching and the title company needs something yesterday.
Get the Full Details
Common Mistakes and What They Cost You
One issue that comes up repeatedly is date sensitivity. Bank letters have an effective date, and many institutions consider them valid for only thirty to ninety days depending on the purpose. A letter issued four months ago means nothing to a mortgage underwriter. They'll ask for a fresh one. This is especially relevant for people who generate these letters proactively and then sit on them hoping to use them later. Don't. Generate it when you're ready to submit, or within a week of submission at most. Another problem is mismatched name formatting. If your bank account is under "Robert James Smith" but your ID or application uses "Bob Smith," some receiving parties will flag the discrepancy. It's not always a dealbreaker, but it creates delays while they sort out identity verification. Make sure the name on the letter matches exactly what the requesting party expects to see. If there's a legitimate difference, ask your bank if they can add a notation linking the two identities. There's also the question of language. If you're dealing with an international request, most banks will only issue letters in the primary language of the country where the branch operates. A branch in Mexico might only produce Spanish letters. A branch in Germany might only produce German. If you need a letter in English for an overseas purpose, request it specifically at the time of issuance. Some branches charge extra for multilingual letters or may refuse entirely if they lack the template. This is a real bottleneck for expats and international business owners.
When a Bank Letter Won't Work
Not every situation requires or accepts a bank letter. Some organizations prefer direct bank-to-bank verification through established channels like standard verification services or secure email protocols. In those cases, a letter you hand-carry is actually less trustworthy because anyone could forge the paper. The requesting party would rather communicate directly with your bank through verified systems. Know which path your situation requires before you invest time in obtaining a physical document. There are also cases where a bank letter alone is insufficient. A poor balance doesn't disappear because the letter is properly formatted. Negative markings, overdraft history, or recent large withdrawals can undermine the impression you're trying to create. Banks won't omit negative information from official letters. If your financial picture is shaky, no amount of document formatting will fix that, and you'd be better off addressing the underlying issue before making any requests.
Where to Access These Documents
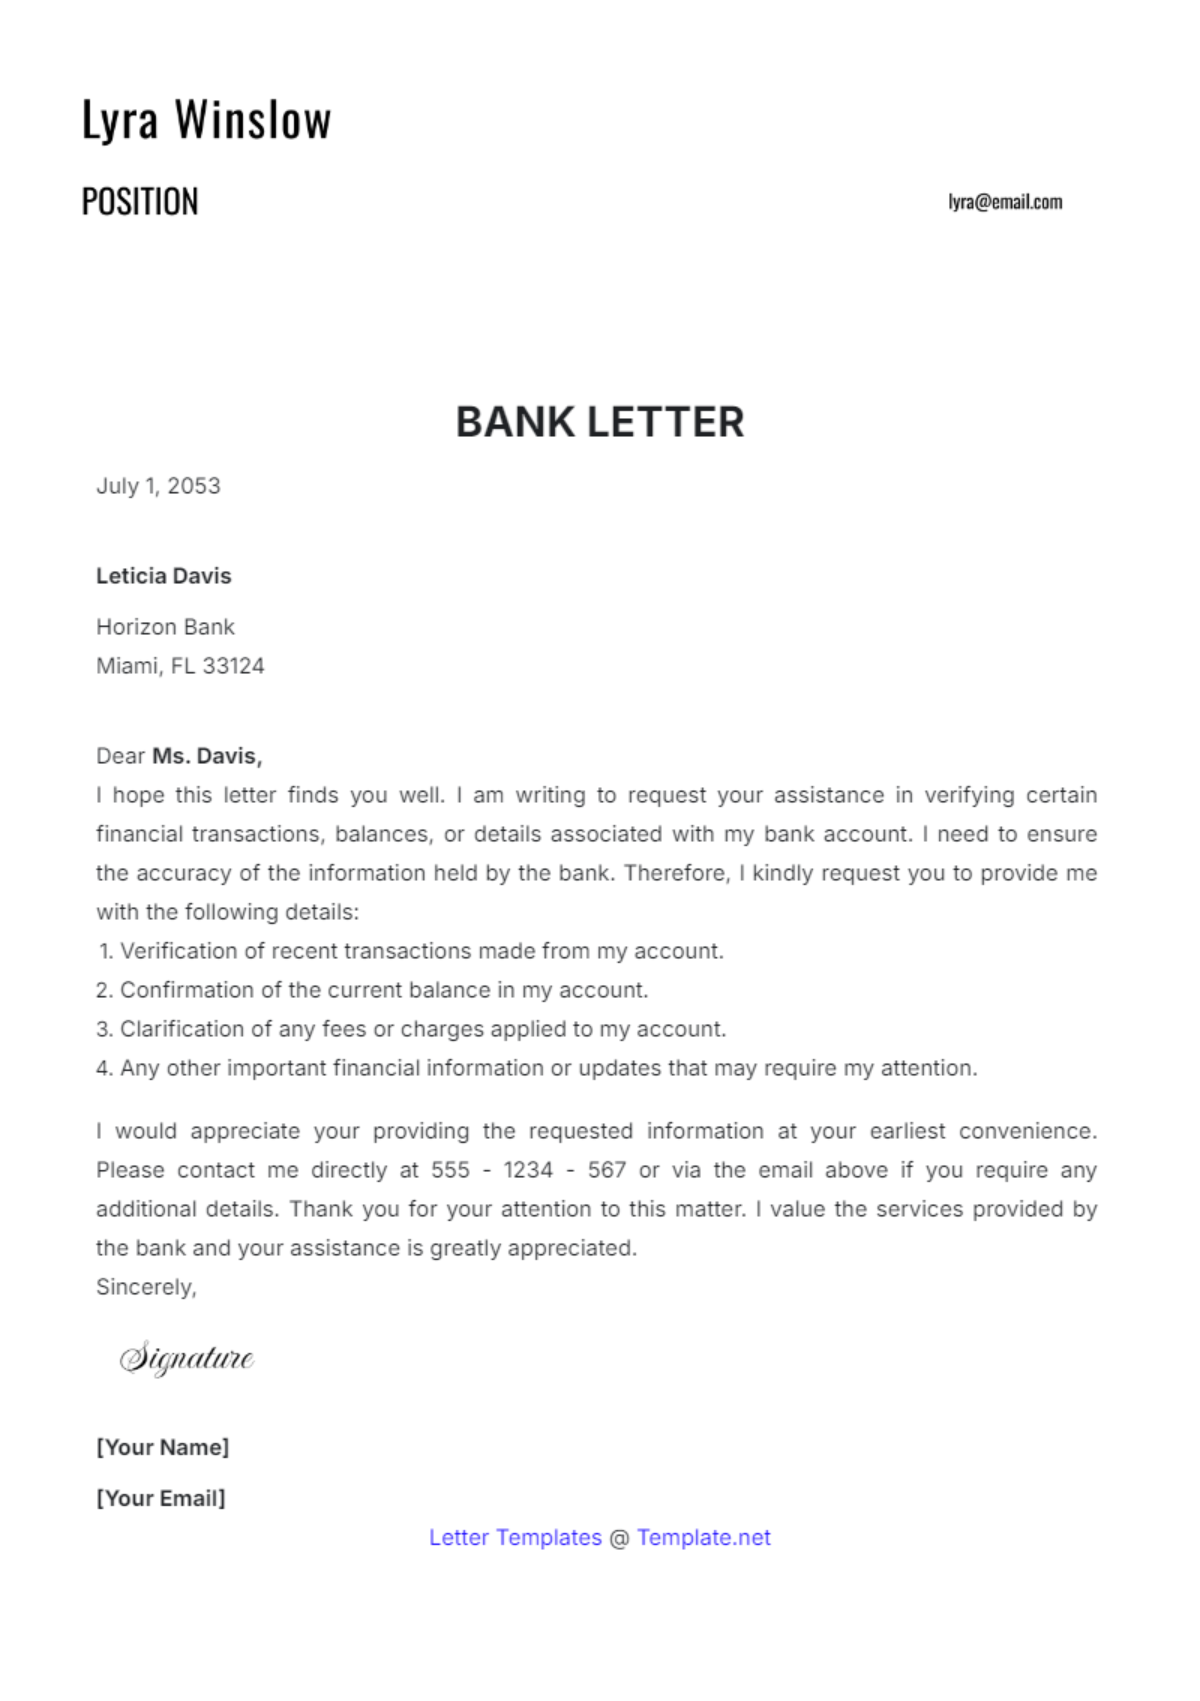
Most major banks provide bank letters through their online banking platforms under sections labeled "Statements," "Certifications," "Document Requests," or "Bank References." Look for terms like "Account Verification," "Balance Certificate," or "Letter of Good Standing." If you can't find it, calling customer service or visiting your home branch with a written request is the fallback. Keep in mind that smaller credit unions and regional banks may have slower turnaround times, sometimes two to five business days for certified letters, compared to same-day or instant issuance at larger national institutions. If you need to download a sample template to understand what to expect, your bank's website often has example documents in their help or FAQ sections. These show you the format, language, and certification markers so you know what you're receiving before it arrives. Reviewing a sample takes about two minutes and prevents a lot of confusion later.