Bridge Loans in Practice
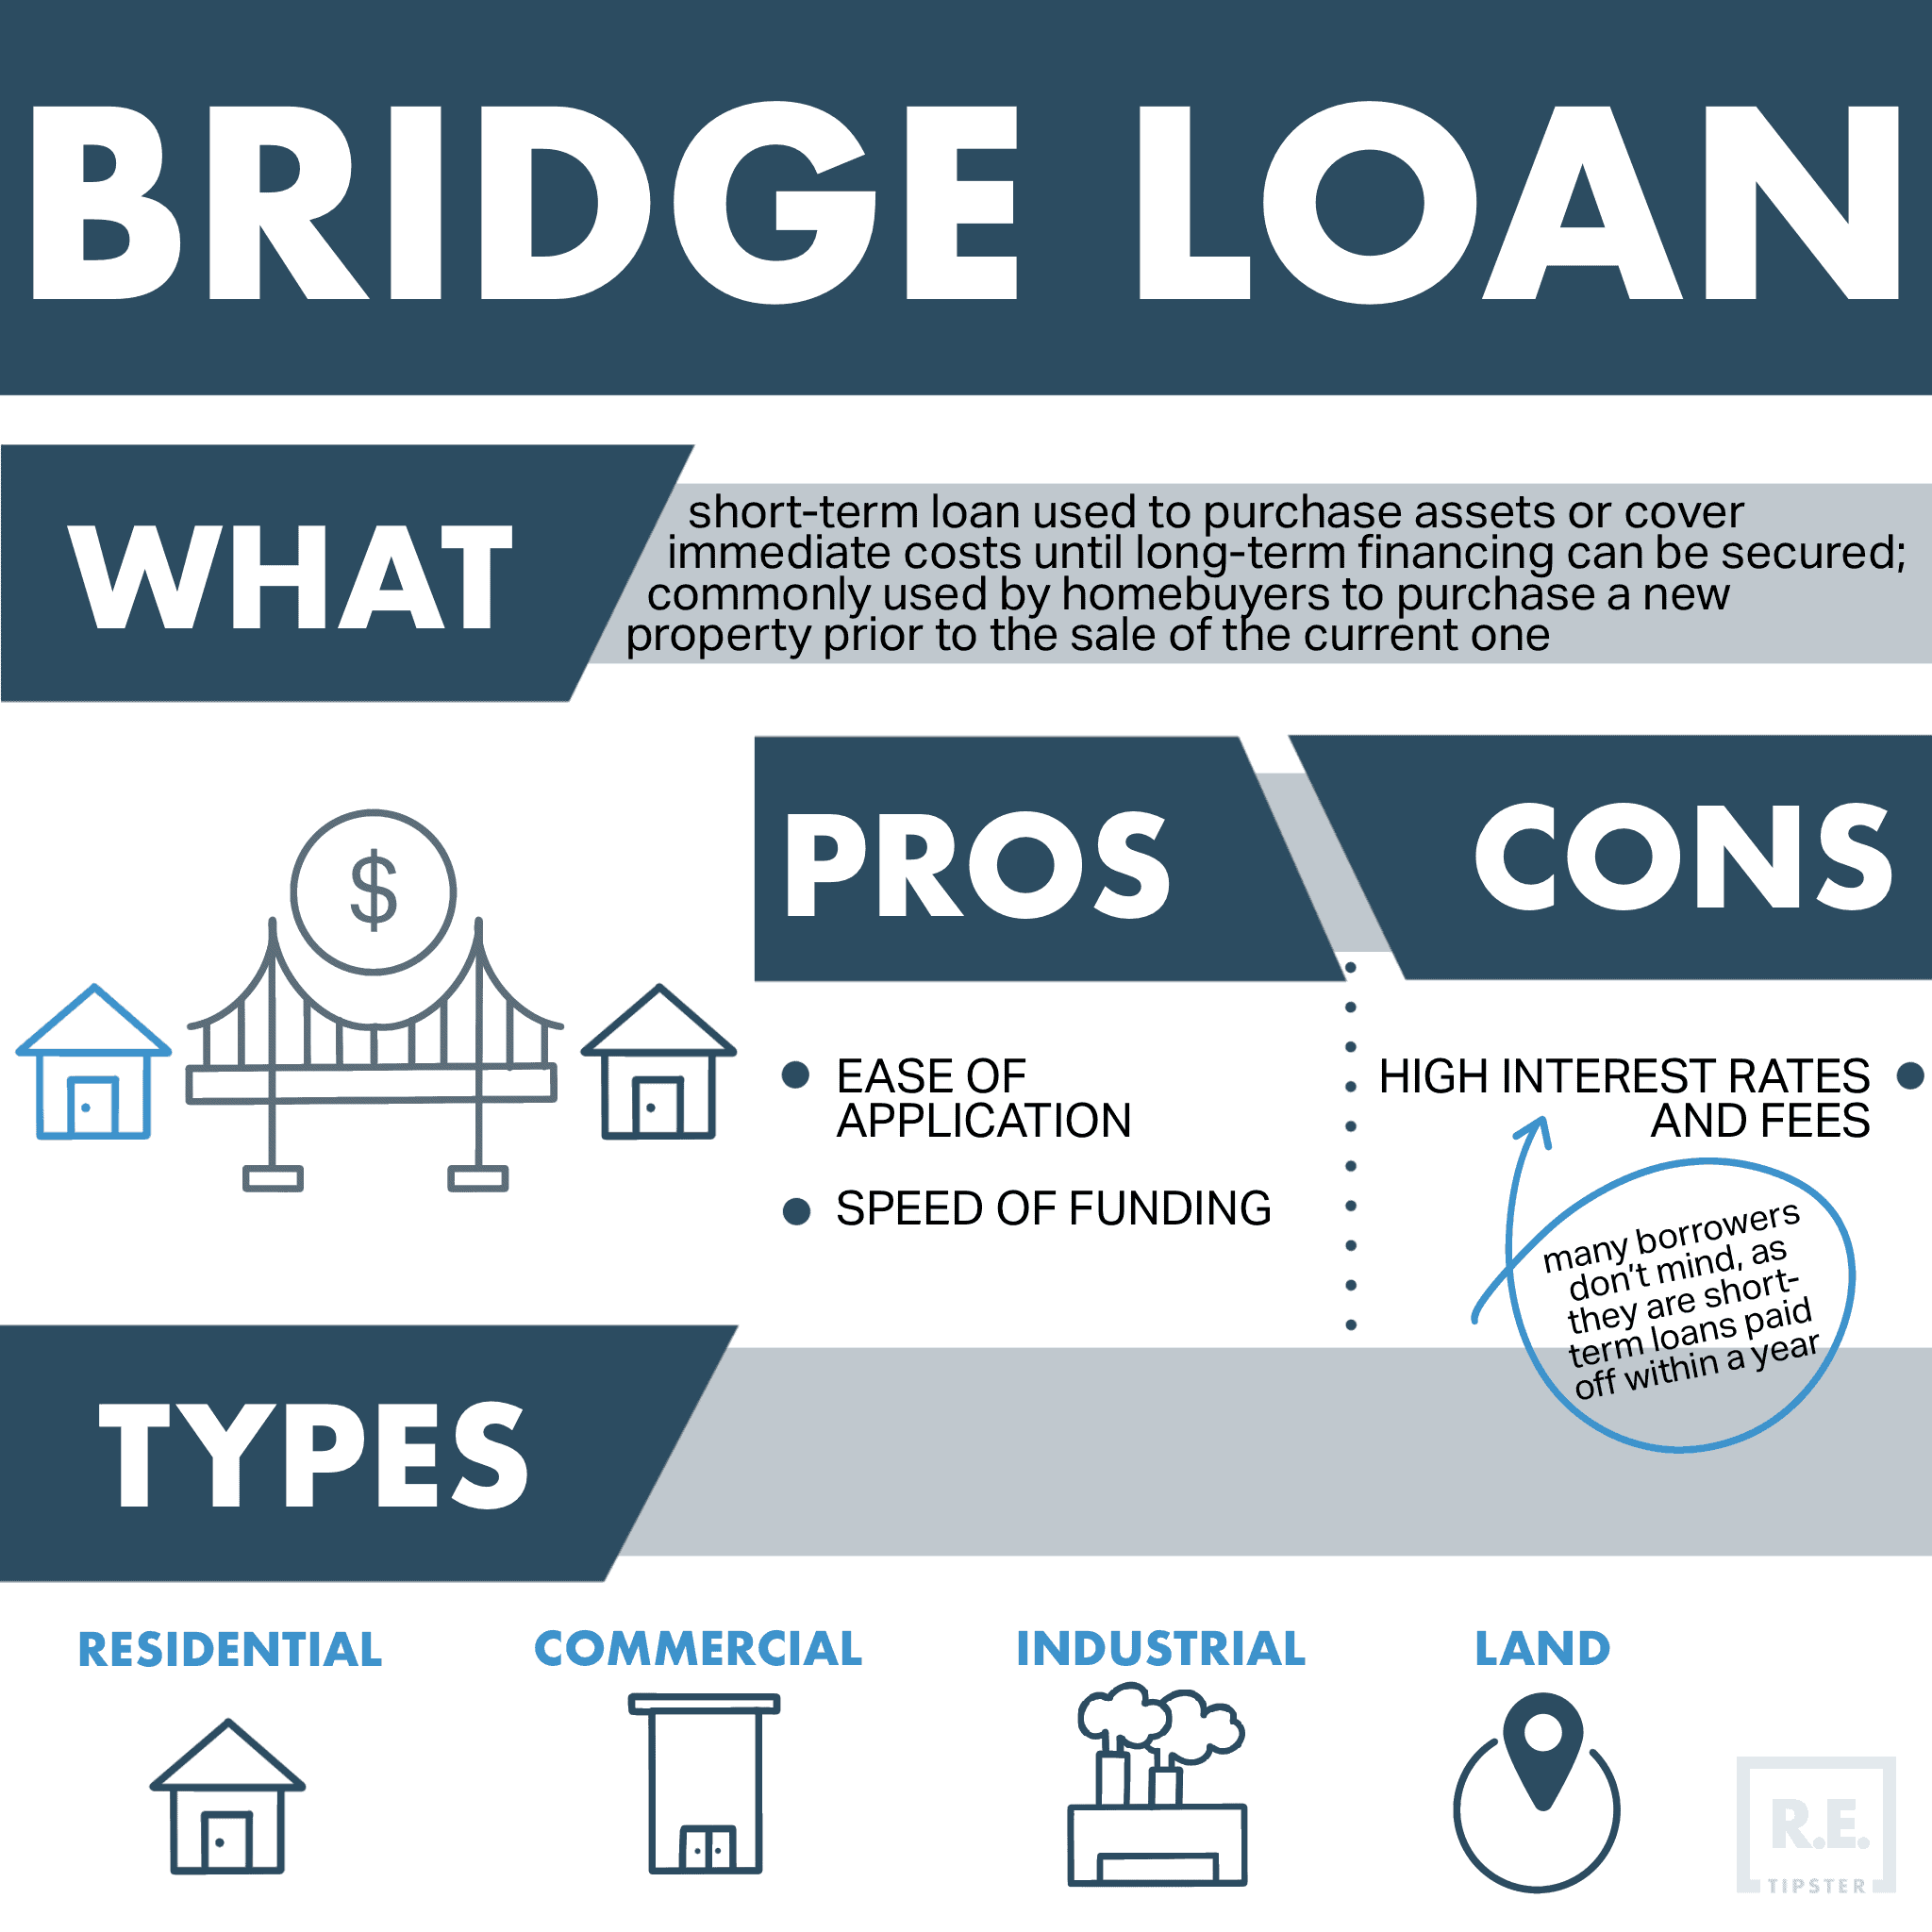
Most people hear about bridge loans when they're already behind on a decision. You've found the house you want, but the one you're in hasn't sold yet. The seller won't wait. Your lender won't extend your current mortgage. That gap is where a bridge loan lives, and it exists purely to convert an asset you control into cash you can deploy immediately while you wait for something else to close. A bridge loan is a short-term financing instrument secured by collateral, typically real estate, that provides immediate capital with the expectation that it will be repaid once a separate, anticipated transaction completes. The standard term runs from 6 to 12 months. Interest rates sit anywhere from 8% to 15% depending on credit profile, loan-to-value ratio, and whether the loan is structured on a recourse or non-recourse basis. You'll also encounter setup fees, appraisal costs, and sometimes mandatory prepayment penalties if you close early. The monthly carry cost on a $200,000 bridge loan at 10% interest alone runs roughly $1,667 before you factor in any points or origination charges.
What Is A Bridge Loan and How Does It Actually Work?
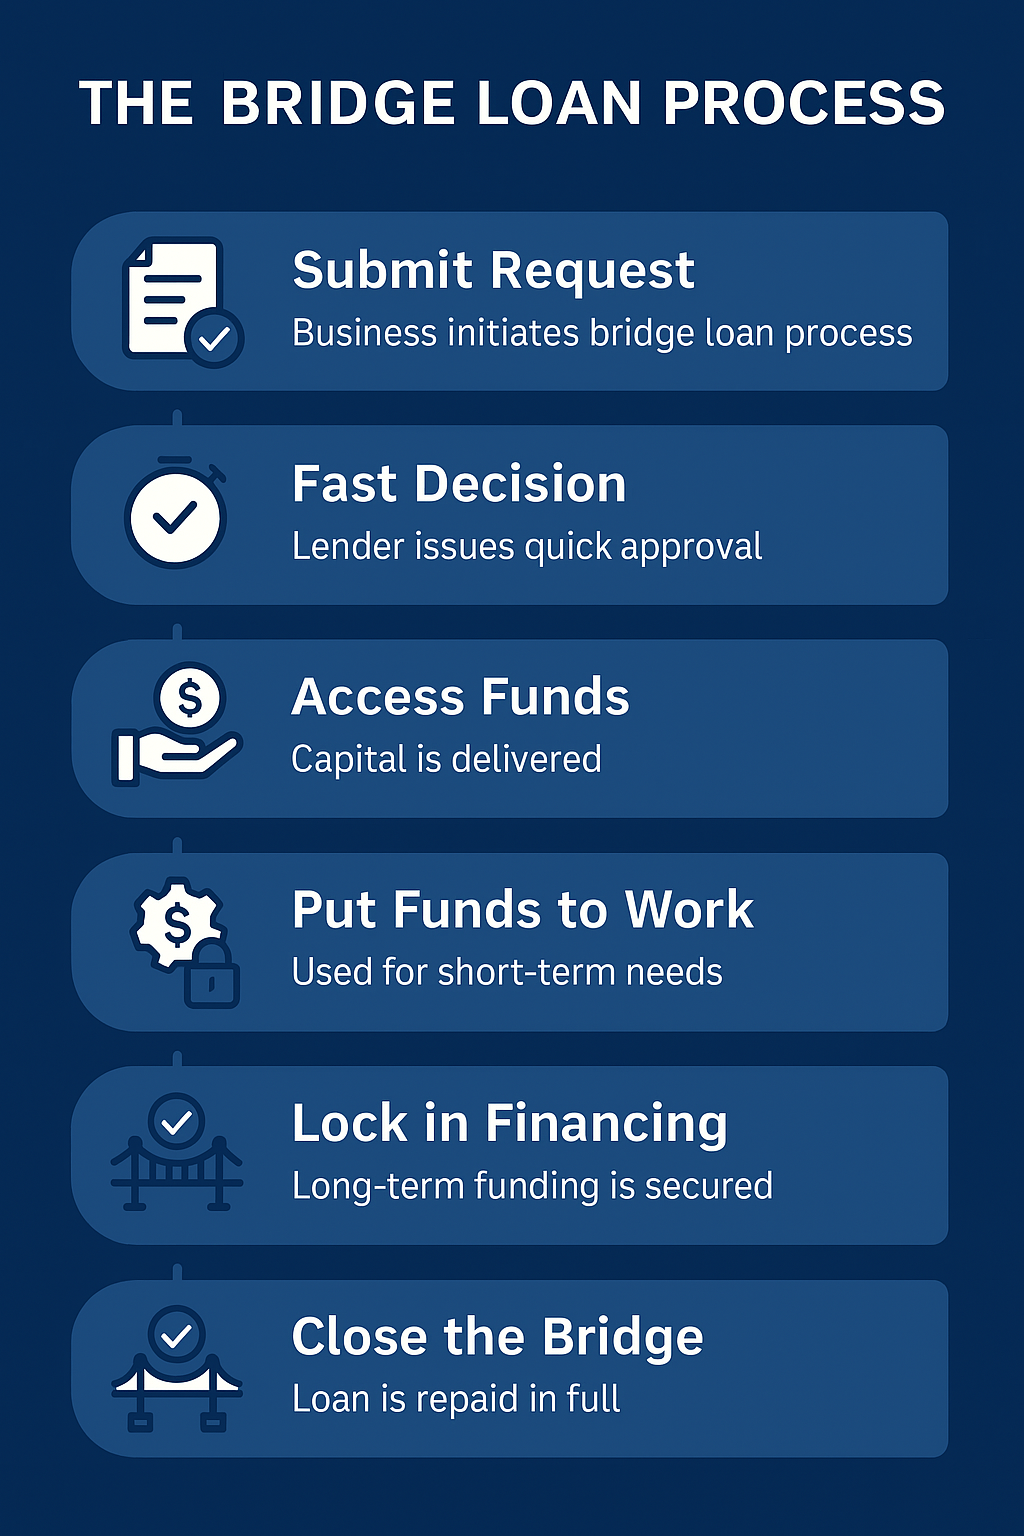
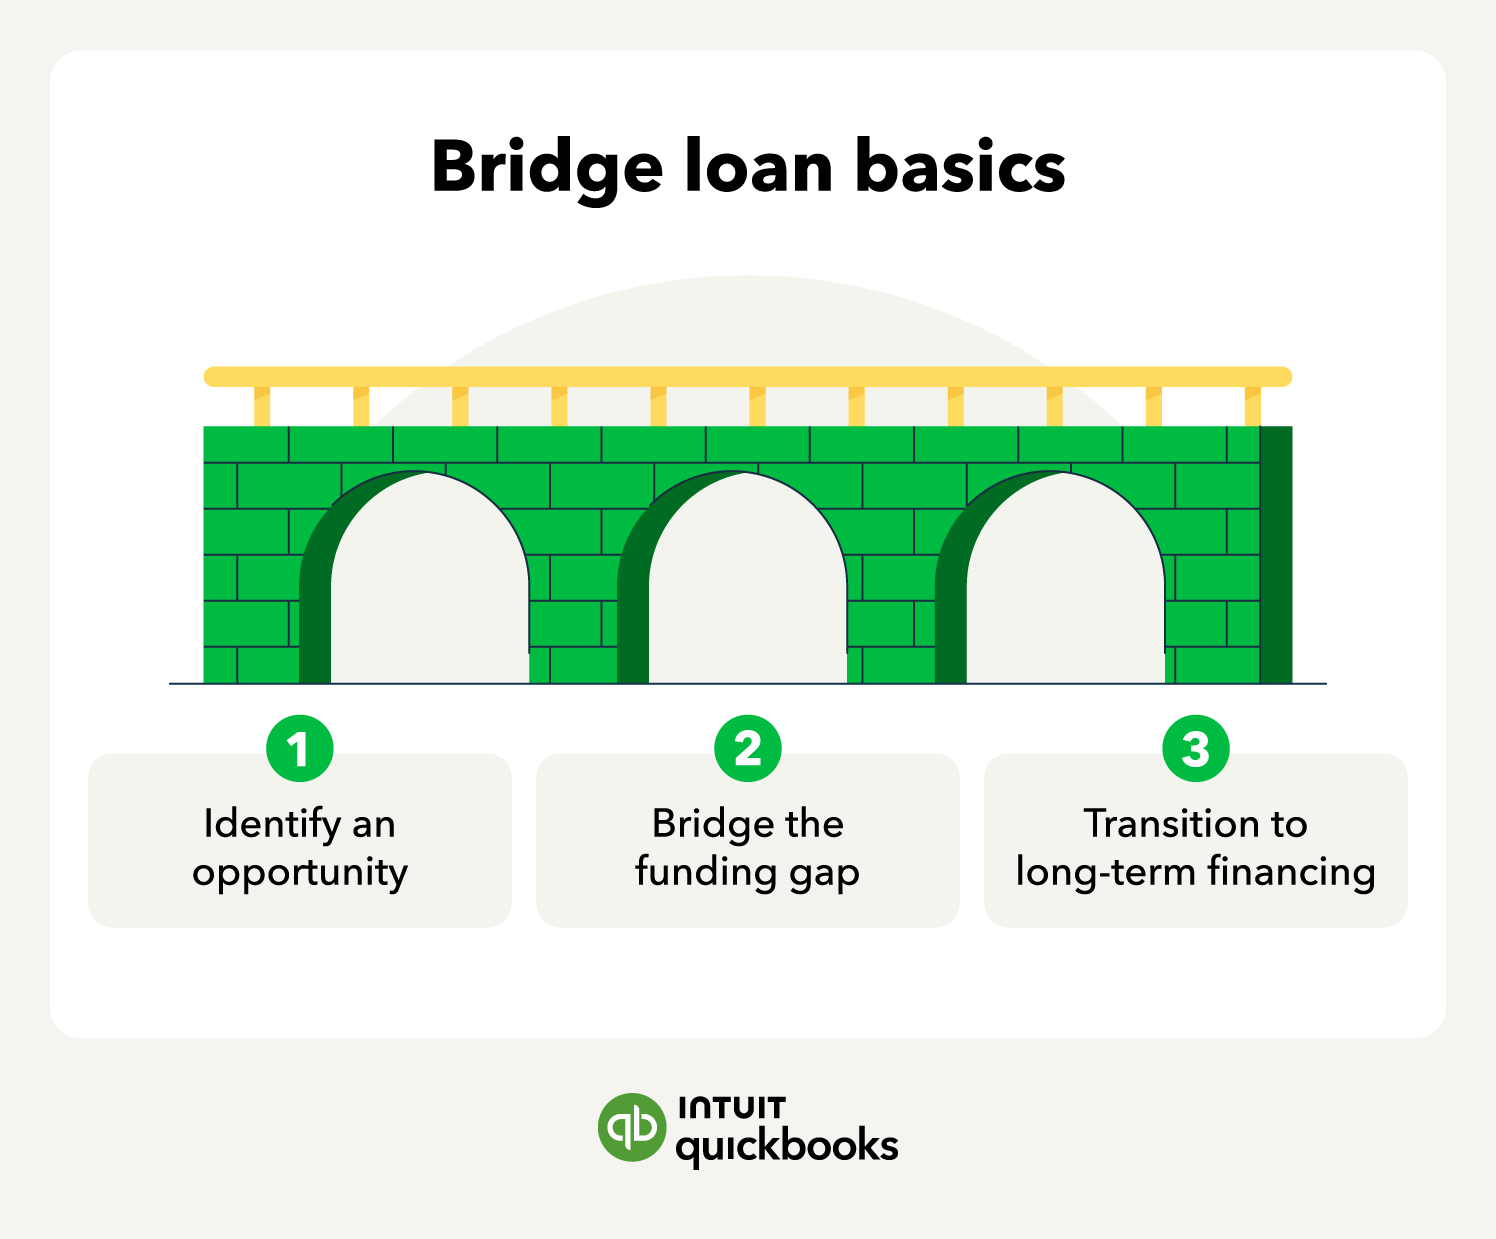
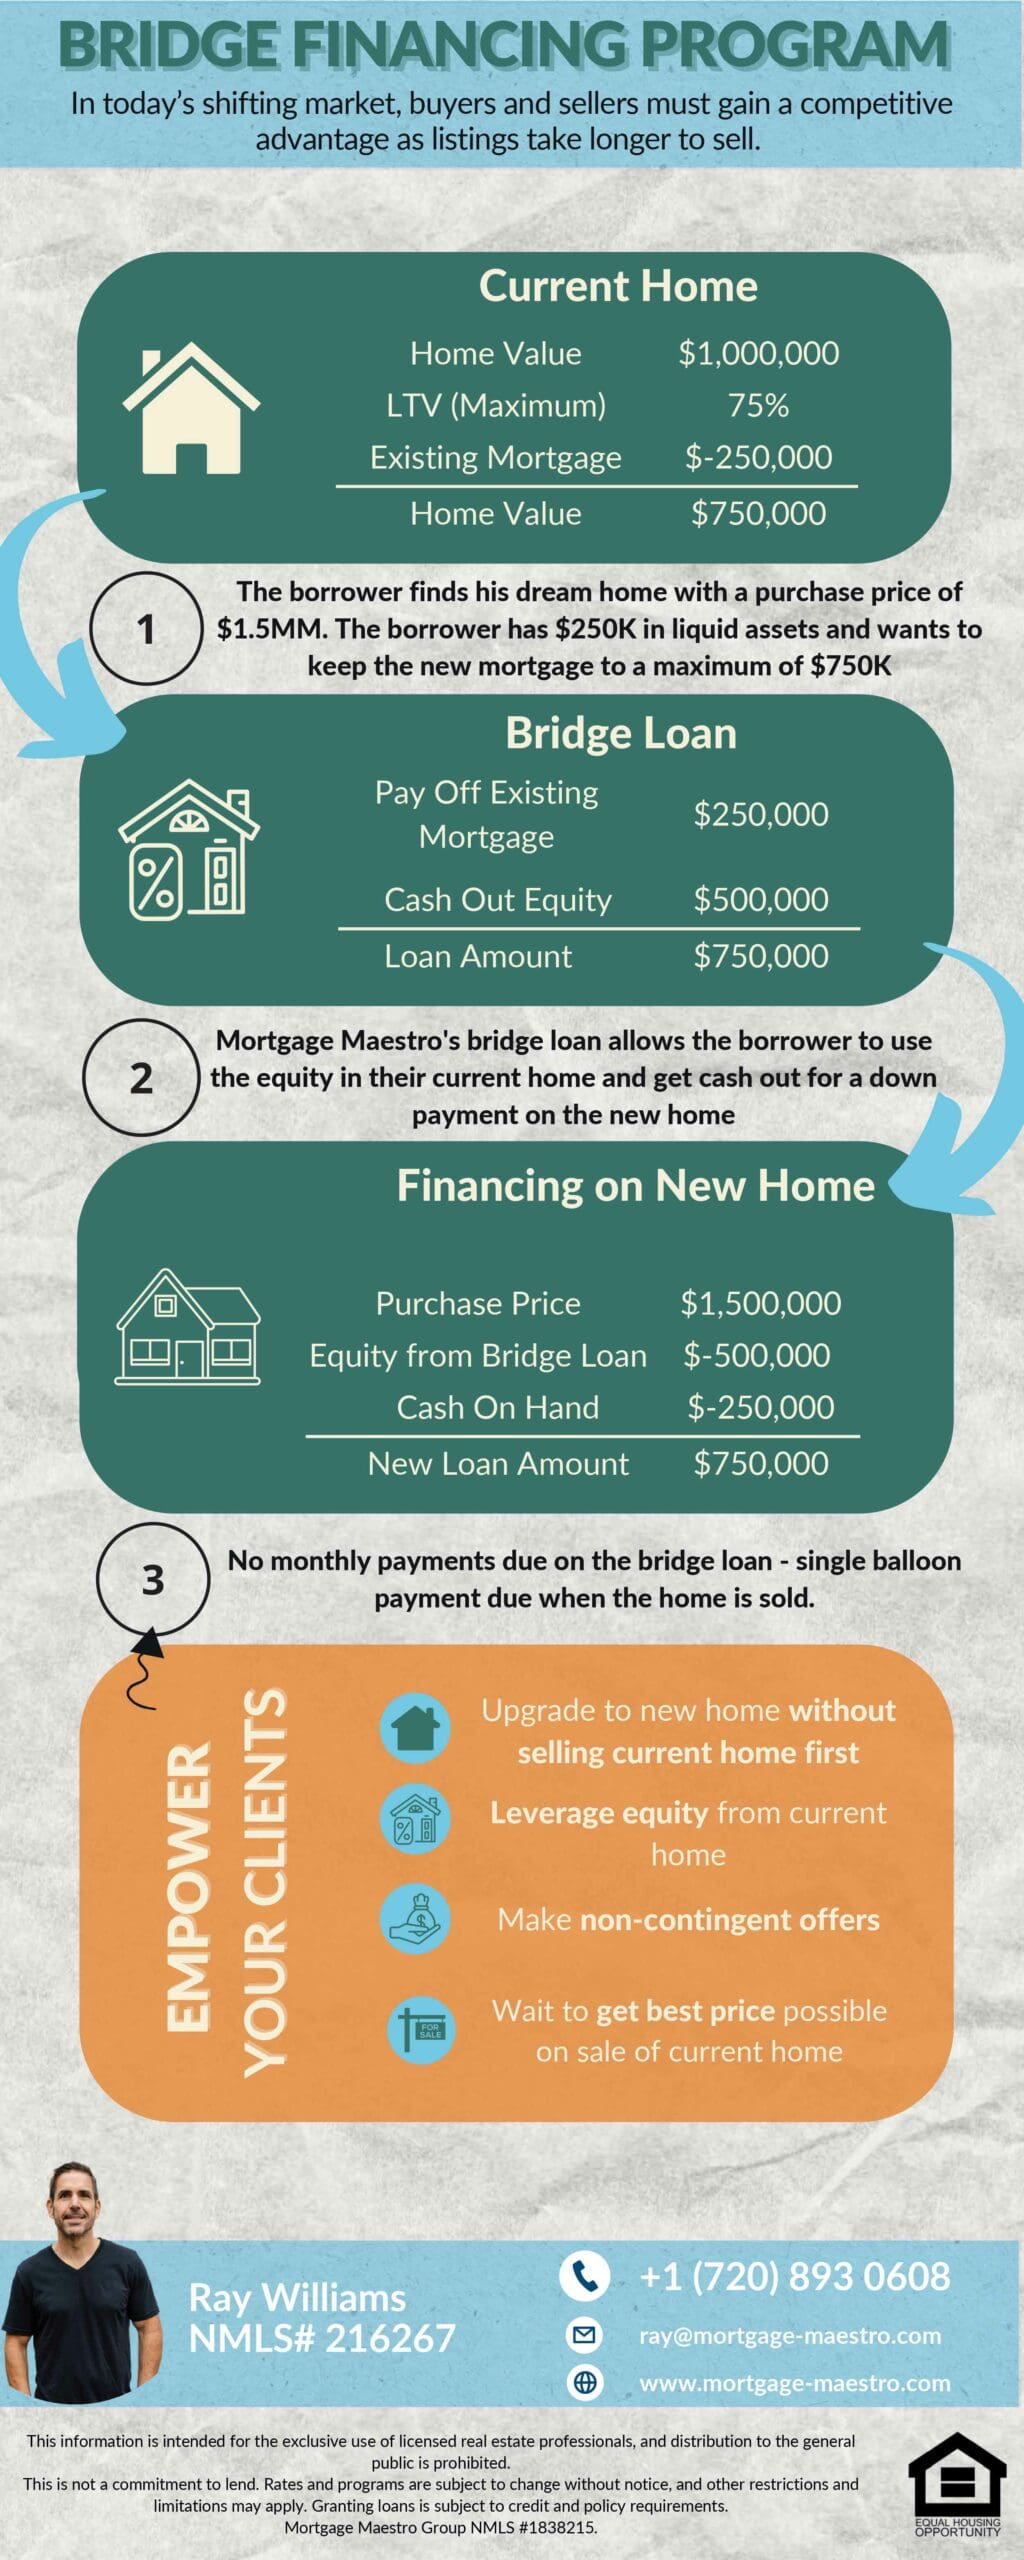
The mechanics are straightforward on paper. A lender advances funds based on the equity in your existing property, you use those funds to close on the new purchase, and then you either sell the original property or refinance it into a permanent loan to pay back the bridge. The entire process usually takes 10 to 21 days from application to funding if everything lines up. That speed is the entire reason people use them, and also the entire reason they're expensive. Here's what nobody tells you upfront: bridge lenders underwrite differently than traditional mortgage lenders. A conventional lender looks at your debt-to-income ratio, your credit score, and the appraised value of the subject property. A bridge lender cares most about the exit strategy. They want to know how you plan to repay this loan and whether that plan is realistic given current market conditions. If you're counting on selling your old home to pay off the bridge, they'll stress-test that assumption against days-on-market data for your neighborhood, not just the asking price. I had a client last year who almost got pulled into a bridge deal where the lender approved based on a 60-day sale estimate, but the local market had shifted and the average days-on-market in that zip code had crept up to 112 days. We ended up repositioning the exit strategy to include a HELOC line on the new property as a secondary payoff source, which satisfied the lender and kept the deal alive. The second thing people miss is that bridge loans are almost always interest-only during the term. You're not paying down principal while you're carrying it. That means every month you stretch the bridge beyond the original timeline, you're burning pure cost with zero equity gain. A three-month extension on a $300,000 loan at 11% adds roughly $8,250 in interest alone with nothing to show for it.
There are also structural variations you need to understand before you sign anything. Closed bridge loans have a fixed repayment date and often come with lower rates because the lender knows exactly when their money comes back. Open bridge loans have no set maturity, which gives you flexibility but typically carries a rate premium of 1 to 2 percentage points. Some lenders also offer roll-in structures where you can bundle the bridge with the new permanent financing into a single closing, which eliminates the need for two separate closings but usually means higher upfront costs and less rate shopping ability. The biggest trap I see is people treating bridge loans like a long-term solution. They're not. They're a bridge, meaning the goal is to cross them as fast as possible. If you're using a bridge loan because you can't qualify for the permanent financing anyway, you're not in a bridge situation, you're in a hard money situation and the rates and terms will be significantly worse. Make sure you actually qualify for the exit loan before you take the bridge. I've seen multiple deals fall apart because the borrower got approved for the bridge but then hit a wall during underwriting for the permanent loan, leaving them stuck paying bridge rates with no way out.
Get the Full Details