How to Actually Calculate a Motorcycle Payment That Won't Eat Your Life
Most people look at a sticker price and divide by six months in their head. That gets you nowhere fast. A real monthly payment depends on the financed amount, the APR you qualify for, the loan term, taxes, registration fees, and whatever add-ons the dealer decides to slip in. I've sat at desks with guys who thought they could afford a $12,000 bike on a $600 monthly budget, then tried to add a $1,200 insurance premium and a $400 tire-and-brake service bundle into the same payment. They couldn't handle it. The math doesn't lie. There's no universal answer, but there's a range that most financial advisors and experienced buyers agree on: your total motorcycle debt payment — including any loans or leases — should stay under 10% of your take-home pay. If you're making $4,000 a month after tax, that's $400 max. Break it down by bike type and here's what tends to work in practice: $200 to $350/month — This is the sweet spot for a used standard or naked bike in the $4,000 to $7,000 range, financed over 48 to 60 months at a decent rate. A 2017 Yamaha FZ-07 with 15k miles, for example, might carry a $5,500 price tag. At 6.5% APR over 60 months, that's roughly $107 in principal and interest. Add about $40 for taxes and fees rolled into the loan, and you're looking at $145 to $160 a month. That's well within the $200-350 band and leaves room for insurance, maintenance, and actual riding costs.
$350 to $550/month — This covers a mid-range new bike, something like a Kawasaki Ninja 650 or a BMW G 310 GS, priced between $7,000 and $10,000. On a 60-month loan at 7% APR, you're looking at about $275 to $385 in the loan payment alone. With fees and tax included, that pushes into the $320 to $440 range. Doable if your budget allows it, but you need to check whether the interest rate is actually competitive. Dealers sometimes quote base rates and then add points without telling you. $550+/month — This is where you're financing a large-displacement sportbike, a touring bike, or a premium adventure machine. A Ducati Streetfighter V4 at $24,000 on a 72-month loan at 9% APR comes to about $385 per month before fees. Once you roll in tax, title, and documentation charges, you're easily past $430. A single Yamaha YZF-R1M at $27,000 pushes the same calculation to roughly $475 before the extras. These numbers are fine if you're earning well and have no other debt, but they're dangerous if you're already carrying car payments or student loans. The real question isn't just the number — it's what that number costs you over the life of the loan. A 72-month loan at 8% on an $8,000 balance costs you about $660 in total interest. Stretch it to 84 months and the monthly payment drops by roughly $30, but you'll pay about $980 in interest instead. That's $320 extra for the convenience of a smaller check each month. Most people don't think about that tradeoff until they've already signed.
The Details Nobody Tells You Up Front
Here's where the actual calculation matters. When you get a quote from a dealer or lender, they usually give you a payment based on the MSRP minus whatever "discount" they mentioned. But the actual amount you're financing includes the following, and they add up faster than you'd expect: Document fees: anywhere from $89 to $400 depending on the state and dealer. California dealers tend to charge $150 to $250. Florida can go higher. This isn't negotiable in most cases — it's baked into the contract. Tax: sales tax varies wildly by state and sometimes by county. In Texas it's 6.25% statewide plus local option taxes that can push it to 8.25%. In New York it's 4% plus local taxes that can add another 3.875%, putting you at nearly 8% in some areas. That's on the full price including the doc fee in most states.
Get the Full Details

Registration and title: another $50 to $200 depending on where you live. This varies by county and vehicle weight class. Extended warranties and service plans: these are where dealers make their real profit. A $800 extended warranty on a $7,000 bike is a 11% markup on top of the bike price. It's optional, but they'll package it into your monthly payment so you never notice the individual line item. I ran into this exact problem with a friend who bought a used Triumph Trident 660. The dealer quoted him $389/month on a 60-month loan. He thought it was reasonable. When he broke it down, the actual loan amount was $8,200, not the $7,400 he expected, because they'd rolled in a $600 "protection package" and a $400 fee he didn't even read about. The payment looked fine until you stripped away the padding, at which point the real number was $342 — still okay, but noticeably different from what he thought he was agreeing to.
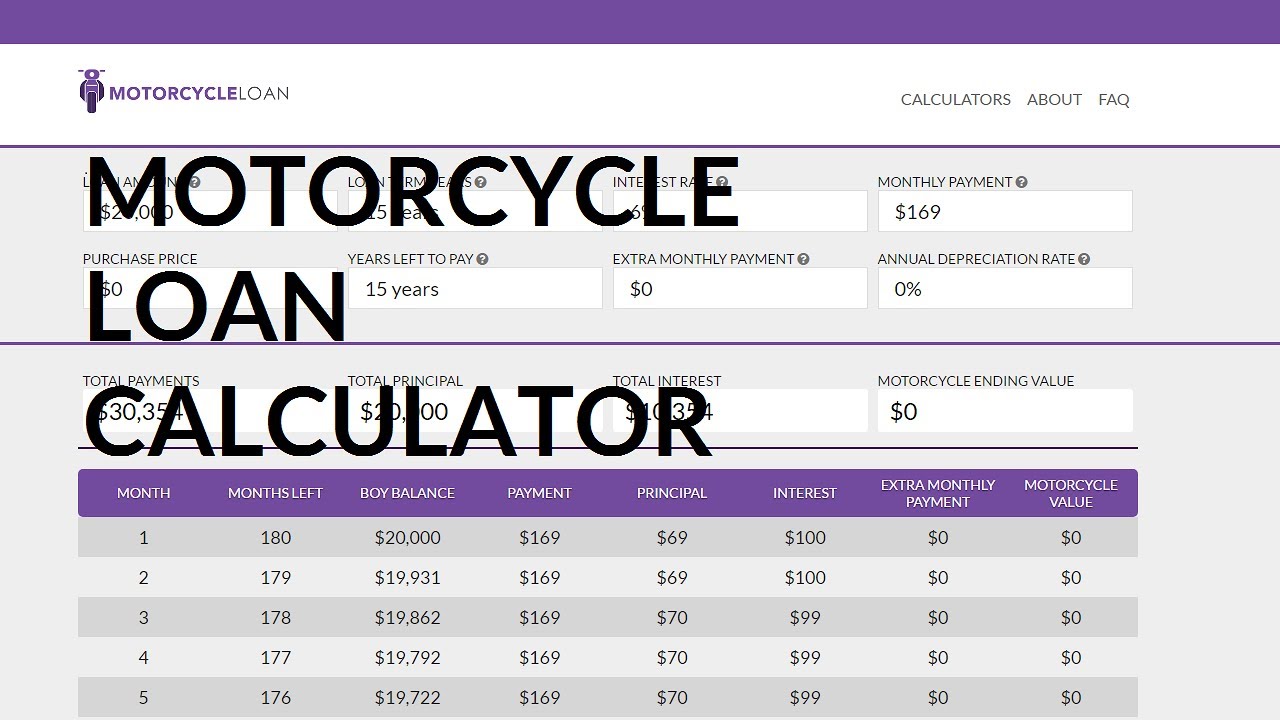
The workaround was simple: I told him to ask for the out-the-door price before anything else. Not the monthly payment. The total amount he'd be financing. Every dealer will give it to you if you ask for it in writing. Once you have that number, you can run your own calculation using any online motorcycle payment calculator or a spreadsheet. The difference between a good deal and a bad one often comes down to whether you negotiate the price or just negotiate the payment. They're not the same thing.
Interest Rates and What Actually Determines Yours
Your credit score is the biggest factor, but it's not the only one. Lenders also look at your debt-to-income ratio, how long you've been employed, and whether you're buying new or used. Here's the rough breakdown most lenders use: Excellent credit (740+): 4% to 7% APR on new bikes, 5% to 9% on used. Some lenders like lightstream or credit unions will go as low as 3.99% for qualified buyers on new equipment. Good credit (670 to 739): 7% to 12% APR. This is where most riders land. The difference between 7% and 12% on a $10,000 loan over 60 months is $143 per month versus $207 — a $64 difference that adds up to $3,840 over the life of the loan.
Fair credit (580 to 669): 12% to 18% APR. This is where things get painful. A $8,000 loan at 15% over 60 months costs $190 per month and $3,423 in total interest. That's more in interest than the bike itself in some cases. Poor credit (below 580): 18% to 25%+. Some subprime lenders will go higher. A $6,000 loan at 22% over 72 months is $128 per month with $3,216 in interest. The monthly payment looks low, but the total cost is brutal. Counter-intuitive insight: a longer loan term doesn't always mean a worse deal if the interest rate drops significantly. I refinanced a personal loan recently — not a bike, same principle — from a 72-month auto loan at 11% to a 48-month refinance at 6.2% after my credit improved. The monthly payment went up $87, but I saved $1,200 in total interest and was debt-free two years earlier. The same logic applies to motorcycle loans. If you can qualify for a shorter term with a better rate, do it. Don't let the lower monthly payment of a longer term be the only factor in your decision.
Another thing people miss: prepayment penalties. Some lenders charge them. Most don't, but it's worth checking before you sign. If your lender charges a prepayment penalty, paying extra each month or refinancing early becomes more complicated and expensive. Credit unions rarely have these. Big banks sometimes do on shorter-term loans. Independent dealerships often work with subprime lenders who almost always include them.
The Hidden Costs That Destroy Budgets
A motorcycle payment is only one part of owning a bike. Insurance alone can add $80 to $300 a month depending on your age, location, the bike you're riding, and your coverage level. A 25-year-old rider on a sportbike in an urban area will pay significantly more than a 45-year-old on a cruiser in a suburban area, even with the same coverage. Full coverage on a $12,000 sportbike for a rider under 30 can easily run $150 to $250 per month in high-risk states. Maintenance is the other silent budget killer. A new bike will cost you next to nothing in the first year. After that, tires cost $400 to $800 depending on the bike. A chain and sprocket kit runs $150 to $300. An oil change is $50 to $120. Brake pads and fluid every 12,000 to 15,000 miles costs $200 to $500. Gear upgrades — helmet, gloves, jacket, boots — can easily exceed $1,000 if you don't already have quality gear. All of this is real and all of it comes after the loan starts. I once worked with a guy who calculated his motorcycle payment perfectly, stuck to it, and still couldn't afford to ride. He'd signed a 60-month loan on a $9,000 Triumph Street Triple, budgeting $210 a month. Six months in, his front tire blew out at 8,000 miles — a known issue with that particular model and rubber compound. The replacement ran $480. His insurance had lapsed because he'd switched providers and missed the renewal date. He couldn't register the bike for three months. The total unexpected cost in the first year of ownership was about $1,400. He ate it, but it set him back financially and almost made him sell the bike.
The lesson isn't to not buy a motorcycle. It's to budget for the things that aren't in the monthly payment. Set aside $50 to $100 a month in a separate account for maintenance and unexpected repairs. It takes six months to build a $300 to $600 cushion, but that cushion prevents you from putting a $500 repair on a credit card at 22% APR.
When to Walk Away
Some deals are just bad, and no amount of negotiation will fix them. Here's when to leave the lot: If the APR is above 14% and you have good credit, something is wrong with the deal. Shop around. Get pre-approved from a credit union or an online lender before you visit the dealership. A pre-approval letter changes the dynamic entirely — the dealer knows you have options and they're less likely to inflate the rate. If they won't give you the out-the-door price in writing, they're hiding something. Walk away. Any legitimate dealer will provide a breakdown of every charge.
If the loan term is 84 months or longer on a used bike, the interest you'll pay will likely exceed the value of the bike itself within five years. That's not a joke. On a $6,000 used bike at 10% over 84 months, you'll pay roughly $1,400 in interest. On a $3,000 used bike at 14% over 84 months, you're paying nearly as much in interest as the bike is worth. Don't finance a bike you could pay cash for — especially not at those rates. If the dealer pushes you into a payment-first conversation instead of a price-first conversation, be suspicious. They want you focused on the monthly number because it's easier to swallow than the total cost. Keep bringing it back to the out-the-door price. Keep asking for the breakdown. Keep walking if they won't cooperate. A good monthly payment for a motorcycle is the one that fits comfortably within your budget after you've accounted for everything — insurance, maintenance, fuel, gear, and the total interest cost over the life of the loan. The number on the contract page isn't the whole story. Do the math yourself. Verify it. And if the numbers don't work, there are plenty of other bikes, other terms, and other dealers waiting for you.