The Reality of Keeping a Journal
A journal is a chronological record of financial transactions. That is the textbook definition. In practice, it is usually nothing so dignified. It is a working document, often messy, frequently revised, and absolutely essential if you want any hope of producing financial statements that do not look like they were generated by someone guessing. The word What Is A Journal comes up constantly in introductory accounting courses, but the classroom version rarely matches the real thing. I have sat through enough of those courses to know the difference, and I have also spent years watching people try to apply textbook rules to actual business transactions that never behave the way textbooks expect them to. The journal sits between the raw transaction and the ledger. You record the event first in the journal, then post it to the appropriate accounts. The order matters because the journal provides the audit trail. When something goes wrong three months later and you need to trace a discrepancy, you go back to the journal entry, not the ledger. The ledger is aggregated data. The journal is the original source. A typical entry includes the date, the accounts debited and credited, the amounts, and a brief description. Some people skip the description because they think they will remember what happened. They do not remember. I stopped making that mistake in 2014 after spending four hours trying to figure out why a $3,200 vendor payment had landed in the wrong expense category, and the only clue was a note I had written on the entry: "reclassified from travel to software." Without that three-word phrase, the error would have gone unnoticed until tax season. The system most people use is double-entry bookkeeping. Every debit has a corresponding credit, and the total debits must equal the total credits. This is not optional. It is the mathematical foundation that keeps the entire system from collapsing into nonsense. I have seen small business owners attempt to run single-entry journals and then wonder why their balance sheet never balanced. It will never balance because there is no mechanism to enforce equilibrium in a single-entry system. That mechanism exists in double-entry precisely because someone centuries ago figured out that people make mistakes and the math should catch them.
There are different types of journals beyond the general journal. Special journals handle high-volume repetitive transactions: sales journals, purchases journals, cash receipts journals, cash disbursements journals. A retail store with hundreds of daily sales entries would drown in inefficiency if every sale went into the general journal. The special journals exist to reduce data entry burden and improve accuracy by batching similar transactions. The general journal remains for non-routine entries: adjusting entries, correcting entries, and unusual transactions that do not fit any standard category. Understanding when to use which journal is one of those skills that separates people who actually understand bookkeeping from people who have memorized a flowchart. Here is something most beginners miss: the journal entry is not about the account names. It is about the economic substance of the transaction. People will see a transaction involving a prepaid expense and immediately reach for the prepaid asset account because the name matched the situation. But if you are receiving services on credit and the benefit extends beyond the current period, the substance might require recognizing the expense over time, not just booking it all at once. The journal entry should reflect what actually happened economically, not what the invoice looks like on the surface. This distinction becomes critical during month-end close when you are reconciling accounts and everything appears correct on paper but the numbers still do not make sense in context.
A Practical Problem and How to Handle It
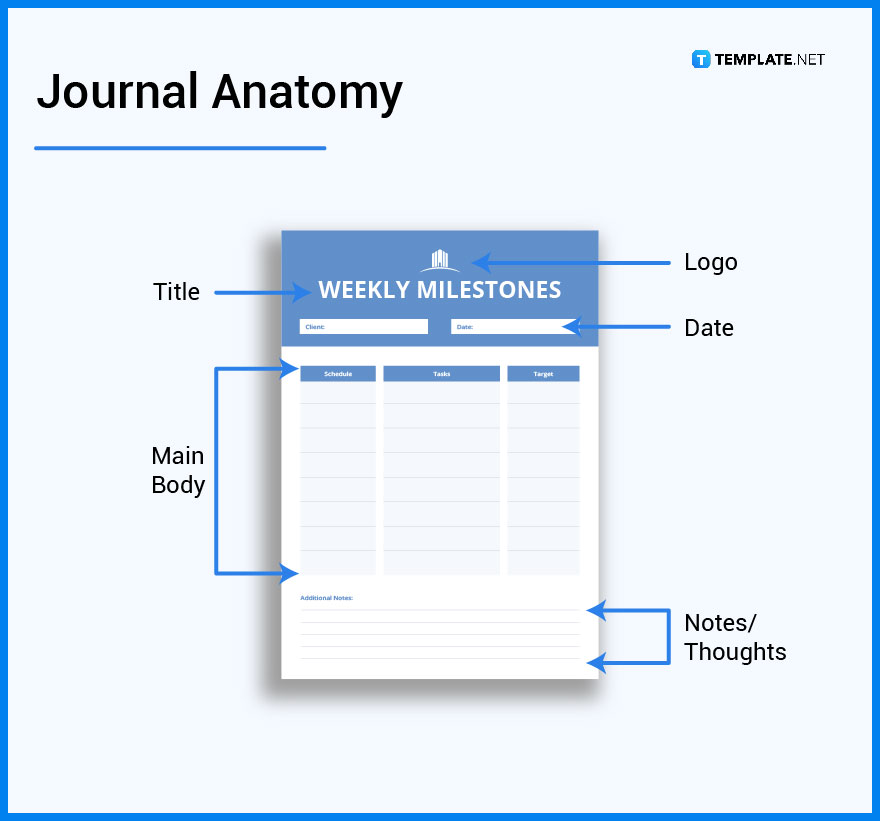
I encountered a specific issue a few years ago with a client who used a cloud accounting system and wanted to implement a proper journal process. The problem was that their previous bookkeeper had been recording journal entries directly in the general ledger module without using the journal interface at all. This meant there was no sequential numbering, no standardized description format, and no way to distinguish between original entries and corrections. When I asked for the audit trail for a particular quarter, I received a spreadsheet that the bookkeeper had compiled manually, which was itself riddled with inconsistencies. The fix was not complicated but it required discipline. I set up a journal entry template with mandatory fields: entry type (standard, adjusting, correcting, reclassifying), sequential numbering tied to the fiscal period, a description field limited to 50 characters but requiring enough detail to be useful without being verbose, and a supporting document field that linked to the scanned invoice or contract. We also established a rule that correcting entries must reference the original entry number rather than simply reversing it with a new number. This created a clear chain of custody for every transaction. The initial setup took about three hours, and the ongoing maintenance cost roughly fifteen minutes per entry instead of the twenty-five to thirty minutes the bookkeeper had been spending trying to reconstruct entries after the fact. Another common issue involves accruals and deferrals at period end. The journal entries for these are mechanical in nature, which makes them feel like something you should automate. But automation fails when the underlying assumptions change. A recurring depreciation schedule works fine until you purchase new equipment mid-quarter. A standard accrual for utilities works until the billing cycle shifts. The journal entry system needs to accommodate exceptions without breaking the pattern. I handle this by maintaining a master list of all recurring entries with their associated assumptions and review dates. Before I post any accrual or deferral, I verify that the original assumption still holds. This takes extra time but prevents the kind of compound error where an incorrect accrual gets rolled forward month after month until it becomes a material misstatement.
Get the Full Details
Where the System Breaks Down
Journals work well for straightforward transactions. They become unreliable when the volume of entries exceeds the capacity of the person reviewing them. A small business with fewer than fifty transactions per month can maintain a journal system effectively with manual oversight. A mid-size company processing thousands of entries weekly needs automation, controls, and periodic reconciliation that goes beyond what a simple journal can provide. The journal is not a substitute for internal controls. It is a tool within a broader system. When organizations treat the journal as the entirety of their accounting process, they create a false sense of security. The journal records what was entered, not what is correct. Verification requires procedures external to the journal itself: bank reconciliations, physical inventory counts, confirmation with third parties, and independent review of complex estimates. There is also the matter of timing. A journal entry can be backdated, and it happens more often than it should. People backdate entries to hit monthly targets, to correct errors discovered late in the cycle, or simply because they were too busy to record transactions promptly. Backdating is one of the leading causes of unreliable financial records. The solution is straightforward: establish a cutoff policy and enforce it. Entries must be recorded in the period they occur. If an error is discovered, the correction goes in the current period with a clear explanation, not hidden in a previous period. This is basic practice, but the prevalence of backdating suggests that basic practice is not as basic as it should be.
Getting Started
If you are building a journal system from scratch, start with the simplest possible structure and expand it as your needs grow. Do not begin with an elaborate multi-journal setup with complex approval workflows. Begin with a single general journal, a consistent entry format, and a habit of documenting every transaction thoroughly. Once that habit is established and the basic workflow is smooth, add special journals for your highest-volume transaction types. Add controls incrementally. The most common mistake I see is over-engineering the system before the fundamentals are solid. A well-maintained simple journal beats a poorly maintained complex one every time. The core principle is consistency. The journal is valuable because it is predictable. When every entry follows the same format, uses the same conventions, and maintains the same level of documentation, you can rely on it. When the format varies from entry to entry, the journal becomes a chore to read and a liability to audit. Decide on your standards early and stick to them, even when it feels inconvenient. The inconvenience of consistency is always less than the cost of inconsistency.