Understanding Partial Derivatives: A Practical Walkthrough
Partial derivatives show up in engineering, physics, economics, and basically any field where you're tracking how a system changes when one variable moves but everything else stays locked. Most people encounter the definition before understanding the point, which is backwards. Here's how the concept actually works in practice. A partial derivative measures the rate of change of a multivariable function with respect to one input variable while all other inputs are held constant. That's it. When your function depends on multiple variables—say temperature varies with both position and time—you use partial derivatives to isolate which direction matters at any given moment. The notation is f/x for the partial derivative of f with respect to x. The curved symbol distinguishes it from ordinary single-variable derivatives and signals to anyone reading your work that other variables are frozen during the calculation.
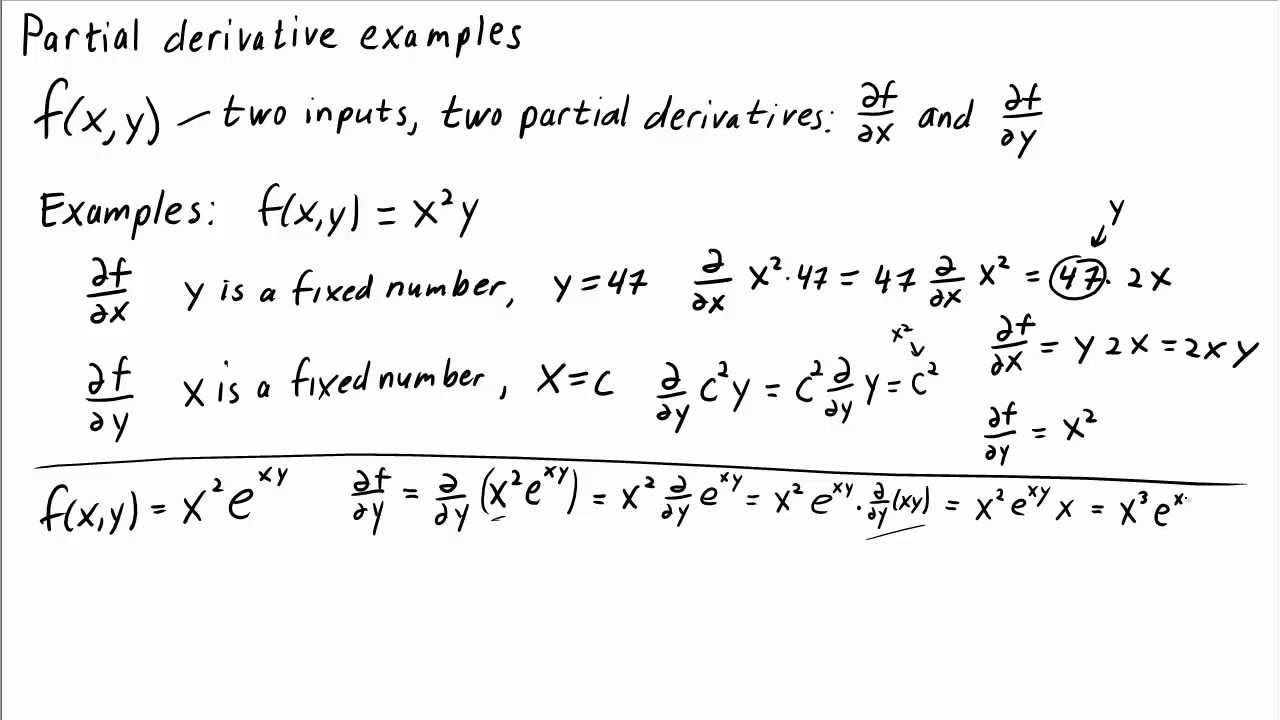
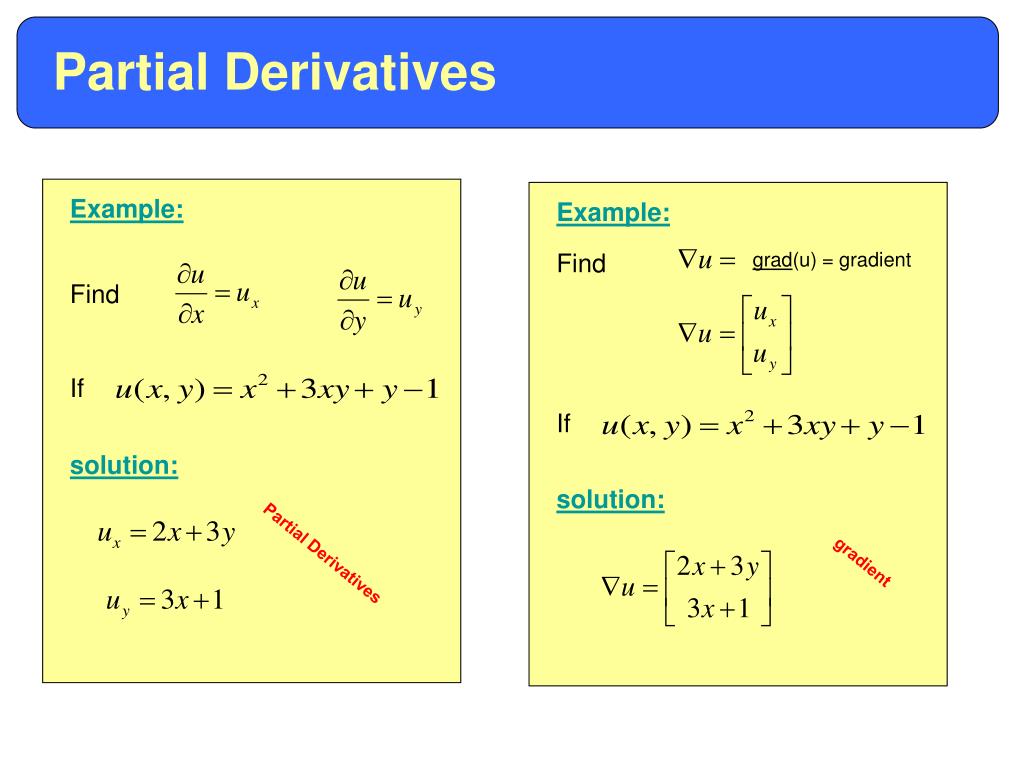
The core mechanic is straightforward. Take your function and differentiate normally with respect to your chosen variable, treating every other variable as a constant number. When you see x² + 3xy + y³ and want f/x, you treat y like it's a coefficient. The derivative of x² is 2x. The derivative of 3xy with respect to x is 3y, because y is sitting there doing nothing. The derivative of y³ with respect to x is zero, since y³ is just a constant. Result: 2x + 3y. That's the whole operation. I worked on a structural analysis project where we needed the gradient of a stress function (x,y,z) across a complex material boundary. The function had twelve variables total. We only needed the partial derivatives with respect to three of them at specific coordinate points along a welding seam. Holding the other nine constant and differentiating through the chain rule took about ten minutes per point. The alternative—numerical approximation with finite differences across all twelve dimensions—would have required thousands of function evaluations per point and introduced significant rounding error near the boundary discontinuity. Here's a worked example. Let f(x,y) = x²y + sin(xy). To find f/x, treat y as constant. Differentiate x²y to get 2xy. Differentiate sin(xy) using the chain rule: the outer derivative is cos(xy), and the inner derivative of xy with respect to x is y. That gives y·cos(xy). So f/x = 2xy + y·cos(xy). For f/y, treat x as constant. Differentiate x²y to get x². Differentiate sin(xy) the same way: the inner derivative with respect to y is x, giving x·cos(xy). So f/y = x² + x·cos(xy).
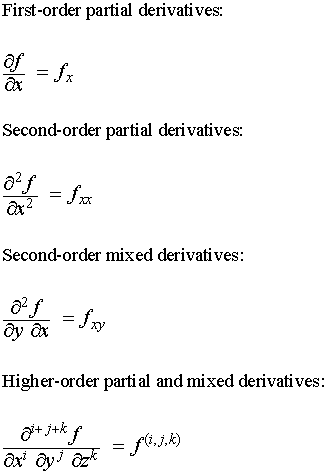
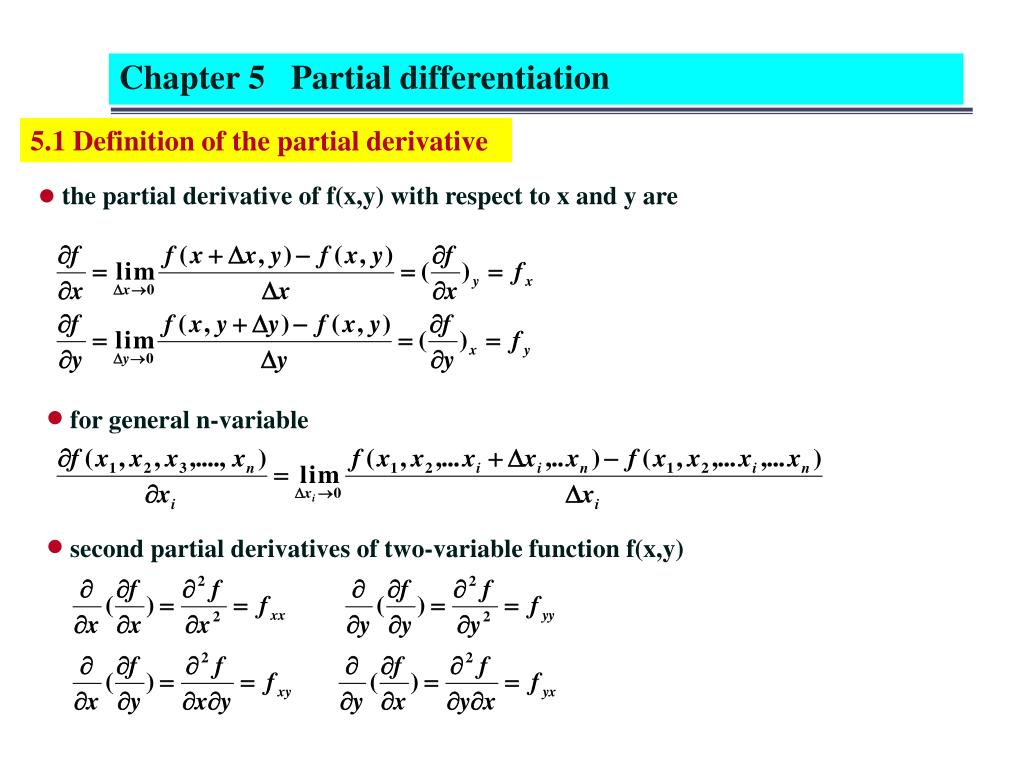
You'll notice the mixed partials usually match. If you compute ²f/xy and ²f/yx for a smooth function, they're identical. This is Clairaut's theorem, and it matters because it means the order of differentiation doesn't affect your result for well-behaved functions. In practice this lets you choose whichever order is computationally simpler. If one order produces simpler intermediate expressions, take it. Don't compute both unless you're verifying your work. There's an edge case that catches people regularly. When your function involves piecewise definitions or absolute values, the partial derivative may not exist at the boundary points even if the function itself is continuous. I encountered this when modeling a cost function with a threshold penalty: the function was defined differently below and above a certain input value. The partial derivative was straightforward everywhere except at that threshold. Standard symbolic differentiation tools would return a result that was technically wrong at exactly that point. My workaround was to compute left and right partial derivatives separately at the boundary and flag those points in the optimization routine. The optimizer then used a subgradient instead of a full gradient, which prevented it from getting stuck or diverging at the discontinuity. It added about five percent overhead to the computation but eliminated the convergence failures that were costing us hours of debugging. Another thing beginners miss: partial derivatives are directional. f/x tells you the slope along the x-axis direction at a point. It says nothing about the slope in other directions. The total derivative or the gradient vector combines all partial derivatives into a full picture. If you're doing optimization, you need the gradient, not individual partials. If you're doing sensitivity analysis on a single parameter, the partial is exactly what you want. Confusing the two leads to incorrect conclusions about how a system responds to changes.
Get the Full Details
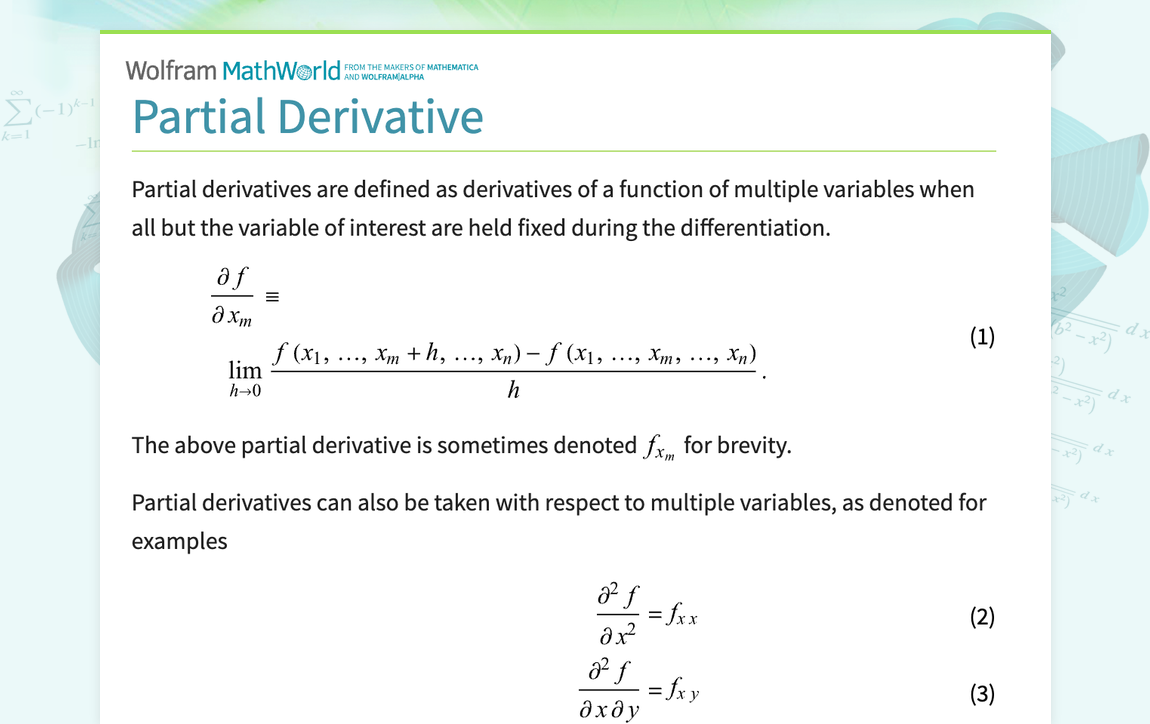
The Jacobian matrix generalizes this concept to vector-valued functions. Instead of one output, you have multiple outputs, each with partial derivatives with respect to each input. The result is a matrix where entry (i,j) is the partial derivative of output i with respect to input j. Robotics uses Jacobians constantly for inverse kinematics. When you're solving for joint angles that produce a desired end-effector position, the Jacobian tells you how small changes in each joint affect the final position. If the Jacobian is singular—determinant equals zero—you've hit a workspace boundary where the robot loses a degree of freedom. You can't solve for certain motions at that configuration regardless of your algorithm. Numerical computation deserves a mention. When you can't or don't want to compute partial derivatives analytically, finite difference methods approximate them. Forward difference uses [f(x+h,y) - f(x,y)] / h. Central difference uses [f(x+h,y) - f(x-h,y)] / 2h. Central difference is generally preferred because its truncation error is O(h²) versus O(h) for forward difference, meaning you get roughly twice the accuracy for the same step size or can use a larger step size to avoid floating-point issues. The tradeoff is that central difference requires two extra function evaluations per partial derivative instead of one. In high-dimensional problems with expensive function evaluations, that adds up. Automatic differentiation tools like those in PyTorch, TensorFlow, and JAX handle partial derivatives programmatically without you writing the symbolic math. They track operations through a computation graph and apply the chain rule automatically. This is what powers modern machine learning training. The catch is that auto-diff only works on differentiable operations. If your function contains a conditional branch, a lookup table, or a non-differentiable activation like the Heaviside step function, the partial derivative is undefined at those points. You need to either smooth the function or use subgradient methods. Neural networks mostly avoid this because ReLU and similar activations have well-defined subgradients, but custom loss functions can introduce problems quickly.
Finite element analysis relies heavily on partial derivatives, though practitioners rarely think of them that way. The weak form of a PDE involves integrating partial derivatives against test functions over a mesh domain. If your mesh is too coarse relative to the gradient variation in your solution, the computed partials will be inaccurate and your results will drift. Refining the mesh near high-gradient regions usually resolves this, but it increases computational cost nonlinearly in three-dimensional problems. I've seen projects where partial derivative accuracy was the bottleneck, not the solver itself.
When Partial Derivatives Fail You
Partial derivatives assume the function is differentiable at the point of interest. Non-differentiable points exist and they cause problems. Absolute value functions, max and min operations, floor and ceiling functions, and any function with a sharp corner or cusp will have undefined partial derivatives at specific locations. In optimization, gradient-based methods completely break down at these points. You need either a subgradient formulation or a derivative-free optimization approach like Nelder-Mead or particle swarm. High-dimensional problems expose another limitation. Computing all partial derivatives scales linearly with the number of input variables for analytical methods but requires n function evaluations for finite difference methods. At twenty dimensions you're already doing twenty evaluations per gradient step. At two hundred dimensions, which is common in some fluid dynamics simulations, the cost becomes prohibitive. Hessian-free methods and limiters on the number of dimensions you differentiate with respect to are the practical workarounds, but they approximate rather than compute exact partials. Black-box functions present a similar problem. If you can only evaluate a function and not inspect its formula, you're forced into numerical differentiation. The accuracy degrades rapidly as the step size approaches machine epsilon due to floating-point cancellation error, and grows large as the step size increases due to truncation error. The optimal step size sits somewhere in between, typically around 10^-8 for double-precision arithmetic, but finding it experimentally is tedious and context-dependent.
The notation itself can be ambiguous in applied settings. When you write T/t in thermodynamics, you need to know what other variables are being held constant. Temperature might be expressed as a function of volume and pressure, or volume and entropy, or pressure and entropy. Each choice gives a different numerical value for the same symbolic expression. physicists handle this by writing T/t|_V to indicate constant volume, but engineers often omit the subscript and rely on context. If you're working across disciplines, clarify the constraint explicitly to avoid mismatches.
Practical Tips That Actually Matter
When computing partial derivatives by hand, simplify the function first. Expanding products, combining like terms, and rewriting expressions in the most tractable form before differentiating saves time and reduces errors. A function written as a single fraction often becomes two simpler terms after partial fraction decomposition, and each term differentiates cleanly. I've watched people spend twenty minutes differentiating a messy expression that could have been reduced to three simple terms in thirty seconds. Check your units. If f represents energy in joules and x is distance in meters, then f/x has units of joules per meter, which is force in newtons. Dimensional analysis catches mistakes immediately. If your partial derivative has the wrong units, you've made an error somewhere in the calculation. This is especially useful when working with unfamiliar functions or when translating between unit systems. Verify mixed partials numerically as a sanity check. Compute ²f/xy and ²f/yx both analytically and compare. They should match. If they don't, either you made an algebra mistake or the function isn't sufficiently smooth at the point you're evaluating. This check takes two extra minutes and has caught errors that would have been much costlier to trace later.
For programming applications, prefer auto-diff over manual implementation unless you have a specific reason not to. Manual partial derivative implementation introduces bugs at a rate proportional to the complexity of the function. Auto-diff implementations in mature libraries are thoroughly tested and handle edge cases like numerical overflow and underflow. The performance difference is negligible for most applications. Only implement manually when you need transparent control over every computational step, such as in educational contexts or when memory constraints prevent building the full computation graph. The partial derivative is a tool for isolating causal relationships in multivariable systems. It tells you what happens when you nudge one input while holding everything else fixed. That isolation is both its strength and its limitation. Real systems rarely hold variables constant in practice, which is why partial derivatives are most useful as building blocks within larger frameworks like gradients, Jacobians, and directional derivatives rather than as standalone answers.
![Partial Derivative Examples Solved] Find All Second Order Partial](https://i.ytimg.com/vi/LE4YrgRnr-s/maxresdefault.jpg "Partial Derivative Examples Solved] Find All Second Order Partial")
