What Variance Analysis Actually Looks Like in Practice
I spent about six months trying to make sense of a production budget that kept blowing up. Revenue tracked fine. Costs jumped in three different categories and I couldn't figure out which part of the operation was responsible. That's when someone suggested variance analysis instead of just looking at totals and hoping for the best. It turned the whole thing around. The basic idea is simple enough. You compare what actually happened against what you expected to happen. The difference between those two numbers is your variance. Most people stop there, but the real work begins after you spot the gap. You need to figure out why it exists and whether it matters.
What Is A Variance Analysis
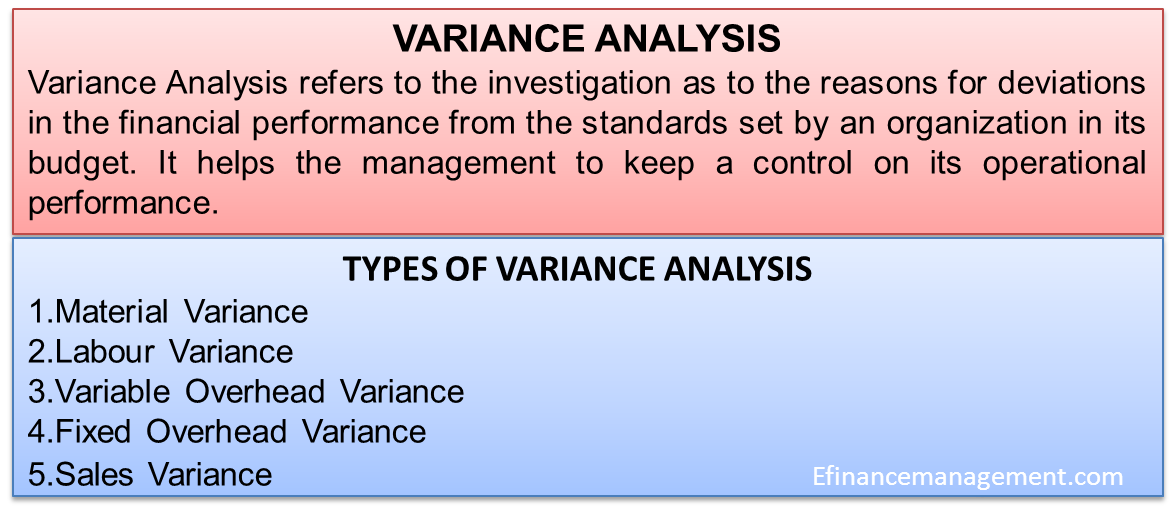
Variance analysis is the methodical breakdown of differences between planned figures and actual results. It shows you where money went wrong and often points directly at the source. In budgeting and accounting, this means looking at revenue, expenses, materials, labor, and overhead. Manufacturing companies track standard costs versus actual costs. Service firms compare projected hours or billable rates against reality. The structure stays the same even when the numbers change. Here is how it actually works step by step. First, establish your baseline. This is the budget, forecast, or standard cost you are comparing against. Without a clear reference point, variance analysis is just number crunching with no direction. The baseline should be realistic. Inflated budgets create false variances that hide real problems.
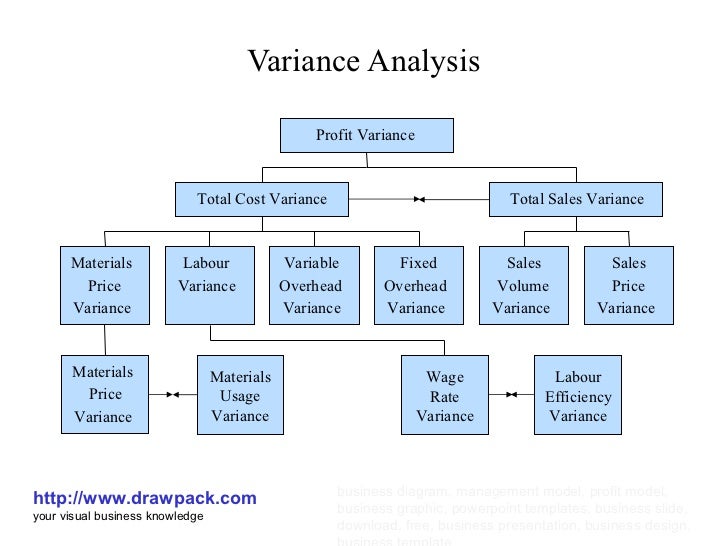
Next, collect actual data. This should be the real numbers from the same period, measured the same way. Mixing cash basis and accrual basis numbers in the same analysis produces garbage results. Make sure everything aligns before you calculate. Then compute the raw variance. Actual minus planned. Positive or negative depending on whether you are tracking costs or revenue. Revenue above target is good. Costs above target are bad. Keep that distinction clear from the start. After that comes the hard part. Breaking the total variance into component parts. For manufacturing, you might split material costs into price variance and usage variance. For labor, you separate rate variance from efficiency variance. Each piece tells a different story.
Get the Full Details
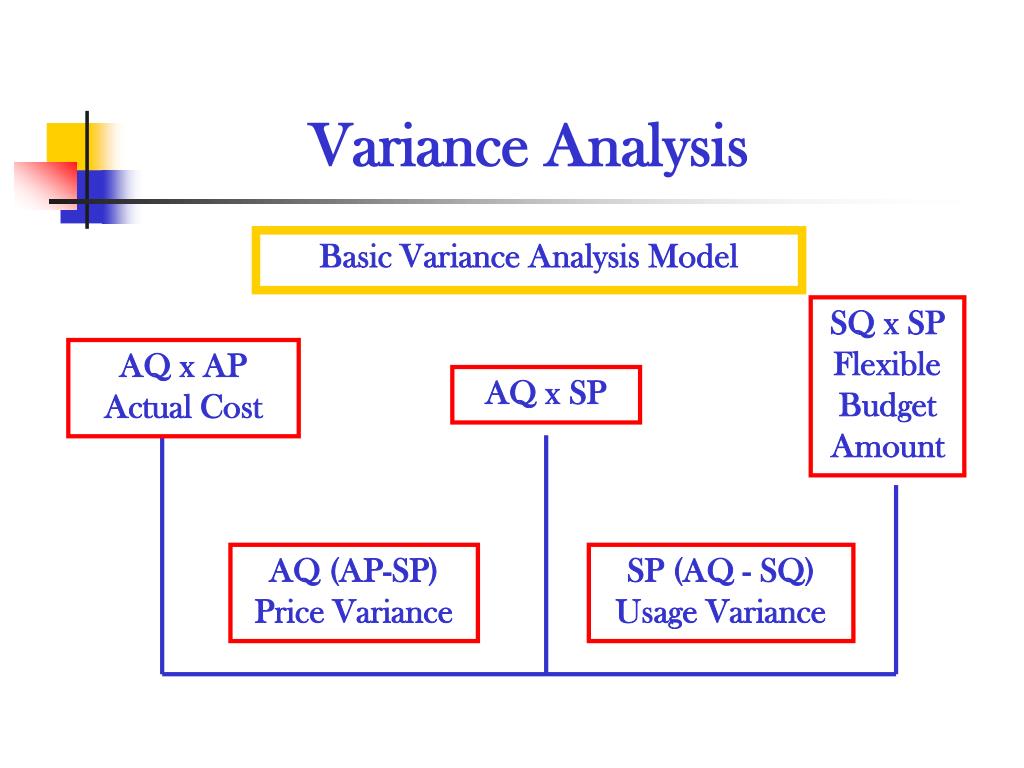
Price variance shows whether you paid more or less per unit than expected. Usage variance shows whether you consumed more or less than expected for the output produced. Together they explain the full picture. Missing either one leaves you guessing.
A Real Example From My Own Experience
Last year I worked on a project where the total cost came in at about forty percent over budget. That sounds catastrophic, but the variance analysis revealed something totally different. The labor variance was negligible. Training hours matched the plan closely, and hourly rates stayed flat. The problem was entirely in material pricing. We had locked in a supplier contract in January. By March, raw material prices had spiked because of supply chain disruptions that nobody had flagged. The procurement team kept ordering through the old contract terms. When we traced the variance back to the price component, the fix was straightforward: renegotiate or switch suppliers. But without the analysis, we would have kept looking at labor and productivity, wasting weeks on the wrong problem. The raw material price variance in that case accounted for nearly all of the forty percent overshoot. Once we identified that, the conversation shifted immediately from "are our people inefficient" to "why are we buying steel at old prices."
Common Pitfalls That Waste Time
The biggest mistake I see is stopping at the headline number. Saying "we are over budget by ten percent" tells nobody anything useful. The second mistake is blaming the wrong department. Labor is often the easiest target because it is visible. But sometimes the issue lives in purchasing, or inventory valuation, or even revenue recognition timing. Another problem is using static budgets as the baseline when activity levels changed dramatically. If production doubled, comparing actual costs to a budget built for half that volume creates misleading variances. A flexible budget that adjusts for actual activity levels fixes this. It should be the default approach, not the exception. Materiality thresholds also matter. Looking at every penny of variance everywhere produces noise. Focus on the significant differences. There is no universal rule for what counts as significant, but most teams use a percentage of budget or a fixed dollar amount. Pick one and apply it consistently across periods.
When Variance Analysis Breaks Down
This method is not a silver bullet. It depends entirely on having reasonable plans to begin with. If your original budget was based on guesses rather than data, the variances will be meaningless. Garbage in, garbage out applies here more than anywhere else in accounting. It also struggles with multi-variable situations. When price, volume, mix, and efficiency all shift at the same time, isolating each factor requires careful mathematical treatment. The standard variance formulas work, but only if you understand what each formula actually measures. Using the wrong formula for a volume variance, for example, can reverse the interpretation entirely. There is also a timing issue. Variances are historical. They tell you what already happened. If you need real-time control, variance analysis alone is too slow. Pair it with leading indicators like purchase order approvals, production scheduling checks, and daily run-rate monitoring. Those give you early warning. Variance analysis explains the aftermath.
Tools and Templates
Most variance analysis can be done in a spreadsheet. A well-structured template with separate tabs for input data, calculations, and results keeps things manageable. I prefer a layout that mirrors the standard formulas: price variance, quantity variance, and total for each cost element. Add conditional formatting to highlight significant items. This turns a wall of numbers into a report that anyone can scan quickly. For larger operations, specialized ERP modules handle the calculations automatically. SAP, Oracle, and similar systems include variance analysis built into their costing modules. The output is faster and less prone to formula errors, but the underlying logic is identical. You still need someone who understands what the numbers mean. If you want a downloadable template to start with, search for "variance analysis template excel manufacturing" or "flexible budget variance spreadsheet." These are widely available and easy to adapt to your own structure. The key is building the component splits into the template from day one, not adding them after the fact.
Advanced Nuances
One counter-intuitive finding from my experience is that favorable variances can sometimes signal future problems. If your material usage is significantly under budget, it might mean your team is cutting corners on quality. The numbers look good today but defects will show up next quarter. Favorable does not always mean good. Always check what drove the variance before celebrating. Another thing beginners miss is the interaction effect. In standard variance analysis, price and quantity variances are calculated independently. But in reality, they influence each other. Paying a higher price for better quality material might reduce waste and improve efficiency. The isolated price variance looks unfavorable, but the combined effect could be positive. Advanced analysis separates the pure price effect from the mix and yield effects to give a cleaner picture. It takes more effort but reduces misinterpretation significantly.

The Bottom Line
Variance analysis is one of those tools that looks basic on paper and delivers real value in practice, provided you do the work beyond the calculation. Identify the baseline. Calculate the raw difference. Break it down into components. Investigate the cause. Act on the finding. Most organizations skip step four or rush it. That is why the exercise often feels pointless in companies that treat it as a compliance task rather than a diagnostic tool. The approach I described cuts the investigation time from days to hours in most cases. Before variance analysis, I was spending weekends chasing rumors about where costs leaked. After, I could look at a three-page report and know exactly which department to question and what documents to request. That is the difference between guessing and knowing.