The mechanics of trade and value, stripped down
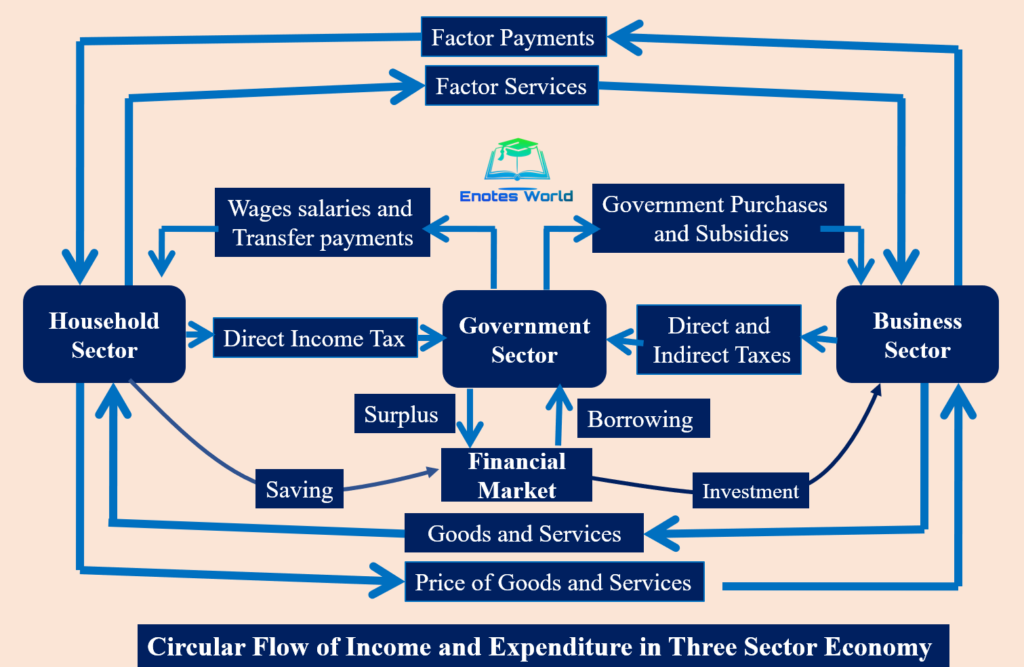
An economy is just a system for deciding how to allocate scarce resources. That is the textbook definition, and it is also more or less the entire thing. People produce things, people consume things, and something in between determines who gets what. Money is the primary coordination mechanism in most modern systems, but money is not the economy. It is a tool. The economy is the network of decisions that happens around that tool. It is helpful to think about this at two scales. The micro level is individual choices. You decide whether to buy a coffee or make it at home. That is an economic act. The macro level is the aggregate of billions of those decisions, which creates inflation, unemployment rates, GDP numbers, and business cycles. Both levels are real. Both matter. Confusing them is a common beginner mistake that leads to poor policy opinions and worse investment decisions. I spent years working in supply chain logistics, and the first time I really understood what an economy was, it had nothing to do with textbooks. I was managing procurement for a mid-size manufacturing firm during the 2021 chip shortage. We had a line that could produce $40,000 worth of units per day, and we were sitting at zero because a single component from a supplier in Taiwan was backordered. The economy in that moment was not a graph. It was a phone call at 11 PM with a purchasing agent in Shenzhen who knew someone at a distributor who might have three weeks of stock. That is what the macro numbers miss. They smooth over the friction.
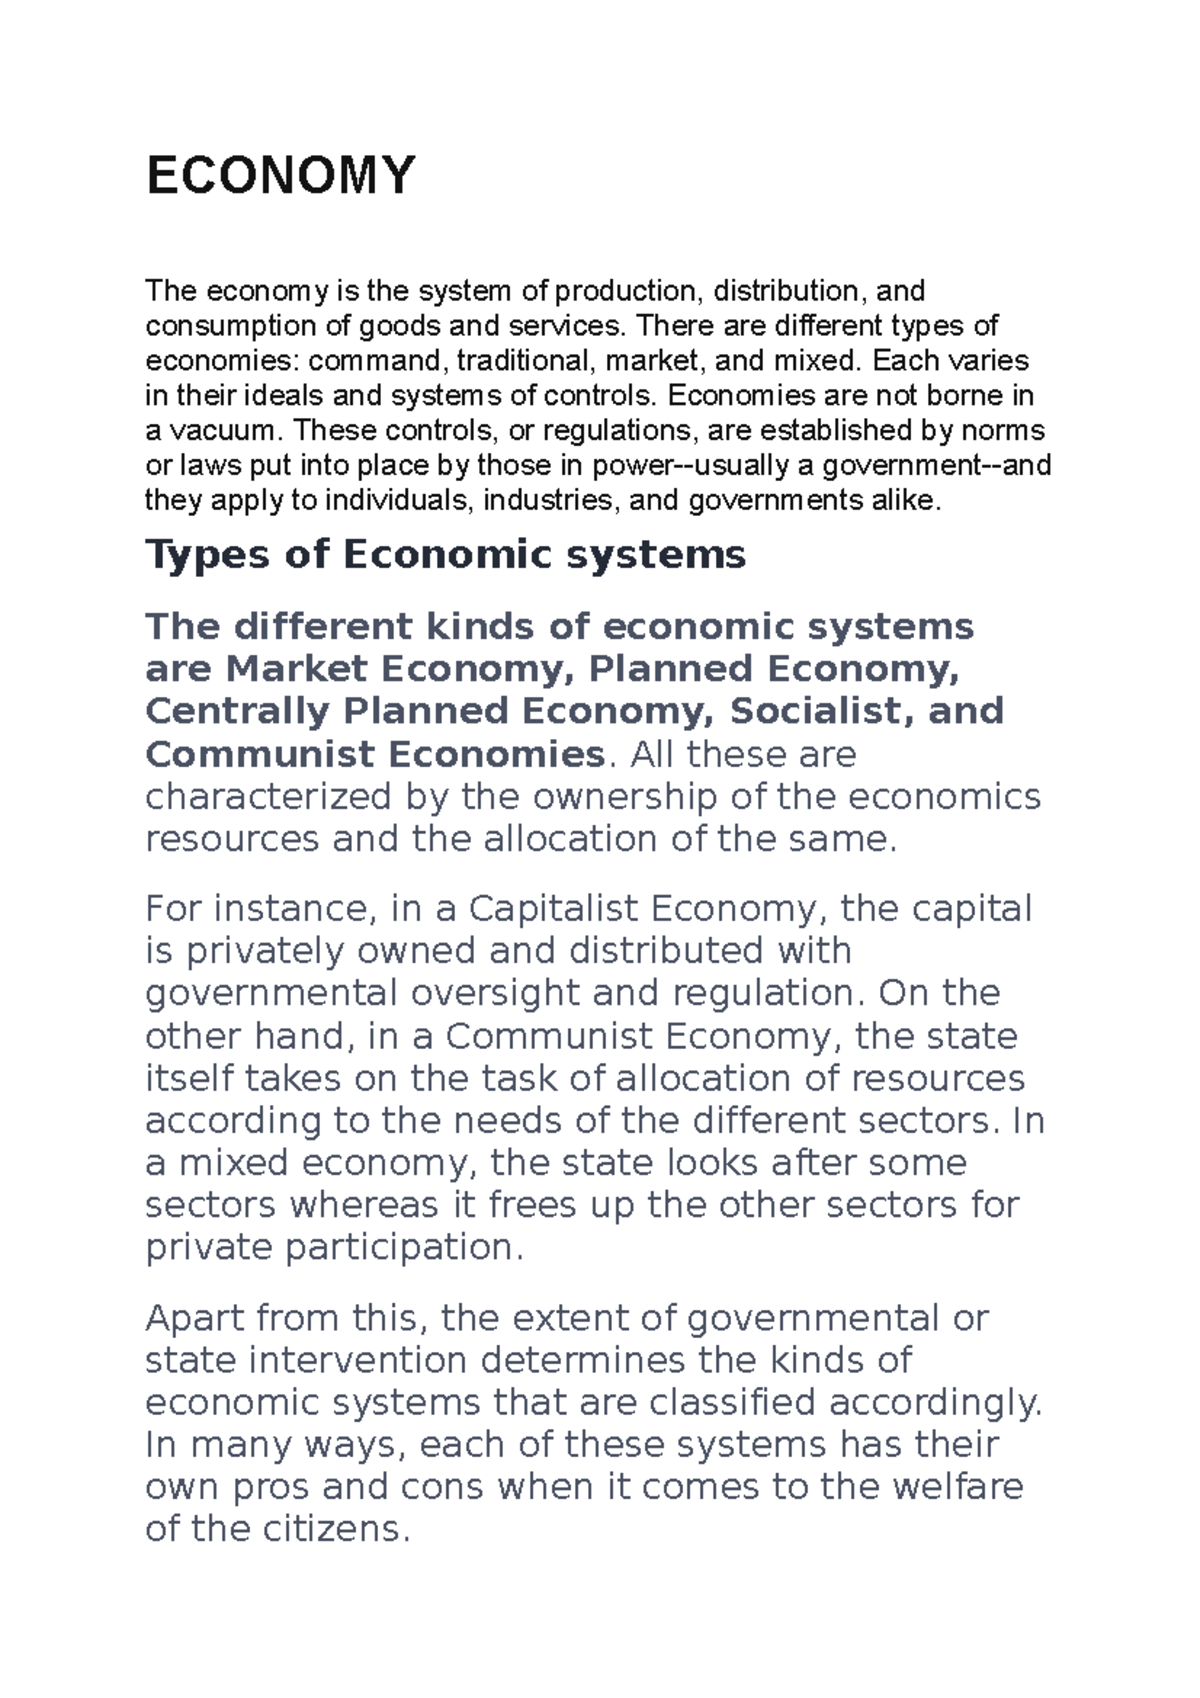
There are different types of economies, and the categorization matters more than people admit. A command economy like the Soviet Union attempted to replace market signals with central planning. It lasted decades but collapsed under its own information problem. No central committee can process the same amount of localized knowledge that price signals move through a market in real time. A market economy delegates those decisions to individuals and firms. A mixed economy, which is what almost every functioning country actually uses, combines both with varying degrees of regulation, subsidies, and state ownership. The United States is mixed. China is mixed. There is no pure version of anything except in economics textbooks, and those exist for pedagogical convenience, not realism. One thing most people get wrong about economies is how they handle shocks. The standard model assumes equilibrium, but real economies spend most of their time in disequilibrium. Prices do not adjust instantaneously. Wages are sticky. Contracts lock in commitments. When a shock hits, the adjustment process is messy and slow, and it disproportionately affects the people least able to absorb it. I watched this firsthand when our raw material costs tripled overnight during that shortage. We could not raise prices fast enough to match because of long-term contracts with customers. We absorbed the loss for six months before we could renegotiate. The economy kept moving, but the people running the firm were making triage decisions in real time, not optimizing toward some theoretical maximum. The measurement problem is another area where the theory diverges from practice. GDP is the most commonly cited metric, and it is also one of the least useful for understanding actual economic well-being. It counts transactions, not value. It does not subtract environmental degradation, unpaid care work, or the depletion of natural capital. It double-counts in some cases and misses entire sectors in others. I have seen executives and policymakers treat GDP growth as the goal rather than a means, which is like treating a speedometer as the destination. A better approach combines multiple indicators: GDP per capita adjusted for purchasing power, the Human Development Index, Gini coefficient for inequality, and sector-specific productivity metrics. None of these are perfect. All of them are better than GDP alone.
Currency is worth a separate look because it is the most visible part of any economy and also the most misunderstood. Money functions as a medium of exchange, a unit of account, and a store of value. Most currencies fail at least one of these under stress. During hyperinflation events, money stops being a store of value overnight. People switch to stablecoins, foreign currencies, or barter. Venezuela and Zimbabwe are recent examples. The workaround in those situations is not to wait for government policy to catch up. It is to hold assets denominated in currencies that are not subject to the same inflationary pressures. This is not investment advice. It is an observation about what actually happens when monetary systems break. Institutional quality is the variable that separates economies that grow from economies that stagnate. Property rights, contract enforcement, regulatory predictability, and low corruption create an environment where investment flows and innovation happens. Without those, you get capital flight, informal markets, and rent-seeking behavior that dominates over productive activity. I worked with a firm that expanded into a Southeast Asian market with high growth potential but weak property rights. We spent more time on legal protections and relationship building than on actual operations in the first two years. The revenue materialized, but the risk-adjusted return was mediocre because the institutional overhead was so high. This is why development economists focus on institutions more than raw resource endowments. Globalization has complicated the picture considerably. Supply chains now span multiple jurisdictions, currencies, and regulatory regimes. A product designed in California, assembled in Vietnam, using components from South Korea and Germany, and sold in Europe represents a tiny fragment of interconnected economic activity. This increases efficiency but also increases systemic risk. A port closure in one country can halt production on three continents. The pandemic exposed this clearly, and the subsequent reshoring and nearshoring trends are direct responses to that vulnerability. The question is not whether globalization is good or bad. It is about finding the right balance between efficiency and resilience, which is a tradeoff that has no single correct answer.
Get the Full Details
For anyone trying to understand how an economy actually works rather than how it is taught to work, the best starting point is to pick a specific sector and trace the value chain. Look at how a loaf of bread gets from wheat farmer to supermarket shelf. Follow the money, the materials, the labor, and the regulations at each step. You will see taxes, markups, transport costs, labor negotiations, and consumer demand all interacting in real time. This exercise is more revealing than any macroeconomic model because it forces you to confront the granularity that aggregate data obliterates. The economy is not a machine. It is a living system, and treating it like one usually gets you in trouble. Practical takeaway: if you are analyzing an economy for business or investment purposes, start with institutional risk, then look at demographic trends, then examine sector-specific dynamics. Most analysts reverse that order and get confused when their models fail in practice. The sequence matters because institutions shape everything else. Demographics shape the timeline. Sector analysis gives you the entry points.