The Quick Answer
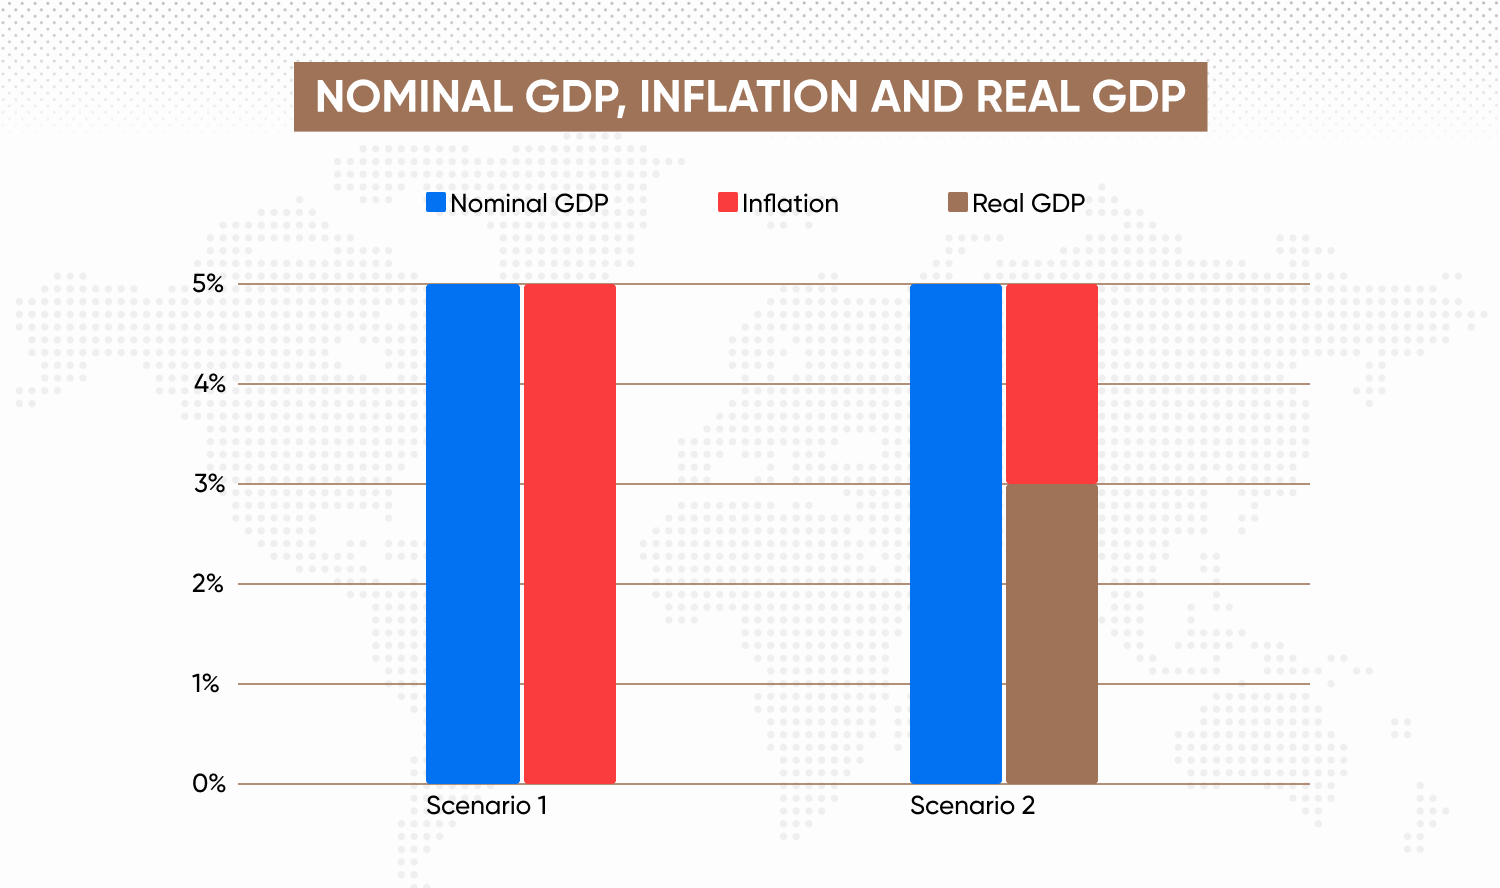
Nominal GDP measures the value of all goods and services produced in a country using current prices. Real GDP adjusts that number for inflation, so you can tell whether the economy actually grew or just got more expensive. That's the textbook version. Here's how it shows up when you're actually working with the numbers. The gap between the two is entirely driven by price changes. If prices stay flat from one year to the next, nominal and real GDP are identical. If prices rise, nominal GDP will always come out higher than real GDP, because it's capturing both more output and higher prices at the same time. The difference is what economists call the GDP deflator — it's the implicit price index that bridges the two. I used to flag down people explaining this and point at the GDP deflator like it was some kind of magic wand. It's not. It's just nominal divided by real, times 100. The formula itself is trivial. What trips people up is what the deflator actually captures and what it misses.
Let me walk through a concrete example so this sticks. Say Country X produced 100 loaves of bread at $2 each and 50 gallons of milk at $3 each in 2023. That's nominal GDP for 2023 equaling $350. In 2024, they still produce 100 loaves and 50 gallons, but bread jumps to $2.20 and milk to $3.30. Nominal GDP becomes $385. Real GDP, calculated using 2023 prices, stays at $350. The economy didn't grow at all. The only thing that changed was the price tag. The GDP deflator for 2024 is 110, which means prices overall rose 10%. That's the entire concept in about ten minutes. But the way people actually use these numbers in practice is where things get messy, and where most explanations fall short.
Why The Distinction Matters In Real Work
I spent years reviewing macroeconomic forecasts for investment decisions, and the single most common error I saw was treating nominal growth figures as if they represented real economic expansion. A client once pitched a manufacturing facility in a country reporting 8% nominal GDP growth over two years. When we recalculated using the local deflator, real growth was closer to 1%. The project wasn't viable. The nominal headline had been misleading the entire term sheet. The reverse problem exists too. Some countries publish real GDP revisions that look dramatic but are actually just methodological changes. When China switched to a chained-dollar methodology in 2016, their historical real GDP figures shifted noticeably without any actual change in output. Nominal comparisons across eras became less reliable because the base year rotated instead of staying fixed. Here's something most beginners miss: nominal GDP can be useful on its own when you're analyzing debt-to-GDP ratios with current-market financing costs. Debt service payments are made in current dollars. Comparing nominal debt obligations to nominal GDP gives you a truer picture of near-term solvency pressure than pulling in real figures. Central banks routinely do this analysis, and it's not an accident.
Get the Full Details

The Hidden Problem With GDP Deflators
The GDP deflator is broader than the CPI, which sounds like an advantage. It covers all domestically produced goods and services, not just consumer purchases. But that breadth is also the problem. The deflator includes capital equipment, government spending, and exports. When oil prices spike, the deflator moves because energy inputs affect production costs across the board, not because consumers are paying more at the pump. That's a feature and a bug depending on what you need the number to tell you. I ran into this directly when analyzing Eastern European economies in the early 2020s. The nominal GDP numbers looked strong because commodity export prices were elevated. But the real GDP figures told a different story — domestic demand was actually contracting. The deflator was inflating the headline. A policymaker looking only at nominal figures would have drawn the wrong conclusion about economic health. We ended up cross-referencing the deflator with sector-level producer price indices to isolate whether price movements were coming from external commodities or internal cost pressures. That took about three days of additional work but prevented a costly misreading.
When Real GDP Misleads Too
Real GDP isn't the honest number people pretend it is. It measures quantity changes relative to a base year, and that base year introduces artifacts. When the base year is several years old, the weighting of different sectors becomes stale. A country that shifted from agriculture-heavy to tech-heavy won't reflect that transition accurately until the base year is updated. Most national statistical agencies revise the base year every five years, but there's always a lag. Another edge case that catches people off guard: real GDP doesn't account for quality improvements. If a smartphone in 2024 costs the same as one in 2019 but has four times the processing power, real GDP treats them as equal units of output. The price didn't change, so the quantity contribution is unchanged. The consumer surplus from the improvement is invisible in the data. This is a well-known limitation that even the BEA acknowledges in their methodology notes, but it rarely makes it into casual discussions of economic performance.
How To Calculate It Yourself
You don't need special software. Pull nominal GDP and the GDP deflator from your country's statistical office — in the US it's the Bureau of Economic Analysis, and the data is freely available in their National Income and Product Accounts tables. Divide nominal GDP by the deflator, multiply by 100, and you have real GDP. That's it. The BEA also publishes real GDP directly, so you can verify your math against their figure. If you want to calculate chained-dollar real GDP, which is what most developed economies use now instead of fixed-base-year methods, you need annual chain-type price indices. The BEA provides these in Table 1.1.6. Multiply the prior year's real GDP by the chain-type price index (divided by 100), then add the change in real final sales. It's a bit more involved but still straightforward arithmetic. The whole process takes about 15 minutes once you know where the tables live. One practical note: when comparing real GDP across countries, don't just grab the nominal figures and convert them using market exchange rates. That ignores differences in domestic price levels. Use purchasing power parity conversions instead, which the World Bank's International Comparison Program provides. The PPP-adjusted figures will look very different from simple exchange-rate conversions, especially for emerging markets.
What To Watch Out For
Staggered base years are the easiest trap. If you're comparing a country that updated its base year last year to one that hasn't updated since 2015, the growth rates aren't directly comparable. The newer methodology may capture informal sector activity differently, or weight services more heavily. Always check the revision history before making cross-country comparisons. Another thing: seasonal adjustment matters. Unadjusted real GDP can be wildly misleading during periods like holiday shopping seasons or agricultural harvest cycles. China's Q1 2020 real GDP drop looked catastrophic until you accounted for the Lunar New Year timing shifting production out of that quarter. Year-over-year comparisons are almost always more reliable than quarter-over-quarter raw figures. The biggest limitation remains what GDP doesn't measure. Real GDP growth in a country can be positive while median household income stagnates, while environmental degradation accelerates, while the informal economy expands faster than the formal sector. None of that shows up in the headline number. I've seen analysts treat real GDP as a proxy for prosperity and then get burned when the correlation broke down during structural transitions. It's a useful metric, not a comprehensive one.
If you need to track actual living standards, supplement real GDP per capita with disposable income data, wealth accounts, and subjective well-being surveys. No single number does the job alone, and anyone claiming otherwise is overselling the data.