Understanding the Basics
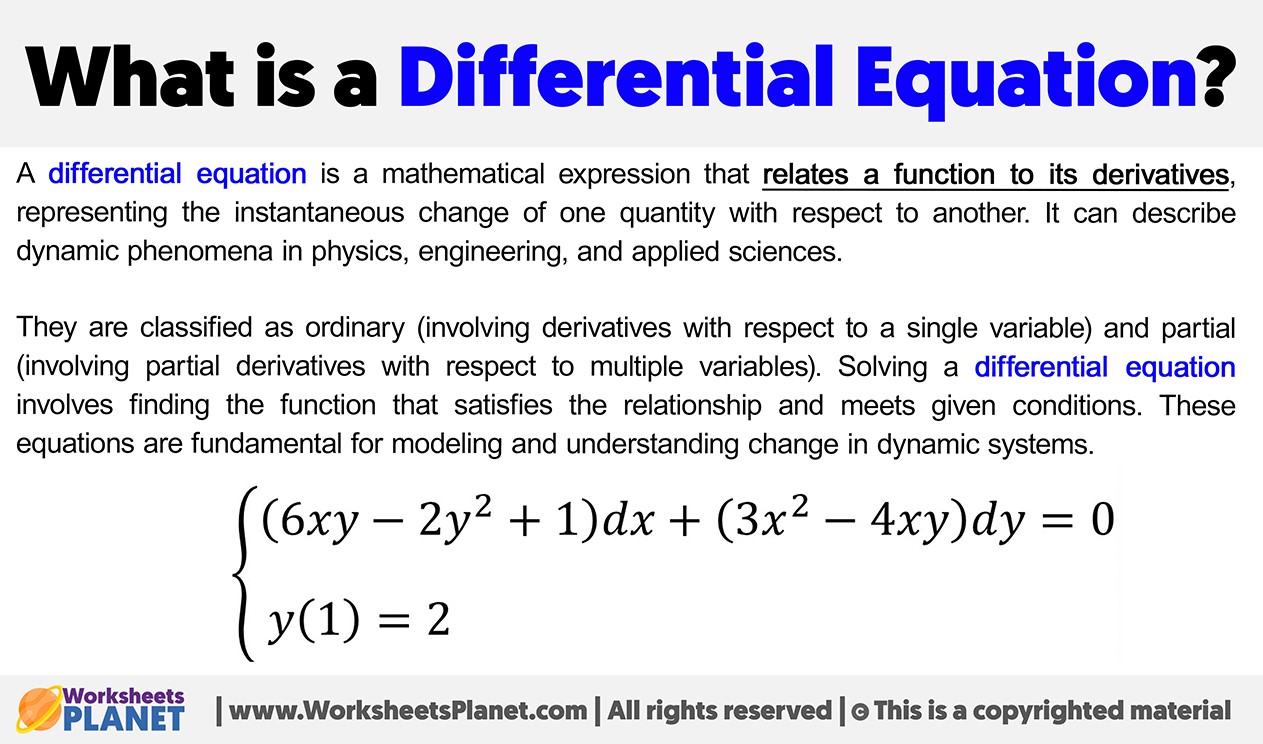
Differential equations are equations that involve derivatives. That is literally all they are. They relate a function to its rates of change. You use them whenever you need to describe how something changes over time or space. Physics, engineering, economics, biology — all of them rely on this stuff constantly. I remember back in grad school I was modeling heat transfer in a composite material. The equation I set up was a partial differential equation with non-homogeneous boundary conditions on an irregular geometry. Standard separation of variables didn't work because the domain wasn't clean. I ended up switching to a finite difference scheme on a mapped grid and wrote a quick MATLAB script to iterate until the residuals dropped below 1e-6. Took me three days instead of the two weeks I'd budgeted for an analytical approach that didn't exist.
What Is Differential Equations
Put simply, differential equations are a branch of mathematics that studies relationships between quantities and their rates of change. An ordinary differential equation (ODE) involves derivatives with respect to a single independent variable. A partial differential equation (PDE) involves derivatives with respect to multiple independent variables. That distinction matters because the solution techniques for each are wildly different. Consider a simple example: dy/dx = ky. This says the rate of change of y is proportional to y itself. The solution is y = Ce^(kx). Exponential growth or decay. You see this everywhere — population models, radioactive decay, compound interest. The equation is simple. The applications are not. Now look at something harder: d²y/dx² + 4y = sin(2x). This is a second-order linear non-homogeneous ODE. The homogeneous part gives you cos(2x) and sin(2x). But the non-homogeneous part is sin(2x), which already appears in the homogeneous solution. So you can't just guess A·sin(2x) as a particular solution. You have to multiply by x and try A·x·cos(2x) + B·x·sin(2x) instead. This is called resonance, and it catches a lot of students off guard.
The Laplace transform method handles this more elegantly. You transform the entire equation into algebraic form, solve for Y(s), then invert. But here is the thing nobody tells you upfront: Laplace transforms only work well for linear ODEs with constant coefficients and defined initial conditions. If your equation has variable coefficients or you are dealing with a boundary value problem rather than an initial value problem, you are better off using other techniques like series solutions or numerical integration.
Get the Full Details

How to Approach Solving Them
First step is always classification. Determine the order, linearity, and whether the equation is ordinary or partial. This determines your toolbox. A first-order separable ODE like dy/dx = x/y is trivial — just integrate both sides after separating variables. A first-order linear ODE like dy/dx + P(x)y = Q(x) requires an integrating factor e^(P(x)dx). Each class has its own standard procedure. For PDEs, the game changes entirely. The heat equation u/t = ²u and the wave equation ²u/t² = c²²u are the two most common ones you will encounter. Separation of variables works beautifully for rectangular domains with homogeneous boundary conditions. But the moment your geometry gets complicated — a circular membrane, an L-shaped plate, anything without clean symmetry — analytical methods start falling apart. I once spent two weeks trying to get an analytical solution for transient heat conduction in a cylinder with convective boundary conditions. The Bessel function series solution existed in theory but converged so slowly that I needed over a hundred terms to get reasonable accuracy near the surface. I switched to an implicit finite volume method and got the same result in seconds. Numerical methods are not a compromise here. They are the correct tool for most real-world problems.
Common Pitfalls
The biggest mistake beginners make is assuming every differential equation has a closed-form solution. It does not. Most do not. The Lotka-Volterra equations, the Navier-Stokes equations, the Schrödinger equation for anything beyond the hydrogen atom — none of these have general analytical solutions. You need numerical methods or approximations. Another frequent error is ignoring existence and uniqueness conditions. For a first-order ODE dy/dx = f(x,y), Picard-Lindelof theorem guarantees a unique solution near an initial point only if f and its partial derivative with respect to y are continuous in a neighborhood around that point. If you skip this check and your function has a discontinuity or a singularity near your initial condition, your solution might blow up or branch into multiple paths. I learned this the hard way when modeling a chemical reactor where the rate coefficient became undefined at a certain temperature threshold. The simulation produced garbage results that looked plausible until I traced back to the singularity. With numerical methods, stability is your real concern. The explicit Euler method is simple but conditionally stable. For stiff equations — where components of the solution vary on drastically different time scales — explicit methods require impossibly small time steps. You need implicit methods like backward differentiation formulas or Rosenbrock schemes. Most engineering simulation software uses these by default, but if you are rolling your own solver, picking the wrong method will waste hours of compute time and give you inaccurate results.
When Analytical Methods Fail
There are established numerical approaches for these cases. Finite difference methods discretize the domain and approximate derivatives with difference quotients. Finite element methods break the domain into elements and use variational formulations — better for irregular geometries and complex boundary conditions. Finite volume methods conserve quantities across control volumes, which makes them ideal for fluid dynamics and heat transfer problems where conservation laws are paramount. Software options range from MATLAB's built-in ode45 and pdepe functions to open-source alternatives like SciPy's integrate.odeint and FEniCS for finite element work. For quick prototyping, Mathematica or Maple can sometimes find closed-form solutions that you would never spot by hand. I keep a Mathematica license specifically for checking whether an equation I am wrestling with actually has an analytical solution before I spend days trying to derive one. The bottom line is that differential equations are not about memorizing solution techniques. They are about recognizing the structure of a problem and matching it to the right tool. Spend time understanding what type of equation you are dealing with before you start punching formulas. The hour you save on misclassification will multiply across the entire project.