Setting Up a Finance Journal Printable That Actually Sticks
A finance journal printable is simply a pre-formatted sheet you download and either print out or fill digitally to track your income, expenses, debts, and savings goals. They come in different shapes and sizes. Some are full monthly spreadsheets, some are debt payoff trackers, some are bare-bones daily logs. The whole category exists because standard note-taking apps and phone notes get unwieldy fast when you're trying to review actual numbers across multiple accounts. The core use case is visibility. You sit down once a week or once a month, pull your bank statements, and manually enter every transaction into the columns. The friction of writing it down forces you to notice things you would otherwise auto-skip. I spent two years using Mint before switching to a printed format, and the difference in spending awareness was jarring. The act of physically writing $47.32 next to "Grocery Store" registers differently than tapping a row in an app. I should be upfront about the biggest limitation right away. If you have more than three accounts or generate over 100 transactions a month, a finance journal printable will slow you down significantly. You'll spend 45 to 60 minutes on a monthly entry session. That's not a bug, it's a feature if your goal is mindfulness, but it's a dealbreaker if your goal is speed. In that case, a spreadsheet or an automation tool like YNAB or Plain Jane makes more sense. Printables work best for people managing one or two checking accounts and wanting to understand their actual cash flow.
Here is how I actually set mine up. I use a spiral notebook and download templates from budget template sites or create my own in Google Sheets, then print them out. The template I settle on every year has five sections: income, fixed expenses, variable expenses, debt payments, and a small savings check-in box. I do not add extra columns for categories like "entertainment" or "self-care." Those get lumped into variable expenses and I figure out the breakdown later if I need to. Over-categorizing a printable defeats the purpose of keeping it simple enough to maintain. One thing people miss with these templates is that the paper format gives you something digital systems can't replicate. You can circle a transaction, draw an arrow to a note on the next page, highlight a repeated vendor, and flip back through previous months without navigating menus or searching. I once caught a recurring duplicate charge on my credit card just by flipping through three months of printables side by side. The visual proximity of the data made the pattern obvious in a way that scrolling through an app never did. There is also a specific edge case that broke my first few attempts at consistency. I initially used A4-sized printables with narrow columns. After about six weeks, I ran out of space mid-page when entering expense details. The columns were too tight for anything beyond a one-word merchant name. My workaround was switching to A3 sheet halves. I print one month's worth across two pages side by side and fold the sheet in half, which gives me wider columns and still fits in a standard binder. This alone made the system sustainable for me over a full year.
Another counter-intuitive point: you do not need color coding to make a finance journal printable effective. I see a lot of templates pushing rainbow color coding for different expense categories. It looks nice in photos, but color coding on paper requires switching pens constantly, and most people end up using just two or three colors anyway. Stick to black ink for entries and use a highlighter only for totals or flagged items. The reduced friction makes it more likely you'll actually do the work. If you are looking to download something ready to use, there are a number of free resources available. Sites like Vertex42, The Budget Mom, and even Canva offer downloadable finance journal printable sheets in PDF or Excel format. You can also generate your own quickly in Google Sheets by setting up a simple table with date, description, amount, category, and running balance columns, then printing it directly. The advantage of building your own is that you control the column widths and can leave enough room for actual handwriting. The main failure mode with these systems is abandonment after three to four months. Not because the method is flawed, but because people treat the printable like a chore instead of a tool. The fix is brutal simplicity. Use one notebook. Use one template. Track only what matters for your situation. If you are carrying debt, add a payoff tracker on the front page. If you are trying to save for something specific, add a progress bar. Everything else is noise.
Get the Full Details
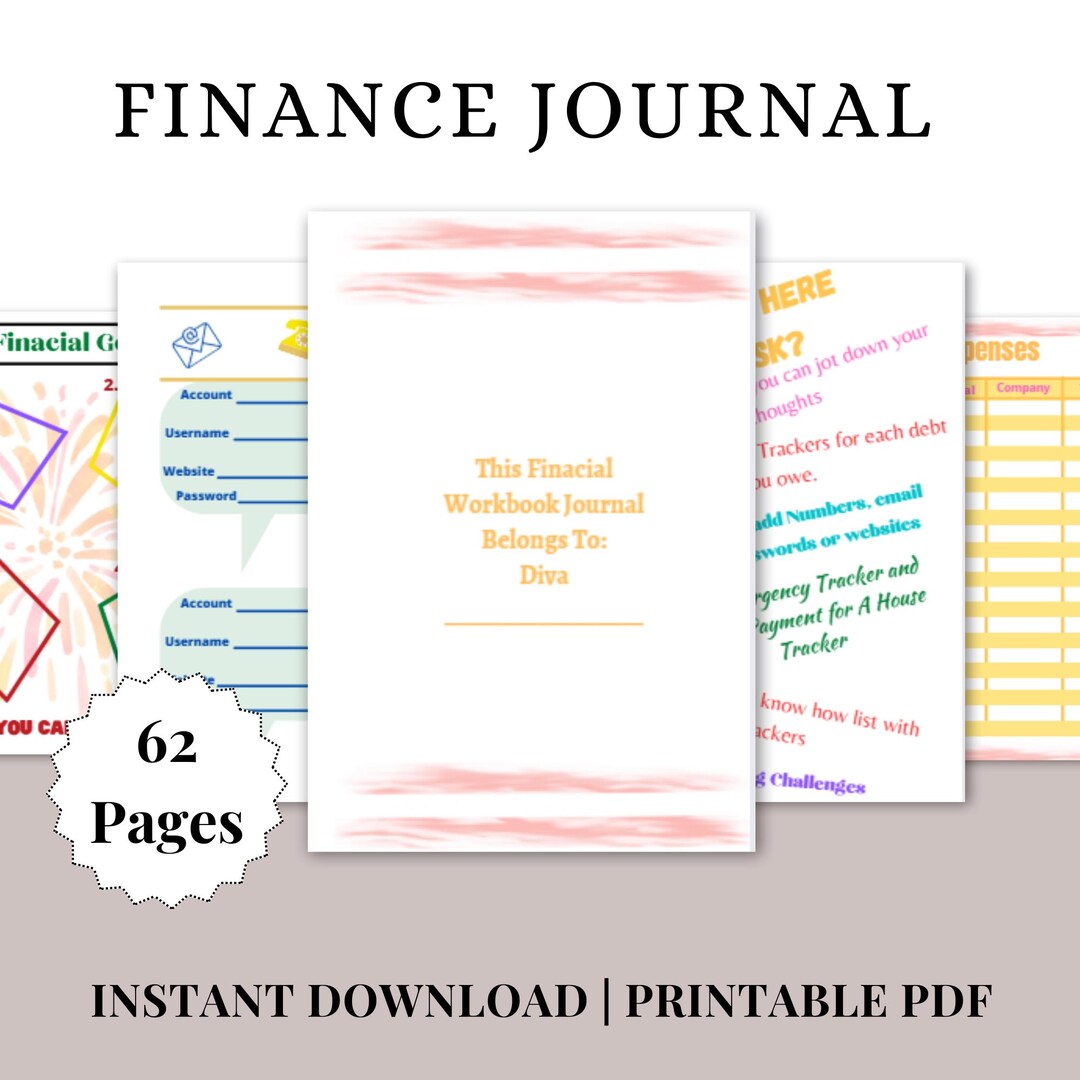
I also want to flag a practical detail that nobody mentions in tutorials. Paper degrades. Coffee gets spilled. Dogs chew the corner of the notebook. If you are serious about keeping records longer than a year, back up each monthly page to your phone before discarding the sheet. I take a quick photo with my phone camera and save it to a dedicated folder. It takes twelve seconds and saves you from having to reconstruct three months of data if the original gets ruined. I learned this after a leaky umbrella destroyed an entire quarter of entries. For the most part, a finance journal printable is what you make of it. It is not a magic budgeting system. It is a structured piece of paper that forces deliberate attention to your money. That slowness is the entire point. If you want speed, use an app. If you want awareness, print it out and sit down with it.