The PMT Function and Why It Matters in Real Work
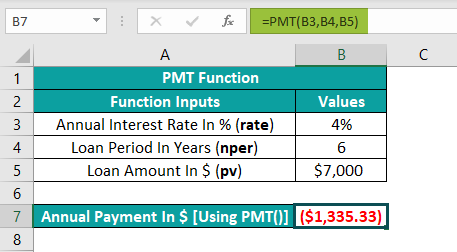
PMT stands for payment. It's one of those spreadsheet functions that shows up constantly in financial modeling, loan amortization schedules, and anything involving periodic cash flows. The function calculates a constant periodic payment for a loan or investment based on a fixed interest rate and a set number of periods. You pass in the rate, the number of periods, the present value, optionally the future value, and an option for whether payments happen at the beginning or end of the period. That's it. The Excel syntax looks like this: =PMT(rate, nper, pv, [fv], [type]). The rate is your periodic interest rate, nper is the total number of payment periods, and pv is the present value, or the principal amount. The fv argument is optional and defaults to zero, representing the remaining balance after the final payment. Type is also optional—1 means payments start at the beginning of each period, 0 means the end. Most loans use 0.
What Is Pmt In Finance
In practice, PMT is used whenever you need to figure out what a regular payment will be on a loan or annuity. Say you're taking out a $250,000 mortgage at 6.5% annual interest over 30 years. You divide the annual rate by 12 to get the monthly rate of about 0.5417%, multiply the years by 12 to get 360 periods, and plug everything in. The result comes out to roughly $1,582 per month. This number includes both principal and interest. It does not include taxes, insurance, or HOA fees, which people often forget when they first run the calculation and then get confused why their actual monthly bill is higher. I spent a lot of time in my early career building loan models for small business clients, and I've seen the same mistakes repeatedly. The most common one is mixing up annual and periodic rates. Someone will plug in the full 6.5% annual rate instead of dividing by 12, and their calculated payment will be wildly inflated. Another frequent error is entering the present value as a negative number when it should be positive, or vice versa. PMT follows sign convention rules—money you receive is positive, money you pay out is negative. If your numbers look wrong, check the signs first before second-guessing the formula. Here's something people don't always realize: the PMT function assumes a fixed interest rate and fixed payment amount throughout the entire term. That works fine for standard amortizing loans, but it breaks down completely for variable-rate mortgages, interest-only periods, balloon payments, or any loan where the terms change mid-life. I once modeled a construction loan that converted from interest-only during the build phase to fully amortizing afterward, and trying to force that into a single PMT call produced nonsense. The workaround was to split the model into two sections—one for the interest-only phase using a simple interest calculation, and another for the amortizing phase where the remaining balance becomes the new present value fed into PMT. That approach takes a bit more setup but produces accurate results that match the lender's actual amortization schedule.
There's also a subtle issue with how PMT handles the timing of payments relative to when interest accrues. If your loan states that payments are applied at the end of each period but your actual contract has payments due on the first day of the month, using type=1 versus type=0 will shift every payment by a full period. Over a 30-year loan, that difference can amount to hundreds of dollars in total interest paid. I learned this the hard way when a client's amortization schedule from the bank didn't match my spreadsheet, and it took two rounds of back-and-forth with the loan officer to figure out the discrepancy was purely a timing convention issue. One more thing worth noting: PMT returns a negative number by convention because it represents cash outflow. If you want it displayed as a positive value, wrap the whole thing in a negative sign or use the ABS function. This matters when you're building formulas that sum payments across multiple loans or compare them against income figures, because mixing positive and negative values will corrupt your totals. The PMT function isn't limited to loans. It shows up in pension calculations, lease agreements, annuity pricing, and even personal finance tools like savings goals. Any scenario where you need to determine the periodic amount required to reach a target balance or pay off a debt falls within PMT's scope. The mathematical foundation is the annuity formula, which has been around since the 1700s and hasn't really changed. What changes is the context, the data quality, and the mistakes people make plugging numbers into the wrong cells.
Get the Full Details

If you want to use PMT right now, it's built into Excel, Google Sheets, and most financial calculators. No download required. Just open a blank spreadsheet and type =PMT(0.05/12, 360, 200000) to see how it works with a sample loan. From there you can experiment with different rates and terms to build intuition about how each variable affects the payment amount.