The Balance Sheet Line That Most People Misinterpret
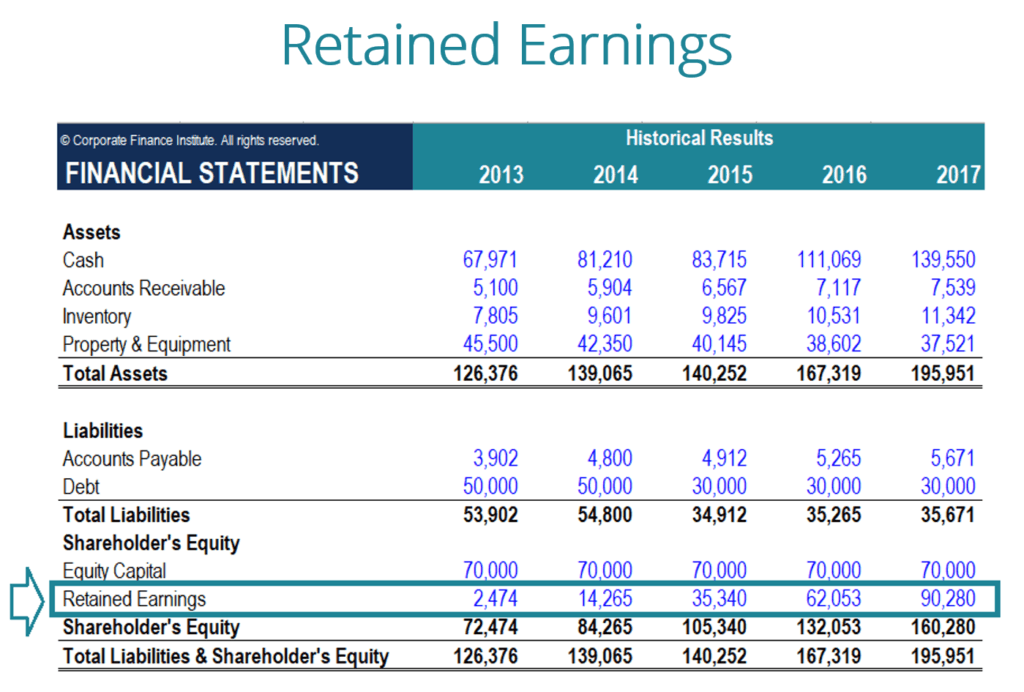
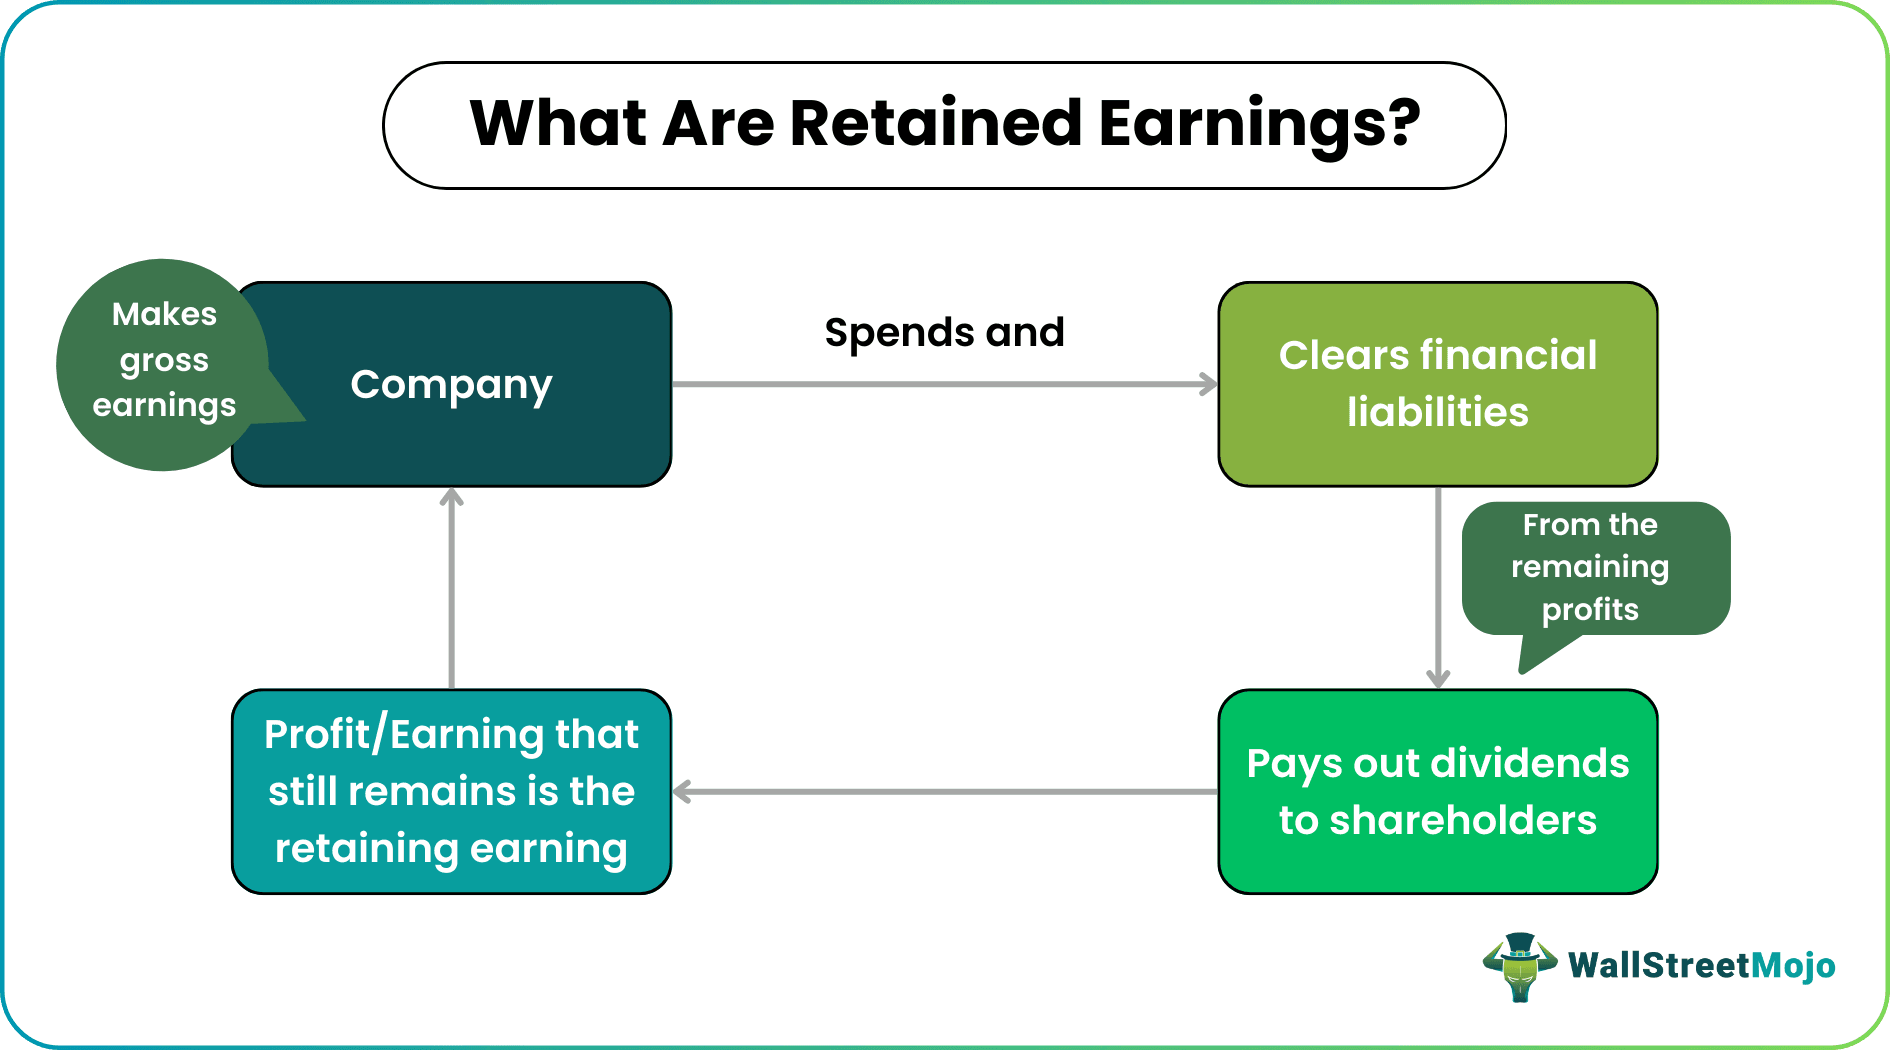
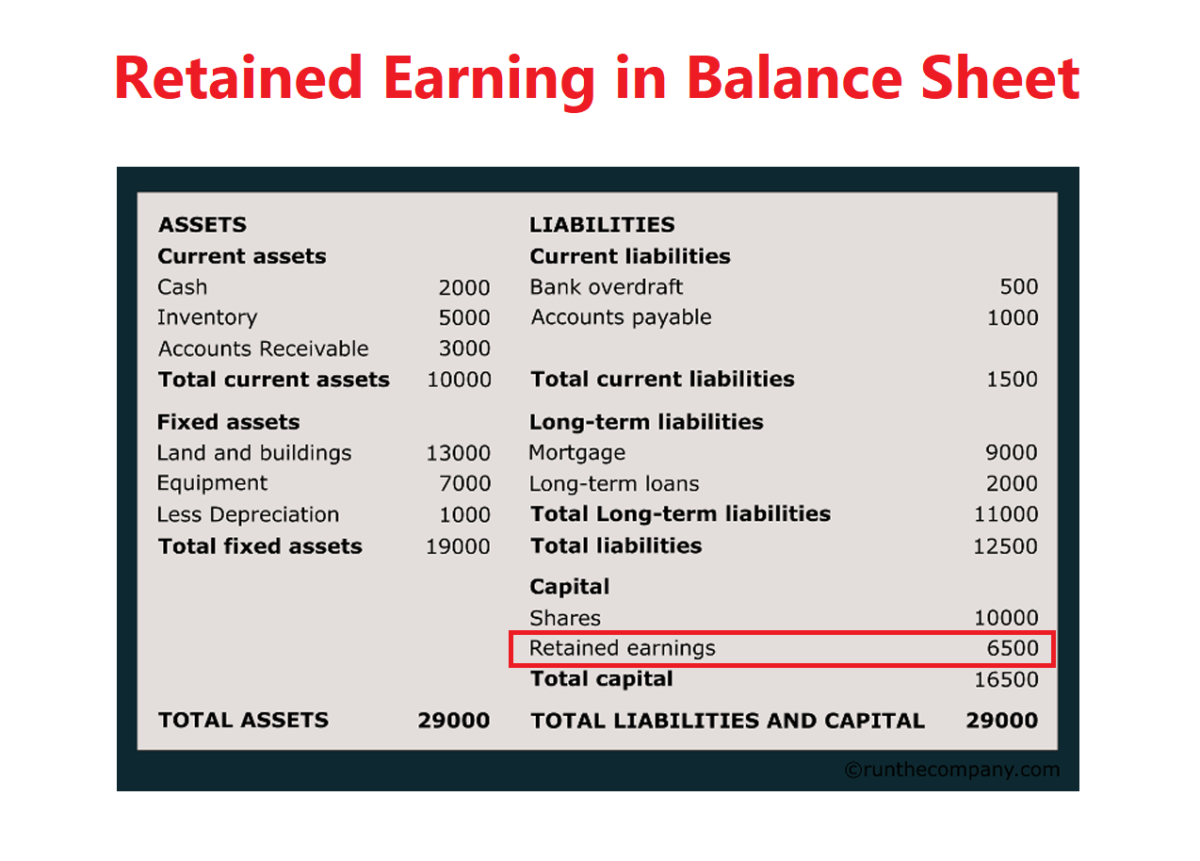
Retained earnings sit in the equity section of a balance sheet. They represent cumulative net income that a company has kept rather than distributing to shareholders as dividends. That is the textbook version. The practical version involves understanding what actually moved that number over time and why it sometimes looks wrong during financial review season.
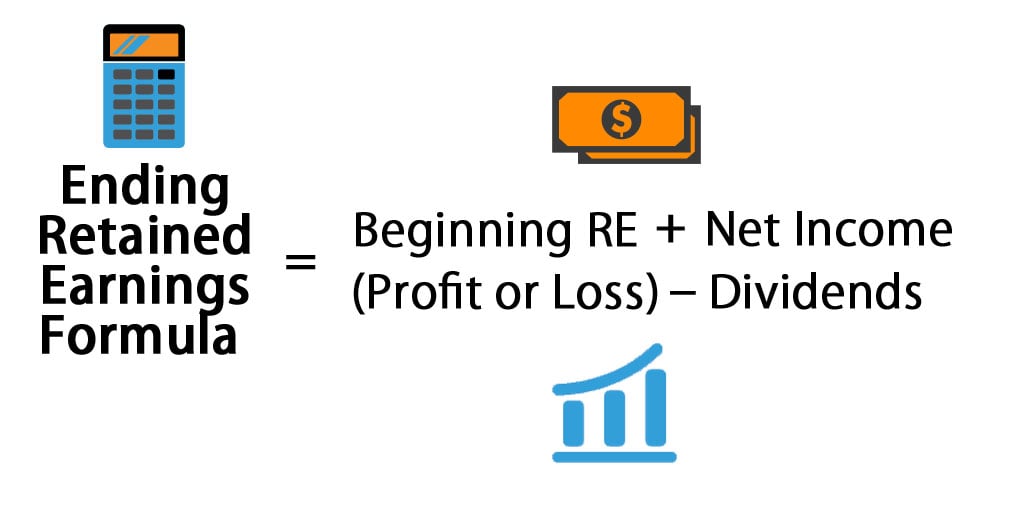
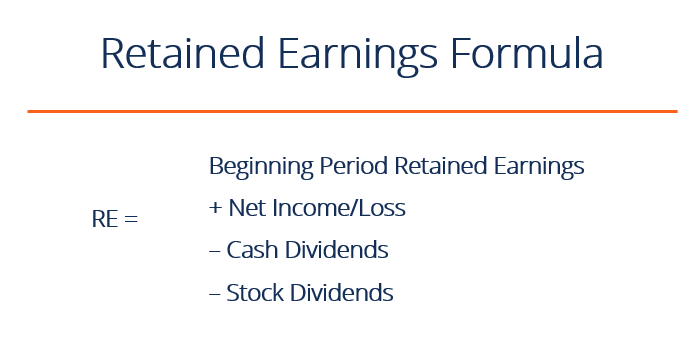
The calculation is straightforward. You take the beginning retained earnings balance, add net income or subtract net loss for the period, then subtract any dividends declared. The result becomes your ending retained earnings. Most accounting software handles this automatically, which means most people never actually see the computation happen. That is both a convenience and a risk.
What Is Retained Earnings and Why It Matters in Practice
I spent three years doing month-end closes for a mid-market manufacturing company before moving to advisory work. One November, our CFO asked me to explain why retained earnings dropped by $1.2 million even though we had reported positive net income for the quarter. I pulled the roll-forward and traced it back. We had a prior period adjustment from an inventory correction tied to a change in accounting estimate. The adjustment hit retained earnings directly, bypassing the income statement entirely. This is not something most introductory materials cover.
When you review retained earnings, always check for these movement categories. Prior period adjustments come through here rather than through current net income. Dividends, including stock dividends, reduce the balance. Net income adds to it. Treasury stock transactions can affect it indirectly through the broader equity reconciliation. A retained earnings statement should list each of these components clearly so anyone reading it understands what caused the change from one period to the next.
Here is something people miss. Retained earnings is not a cash account. A company can show large retained earnings and still have negative cash balance. I have seen this create serious problems during lending negotiations because bankers sometimes conflate the two. The retained earnings figure reflects accounting profit over time, not liquidity. When I prepare financial packages for small business owners, I always include a one-line note clarifying this distinction. It prevents follow-up questions that waste time and slow down closing processes.
Another counter-intuitive point involves negative retained earnings. When a company accumulates more losses than profits over its life, it reports this as an accumulated deficit. Some business owners panic when they see a negative number in equity. In early-stage technology companies especially, this is normal and expected. Investors understand that heavy upfront investment creates temporary negative retained earnings. What matters is whether the company has a credible path to profitability, not the raw sign of the equity line item.
I ran into an edge case with a software company where we were capitalizing certain development costs under ASC 350-40. The capitalization policy affected net income, which flowed into retained earnings. Our auditor wanted us to expense those costs instead, which would have reduced retained earnings by about $400,000. We negotiated a compromise where we documented the capitalization criteria more thoroughly and provided amortization schedules. The retained earnings balance stayed higher, but we had to add disclosure notes. This took approximately two weeks of back-and-forth with the audit team. The key takeaway is that accounting policy choices directly impact retained earnings, and those choices are where disputes often surface during audits.
Why this concept gets confusing is partly because the name suggests the money is sitting somewhere reserved and untouched. It is not. The number is purely a accounting construct. The actual cash may have been spent on equipment, paid out as dividends, or tied up in receivables. The retained earnings line is an equity checkpoint, not a bank account balance.
Small business owners using QuickBooks or Xero should know that the retained earnings figure updates automatically at period close. However, if you have ever made manual journal entries to equity accounts or corrected prior period errors, you need to understand where those entries land. An incorrectly posted journal entry can distort retained earnings without triggering any alerts in most systems. I always run a trial balance with detail on equity accounts before finalizing any close. This catches misposts that would otherwise show up later as unexplained swings in the retained earnings line.
The real limitation of relying solely on retained earnings as a health indicator is that it masks a lot of activity. A steadily growing retained earnings balance could mean the business is profitable, or it could mean the business is not investing in growth and just accumulating accounting profit. Both scenarios look identical on a balance sheet. You need to look at returns on equity, reinvestment rates, and dividend policy to understand what is actually happening.
If you want to trace the full picture, pull the statement of retained earnings or the statement of stockholders equity. These documents break down every transaction that moved the number. They are usually required for external reporting but often skipped in internal management packs. I recommend building a simple template that shows beginning balance, net income, dividends, prior period adjustments, and ending balance. It takes about ten minutes to produce after you already have your trial balance ready, and it saves significant time when someone asks you to explain a balance sheet fluctuation.
Gallery What Is Retained Earnings
What is Retained earnings 2026
Retained Earnings - What Is It, Examples, vs Net Income
What Is Retained Capital at William Rohde blog
What Are Retained Earnings Guide Formula Examples 566x546
Unique Info About Calculate Retained Earnings On Balance Sheet Financial Statement | Alayneabrahams