Scarcity in Macroeconomics: The Real Deal
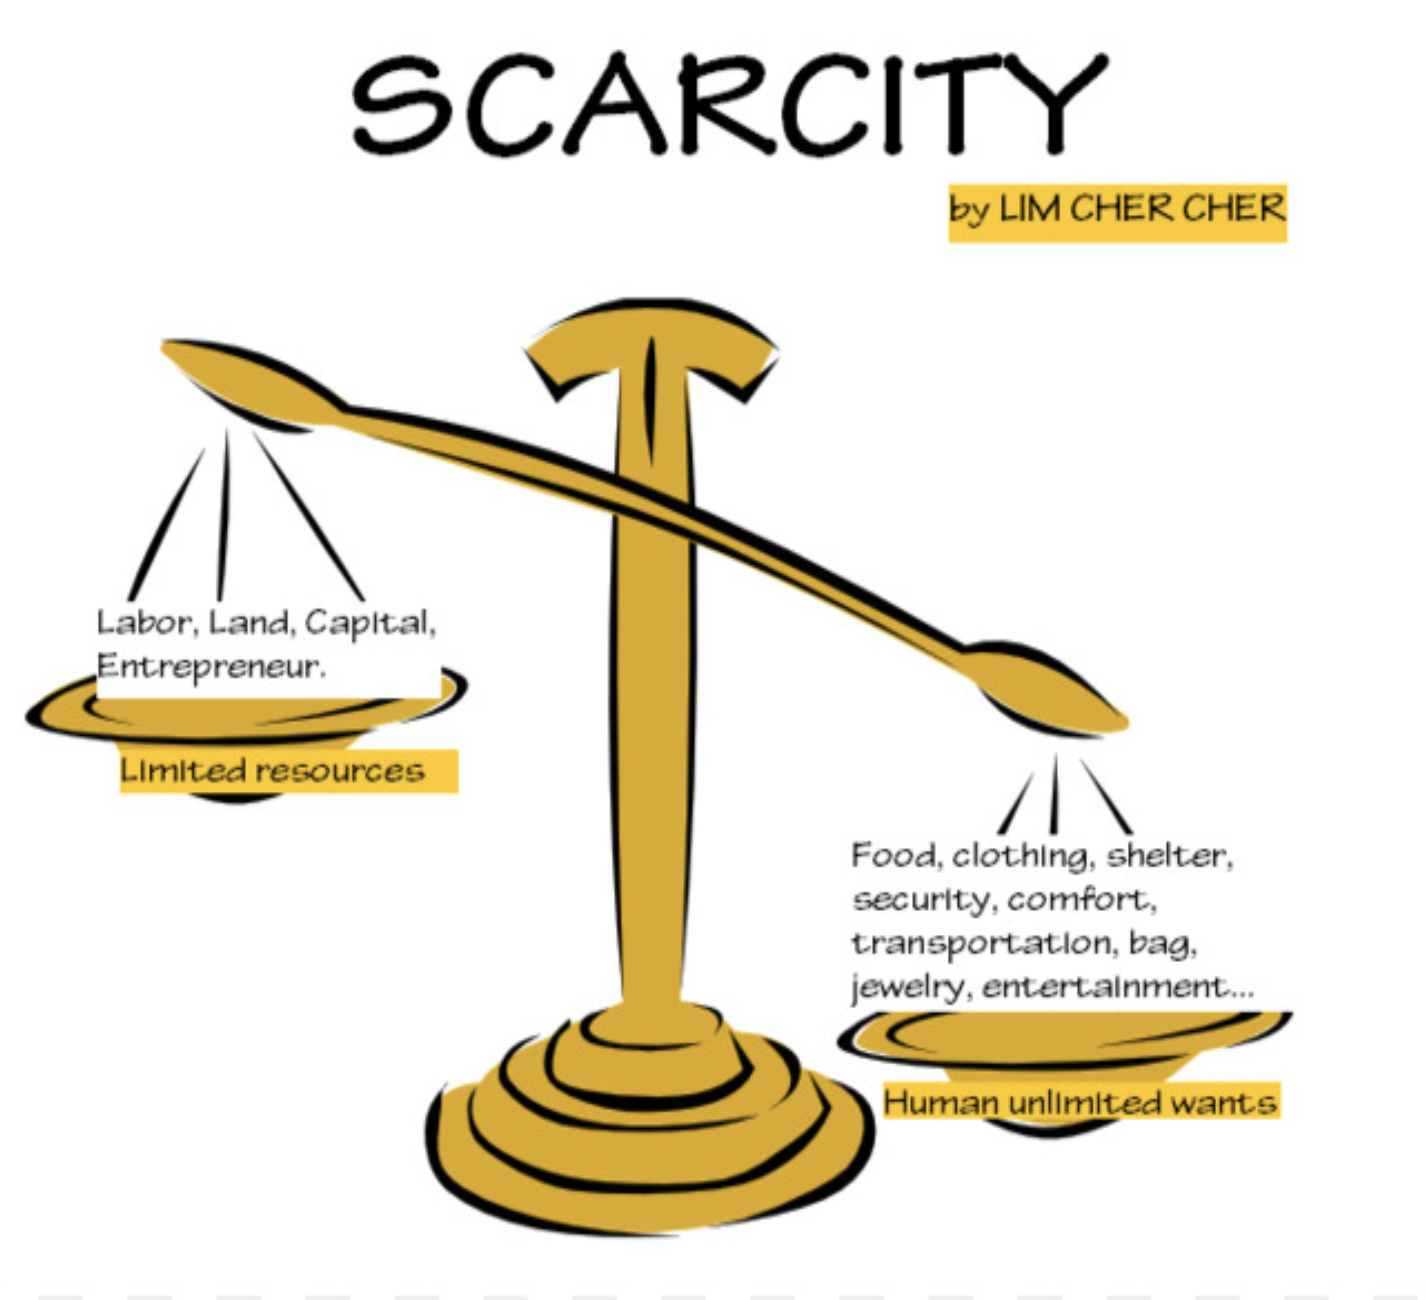
Most people learn about scarcity in their first economics class and then immediately forget how deep the concept actually goes. Scarcity simply means that resources are while wants are not. That's it. But in macroeconomics, this basic truth becomes the foundation for everything from economic growth models to policy decisions that affect millions of people. When you're looking at an entire economy, scarcity isn't just about one person choosing between buying coffee or tea. It's about a nation deciding whether to invest in infrastructure or education, and understanding what gets sacrificed in either case. In macro, scarcity shows up as constraints on production. An economy can only produce so much given its available labor, capital, land, and technology. The Production Possibilities Frontier (PPF) is the standard tool for visualizing this, and most textbooks use it to introduce opportunity cost. I've seen students nail the PPF graph but completely miss what happens when you try to apply it to real policy. Here's what the models leave out: scarcity isn't always about running out of physical things. Sometimes it's about institutions. I worked with a development team analyzing a Southeast Asian country that had plenty of arable land and a growing labor force, but their agricultural productivity was stuck. The constraint wasn't resources. It was property rights enforcement and credit access. Farmers couldn't invest in better equipment because they couldn't get loans, and banks wouldn't lend because land titles were unreliable. That's scarcity too, and it's way harder to fix than finding more of something.
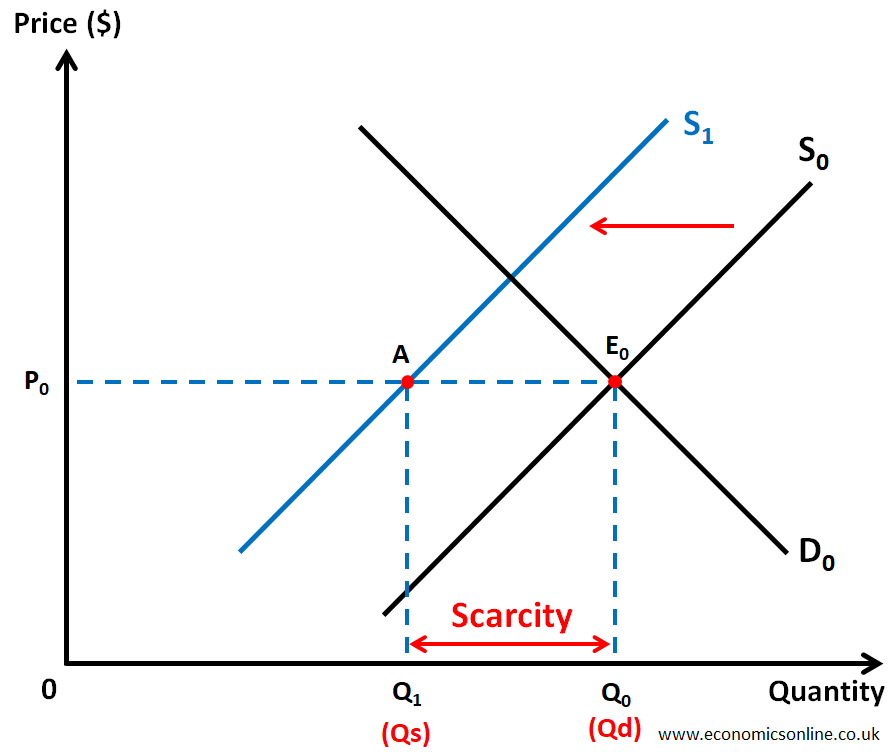
The standard definition covers the basics well enough. Scarcity means limited resources facing unlimited wants, which forces choices, which creates opportunity cost. But the interesting part is how scarcity changes over time and across different types of economies. A developed nation facing scarcity might be dealing with aging infrastructure and a shrinking workforce. A developing nation might face scarcity of basic capital goods and institutional capacity. The mechanism is the same—constraints forcing trade-offs—but the nature of the constraints looks very different. One thing beginners consistently get wrong is thinking that economic growth eliminates scarcity. It doesn't. Growth shifts the PPF outward, which means the economy can produce more of everything. But the frontier keeps moving, and wants keep expanding too. We've been growing for centuries and scarcity hasn't gone away. It just changes shape. When oil becomes scarce, we develop alternatives. When those alternatives hit their own limits, the constraint shifts again. This is why the concept matters more now than ever. The other common mistake is treating scarcity as purely a supply-side problem. Demand-side scarcity exists too, and it shows up in places like liquidity traps or when income distribution is so unequal that most people simply can't afford what the economy produces. Japan in the 1990s and early 2000s is a good example. The country had the technology, the labor force, and the capital. What it lacked was effective demand, which is a different kind of scarcity that Keynesian models try to address. You can't solve a demand-side scarcity problem with more factories.
If you're working with this concept practically, here's what I've found useful. When analyzing any economy's constraints, start by identifying which factor of production is the binding one. Is it labor? Capital? Natural resources? Technology? Institutional quality? The answer determines what kind of policy intervention would actually move the needle. Throwing money at a labor-scarcity problem usually just causes inflation. Investing in education and immigration policy addresses the actual constraint. The diagnostic step matters more than the solution. I once spent weeks trying to understand why a particular Latin American country's growth model kept failing. The standard advice was always the same: invest more, save more, open up to trade. But the data kept pointing somewhere else. The binding constraint was human capital quality, not quantity. Workers were numerous but poorly educated, which meant even heavy capital investment yielded diminishing returns. The workaround was focusing on targeted vocational training aligned with existing industry needs rather than general education spending. It's slower and less glamorous than building a new highway, but it addresses the real scarcity. The takeaways are straightforward if you think about them carefully. Scarcity is unavoidable and permanent in macroeconomics. The goal isn't to eliminate it but to understand what form it takes in any given situation and allocate resources accordingly. Opportunity cost is always present, even when it's not obvious. And the type of scarcity matters enormously for policy design. Mismanaging a capital constraint is qualitatively different from mismanaging a technological one, even though both are scarcity problems.
Get the Full Details