What Should Cost Analysis Actually Looks Like in Practice
Most people hear "should cost analysis" and immediately think it's some kind of sophisticated pricing algorithm or a fancy procurement textbook concept. It's not. It's essentially the process of breaking a product or service down into its fundamental components and estimating what each piece should reasonably cost to produce, then comparing that to what you're actually being charged. That's the whole thing. The rest is just methodology and how much effort you want to put into it.
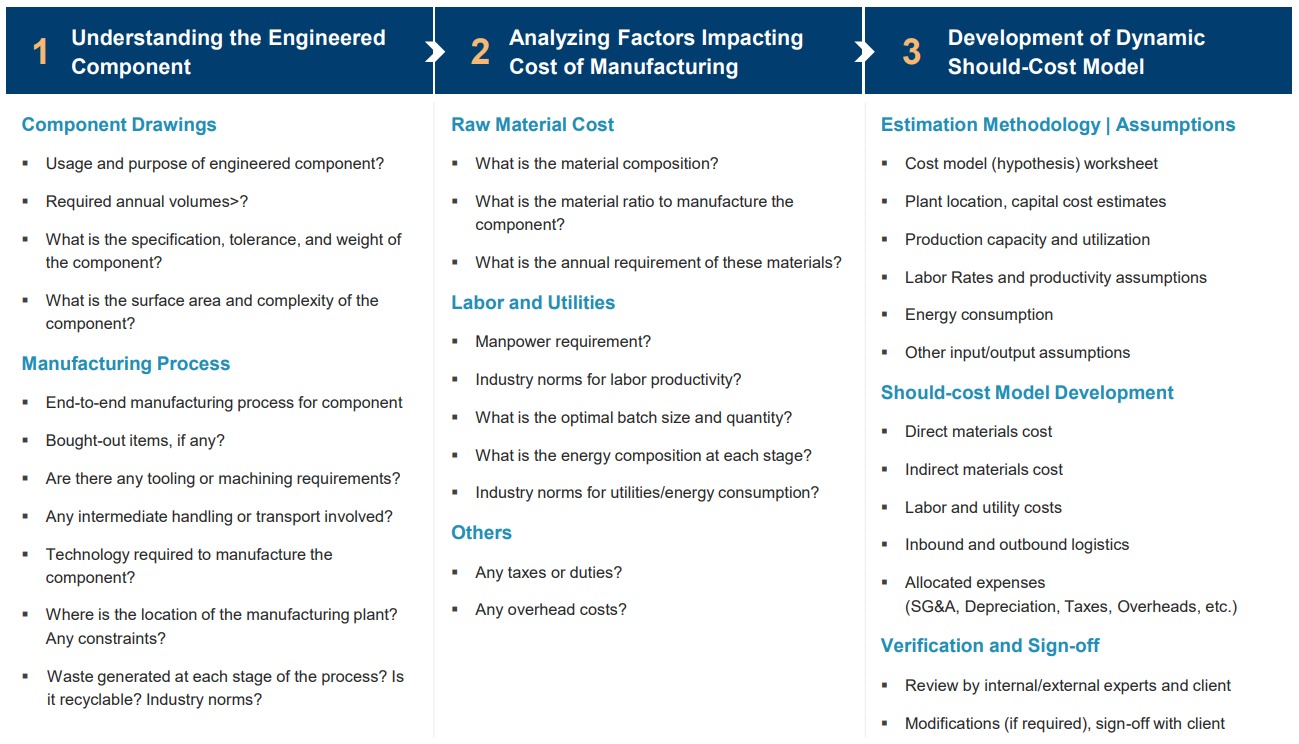
The core mechanics are straightforward. You take a Bill of Materials or a scope of work, identify every material, labor hour, overhead factor, and margin layer involved, research current market rates for each component, and build a bottom-up model. The difference between your calculated cost and the supplier's quote becomes your negotiation leverage. If the analysis shows a part should cost $12 and they're charging $19, you have a conversation. If they're charging $11, you know something else is going on.
Here's the practical workflow most people actually use:
Start with whatever documentation you can get from the supplier. A detailed quote helps, but even a vague one is enough to begin. Reverse-engineer the cost structure by asking specific questions about material composition, manufacturing processes, volume tiers, and shipping terms. Cross-reference those inputs against public commodity pricing databases, industry benchmark reports, and supplier cost models where available. Some people build spreadsheets from scratch. Others use dedicated should-cost modeling software. Both approaches work if the inputs are solid.
What Is Should Cost Analysis and Why It Keeps Getting Overcomplicated
I see teams spend weeks building elaborate should-cost models when a rough order-of-magnitude estimate would have been sufficient for their decision. The trap is treating should cost analysis as a precision exercise when it's usually a directional one. Getting within 10 to 15 percent of true cost is typically good enough for most sourcing decisions. Obsessing over perfect accuracy on every line item burns time and rarely changes the outcome.
The technique has real limitations that don't get discussed enough. It breaks down when you're dealing with highly proprietary processes where the supplier guards their manufacturing secrets. It becomes unreliable for custom work where there's no established market benchmark to reference. And it can actually harm negotiations if you present an overly precise cost model that turns out to be wrong, because then the supplier can pick apart your assumptions and destroy your credibility for future conversations.
I ran into this exact problem a few years back working on a custom enclosures project. The supplier quoted $47 per unit and my should-cost model came back at $38 based on aluminum extrusion rates, CNC machining hours, and powder coating costs from several publicly available databases. I walked into the negotiation ready to hammer them down. They pulled out their actual cost breakdown showing the $47 was driven partly by a specialized anodizing treatment I hadn't accounted for, plus a low yield rate on their first articles that I couldn't have known about without spending weeks on their factory floor. The real should-cost was closer to $44. I had lost credibility by being confidently wrong on the details, and it took three more supplier meetings to rebuild trust. The workaround was simple: I started treating every should-cost model as a living document, explicitly noting which assumptions I was uncertain about, and using those uncertainty ranges as discussion points rather than ammunition.
Common Pitfalls That Make Should Cost Models Worthless
Using stale data is the fastest way to produce a bad model. Commodity prices shift, labor rates change, and exchange rates move. A should-cost analysis built from data that's six months old will quietly mislead you. I check my source dates before running any analysis, and if anything is older than ninety days I flag it and either find fresher data or widen my confidence interval.
Another trap is ignoring indirect costs. People focus on materials and direct labor and forget that overhead allocation, quality inspection time, tooling amortization, and inventory carrying costs often account for 20 to 30 percent of total cost. Leave those out and your model will consistently undershoot. The fix is to build in standard overhead rates from industry benchmarks and apply them to each cost category rather than trying to calculate every overhead line item individually.
Volume assumptions matter more than most modelers admit. A should-cost model built around 10,000 units per year will look very different from one built around 100,000. Fixed costs spread differently, material pricing tiers change, and setup time per unit drops. I always run at least two scenarios, one at the current volume and one at the projected volume after negotiation, because the supplier will likely increase volume if they accept a lower price.
When Should Cost Analysis Is the Right Tool and When It Isn't
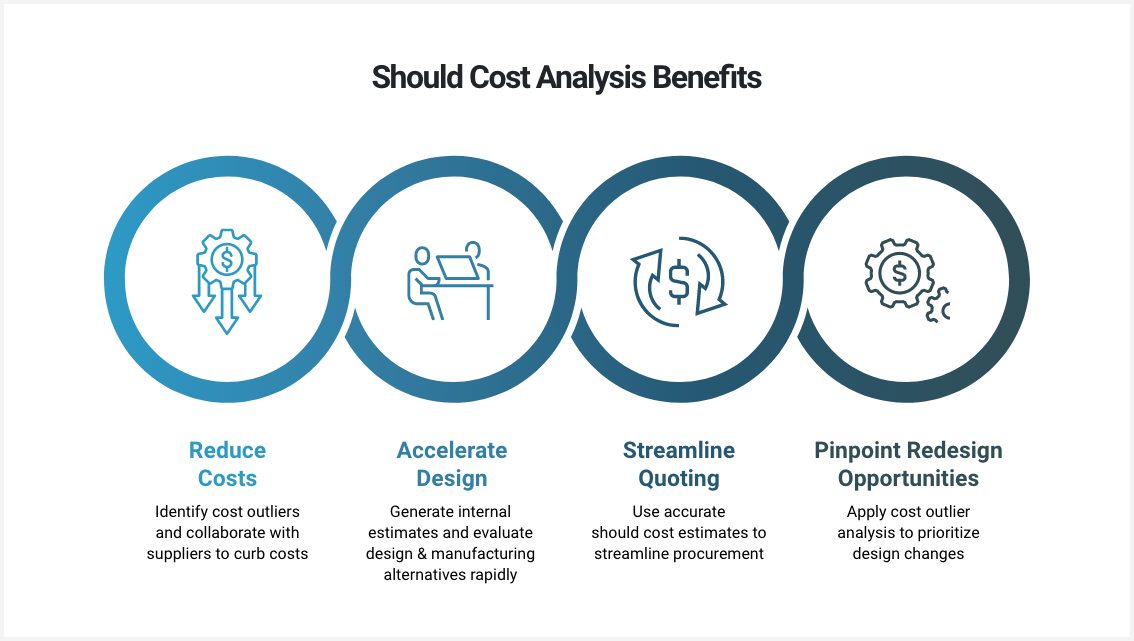
You should use this approach when you're procuring high-value items, negotiating long-term contracts, dealing with sole-source suppliers where competitive pressure isn't enough, or evaluating whether to make versus buy. It becomes less useful for low-value purchasing where the transaction cost of building the analysis exceeds the potential savings. You also shouldn't rely on it when the cost structure is genuinely unknowable, like custom R&D work with no comparable benchmarks or heavily regulated products where pricing is driven by compliance rather than production economics.
The most practical version of this analysis for most teams doesn't require expensive software or full-time analysts. A well-built spreadsheet with transparent assumptions, regularly updated source data, and explicit confidence intervals on uncertain line items will outperform most off-the-shelf tools for typical sourcing decisions. The skill isn't in the calculation itself. It's in knowing which assumptions to scrutinize and which to accept as reasonable estimates.