So you need to know what Surest is
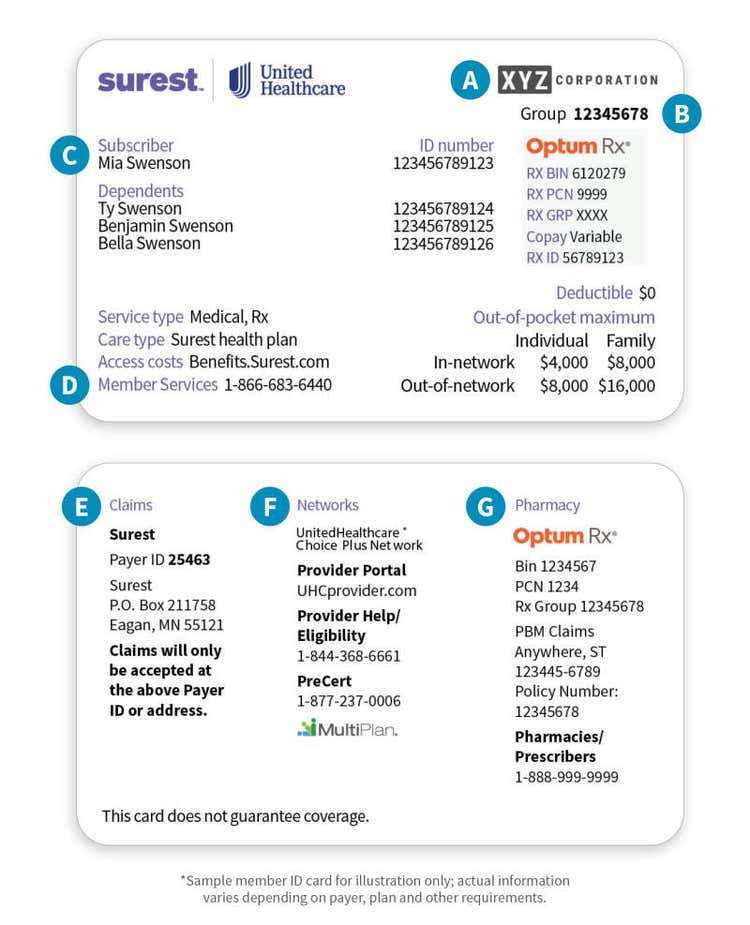
Surest is a health insurance company that sells plans through the ACA marketplaces. It's one of the many carriers you'll see when you shop on Healthcare.gov or a state-based exchange. They offer Bronze, Silver, and Gold tier plans across a handful of states. They're not the biggest name out there, but they're legitimate and ACA-compliant. It was launched as part of the broader effort to bring more budget-conscious options into the individual marketplace. Surest is owned by Centene Corporation, which is one of the larger Medicaid and marketplace insurers in the country. That matters because Centene's infrastructure gives Surest some backend support that a small startup wouldn't have, but it also means Surest operates within Centene's network and plan design rules. The plans themselves are straightforward. They're metal-tiered, they cover the essential health benefits, and they're available to anyone who qualifies through the marketplace. No short-term limited-duration products. No substandard plans. Just standard ACA-compliant coverage.
I've dealt with a bunch of these companies over the years, and Surest sits somewhere in the middle of the quality spectrum. Their premiums tend to run competitive, especially on the Silver tier if you're eligible for cost-sharing reductions. Their provider networks are narrower than something like Blue Cross, which is a real factor if you have a specialist you depend on.
How the enrollment process actually works
You go to your state's exchange or Healthcare.gov, enter your zip code and income, and then filter or sort by carrier. Surest will show up if they operate in your area. You pick a plan, answer the screening questions, and pick a start date. That's the whole thing. It usually takes about 10 to 20 minutes if you have your information ready. The trick is knowing what to look for before you click submit. The premium number on the screen isn't what you'll actually pay if you qualify for subsidies. You need to check the estimated monthly cost after any advance premium tax credit or cost-sharing reduction is applied. I've seen people get surprised when their "selected" plan suddenly costs $90 a month instead of $280 after the subsidy applies. The exchange will show both numbers, but only if you actually read them. Another thing that trips people up is the difference between the plan's deductible and the total out-of-pocket maximum. Surest's Silver plans often have moderate deductibles, but the out-of-pocket max is capped by federal law at a set amount based on whether you're individual or family. That cap is a hard number the insurance company can't exceed, so you can use it as a quick sanity check.
Get the Full Details

What the plan network actually looks like
This is where things get real. Surest uses narrow networks in most markets. In California, for example, they partner with specific hospital systems and physician groups rather than casting a wide net. In Wisconsin, their network is built around certain health systems and independent group practices. The exact provider list changes by county and by plan year. Before you enroll, you need to look up your doctors and your pharmacy on Surest's provider directory. Not the general Centene one. The Surest-specific directory. I learned this the hard way when I was helping someone get enrolled and we assumed their primary care doctor was in-network because he was listed under the parent company's directory. He wasn't on the Surest plan. She got billed at out-of-network rates for a follow-up visit. Took three months and two escalation calls to get it reversed, and even then the claim was only partially adjusted. The workaround is simple and it saves you a lot of headaches. Call the doctor's office directly and ask them to confirm they accept the specific Surest plan you're looking at. Give them the plan name and the plan ID number. Don't rely on the directory alone. Directories get updated on schedules, and there's always a lag between when a provider leaves a network and when the directory reflects it.
Common pitfalls people run into
The first one is assuming that Surest covers everything you expect just because it's an ACA plan. Essential health benefits is a broad category. Prenatal care is required. Mental health services are required. Prescription drugs are required. But "required" doesn't mean "no limitations." Prior authorization rules, step therapy protocols, and formulary tiers still apply. If you're on a specific medication, check the formulary for the exact Surest plan before you enroll. I've seen people pick the cheapest plan only to find their maintenance medication was on the highest tier with a $150 monthly copay instead of the $30 it was under their old plan. The second pitfall is not understanding how cost-sharing reductions work. If your income falls between 100% and 250% of the federal poverty level, you might qualify for CSR. This bumps your Silver plan up to an effective Gold-level cost-sharing structure without changing the premium. Surest offers this pathway, and it's one of the most valuable options on the marketplace. But you have to meet the income threshold and you have to select a Silver plan. If you pick Bronze or Gold, CSR doesn't apply and you lose the benefit entirely. The third issue is customer service responsiveness. Surest is a smaller brand, which means their call volumes are lower but so is their staffing relative to the big carriers. When claims problems come up, you're more likely to get transferred multiple times than you would with a larger company. It's not terrible, but it's slower. Keep good records of every call, including the date, time, and the name of whoever you spoke to. It sounds paranoid, but it's the single most useful thing you can do when you need to escalate something later.
When Surest makes sense and when it doesn't
Surest is a solid choice if you're healthy, you don't have a long list of specialists you visit regularly, and you want a lower premium. Their Bronze and Silver plans are priced competitively, and for people who mostly use primary care and urgent care, the savings add up. If you're expecting a baby or you have a chronic condition requiring frequent specialist visits, you need to scrutinize the network more carefully before committing. A lower premium doesn't matter much if your regular doctors aren't in it. If Surest isn't available in your area or their network doesn't include your providers, the alternatives depend on your state. UnitedHealthcare, Aetna, and Cigna are the bigger names with wider networks but usually higher premiums. Regionally, there are often local Blue Cross affiliates or community health alliances that might serve the same population with different network characteristics. Shop around. Don't auto-select the first plan you see.
The practical takeaway
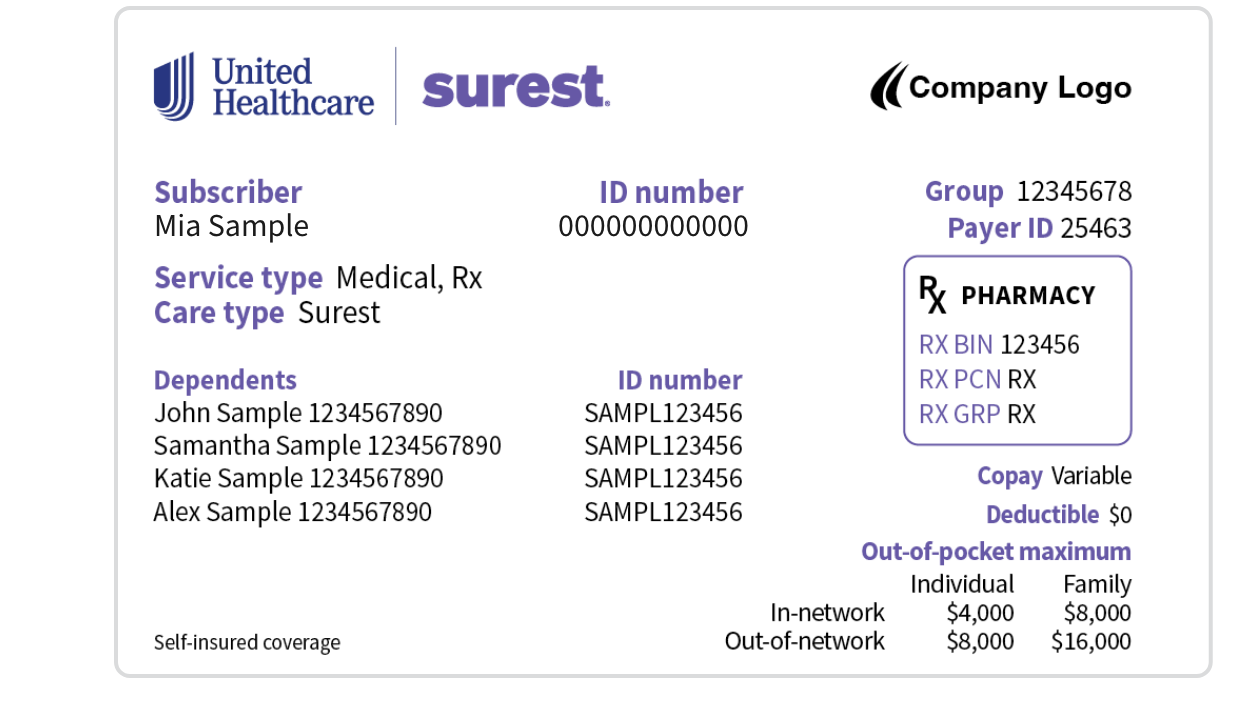
Pick your plan based on your doctors and your expected medical needs, not just the premium. Verify your providers in the Surest network before you enroll. Check the formulary if you take prescription medication. Look at the out-of-pocket maximum and compare it across the available plans. And keep a folder with your plan documents, member ID, and a log of any customer service calls. You'll thank yourself later if anything goes wrong.