Life Expectancy Is Just An Average, And That Is The Whole Problem
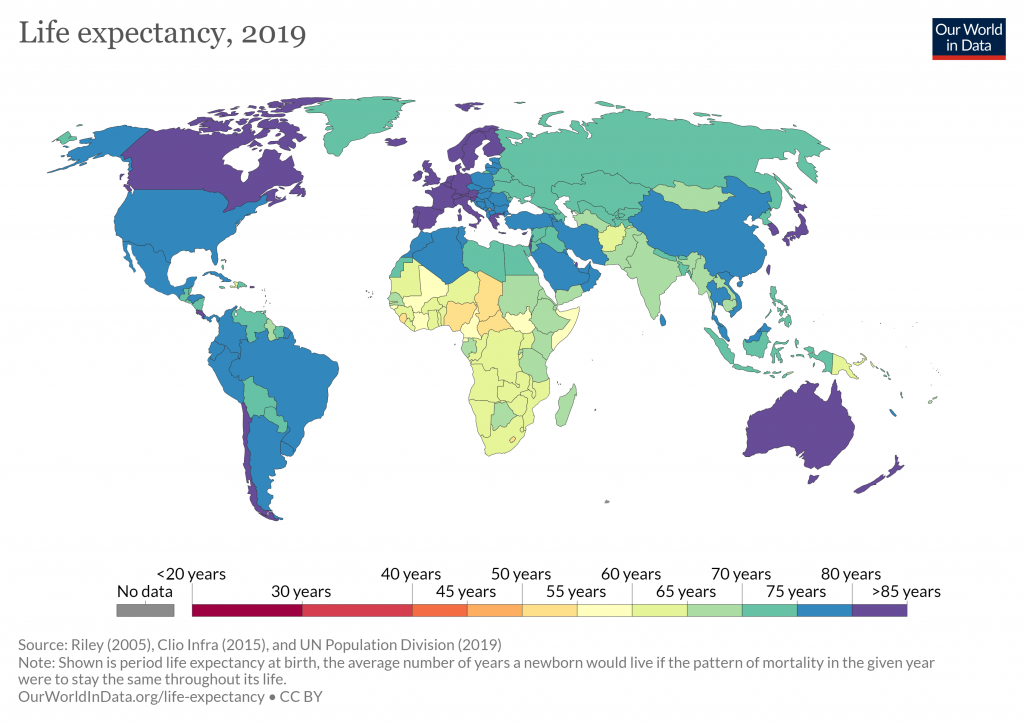
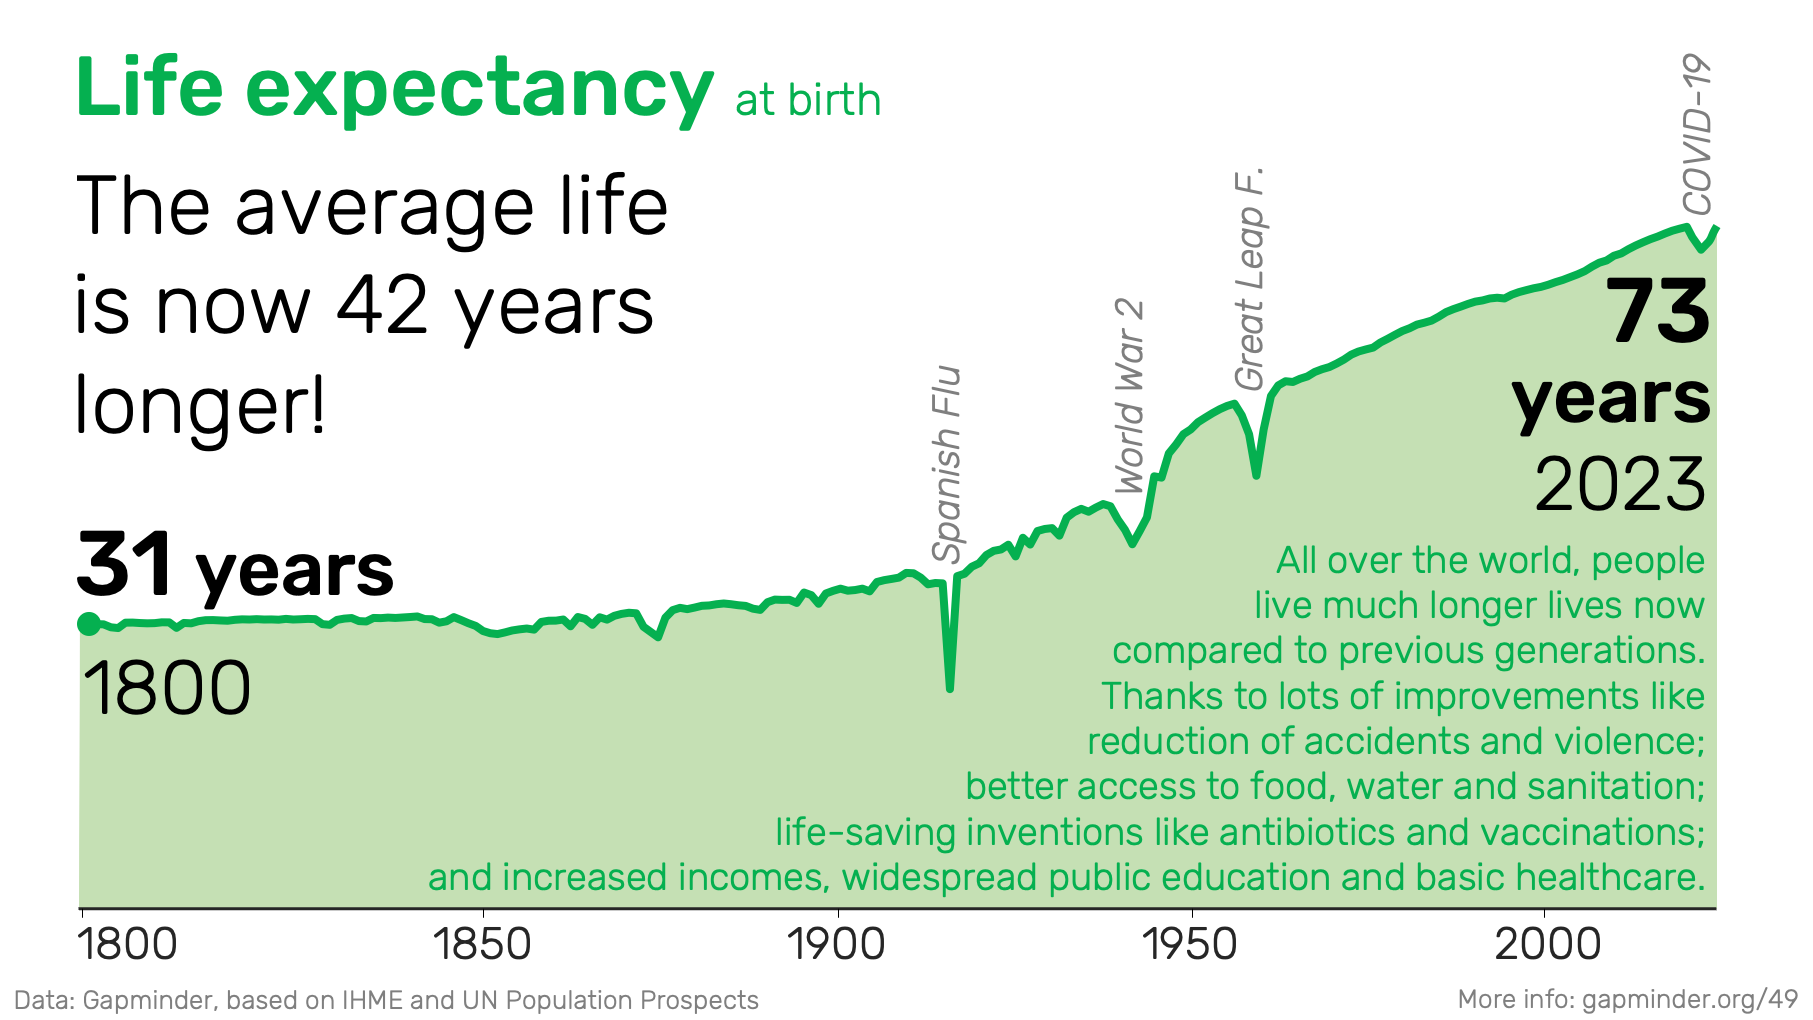
Most people treat life expectancy as if it's a prediction for any individual person. It is not. It is a statistical snapshot calculated from current death rates across a population. If you are looking at a single life expectancy number and treating it like a deadline, you are already working with bad data. The average life expectancy globally sits somewhere around 73 years as of recent World Health Organization data, but that number moves slowly and depends entirely on which calculator you use. Period. The method matters more than the final digit. Standard life tables take age-specific death rates from a given year and construct a hypothetical cohort that experiences those rates throughout its entire life. That cohort's average age at death becomes the life expectancy for that year. I spent several years working with actuarial models for insurance products, and one of the first things I learned is that these tables are backward-looking projections disguised as current facts. They assume today's mortality rates stay constant. They do not. This is where most people get tripped up, and it is worth understanding before you make any decisions based on a single number.
Why The Number Changes Depending On Who Calculates It
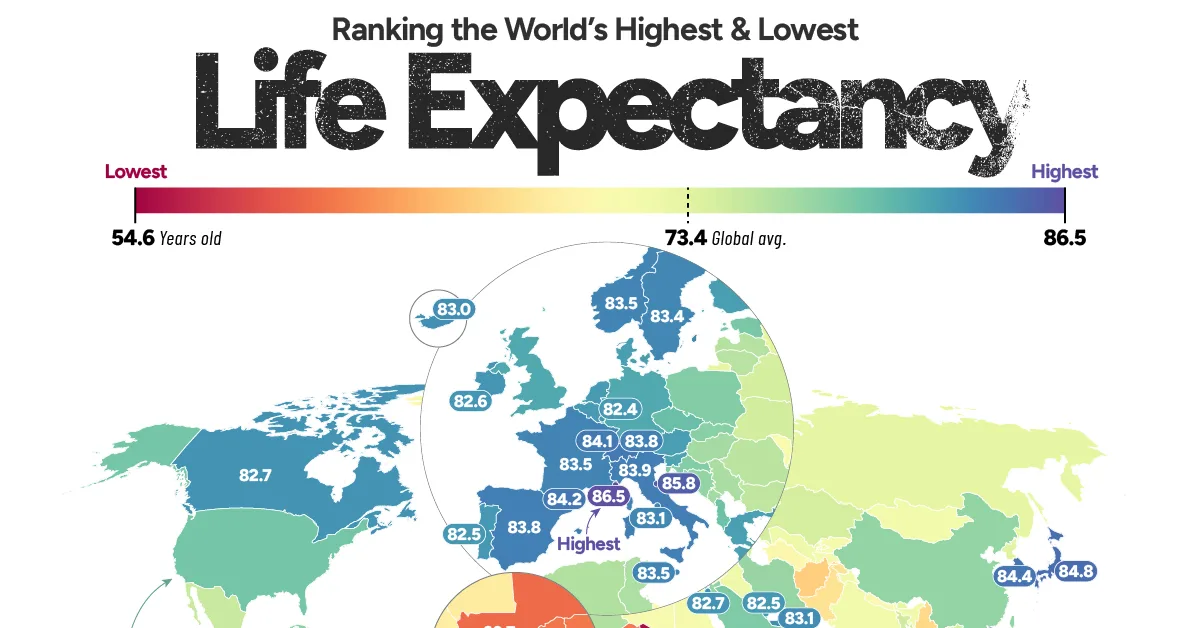
Different organizations produce different results because they use different methodologies. The World Bank, the UN, the Social Security Administration, and national statistics offices all publish slightly different life expectancy figures for the same country. Sometimes the gap is six months. Sometimes it is two full years. This is not a conspiracy. It is a difference in how they handle infant mortality adjustments, period versus cohort life tables, and whether they extrapolate into the future or report purely historical data. When I was building retirement product pricing models, my team once ran into a situation where our actuarial table showed a 78-year life expectancy for a certain demographic, but the client's public-facing marketing materials cited 82 years from a completely different source. The discrepancy cost us about three weeks of recalibration work. We resolved it by agreeing to use a single source for each demographic segment and flagging every assumption in the product documentation. Transparency prevented the argument from escalating further.
How To Interpret Life Expectancy Without Misleading Yourself
Start by understanding the difference between period life expectancy and cohort life expectancy. A period life table reflects death rates in a single year. A cohort life table follows an actual group of people born in the same year as they age. Cohort estimates are always higher because medical technology improves over time, and period tables do not account for that improvement. If you want a more personalized estimate rather than a population average, there are calculators available that factor in genetics, lifestyle, and medical history. The Mayo Clinic calculator, the Healthier Nations tool, and various pension-age calculators all use different underlying data. None of them are particularly accurate for anyone over the age of 55 because the sample sizes in validation studies tend to be small at older ages. The margin of error widens considerably past 70. I encountered a case where a client used an online calculator that projected a life expectancy of 91 for a male in his mid-40s with a family history of heart disease. The calculator had no input for family medical history. It was pulling from general population averages. I recommended he consult with his physician instead and use clinical risk scoring tools like the ASCVD risk estimator, which actually incorporates the relevant variables. The physician's assessment came in at roughly 76 years. That is a 15-year difference driven entirely by whether personal risk factors are included in the model.
Get the Full Details
Common Pitfalls People Make With This Data
One of the most persistent mistakes is assuming that life expectancy applies equally across socioeconomic groups within a country. In the United States, for example, life expectancy can vary by up to 20 years between neighborhoods that are only a few miles apart. The difference comes down to access to healthcare, environmental exposure, stress levels, and economic stability. A single national number erases all of that. Another frequent error is using life expectancy to determine retirement savings needs without adjusting for longevity risk. If you plan your finances around the average life expectancy, you are planning for a outcome that half the population will exceed. That is the difference between running out of money in your 90s and being financially secure well past that point. I worked on a project where we compared the retirement planning assumptions of two firms. One used a simple period life table. The other used a cohort-based projection that accounted for anticipated improvements in mortality. Over a 30-year horizon, the gap in projected fund requirements was substantial. The cohort-based approach required significantly more capital upfront but produced far more realistic outcomes for actual clients. The lesson here is that methodology selection has real financial consequences, not just academic ones.
Where Life Expectancy Data Fails Completely
Crisis situations expose the fragility of life expectancy numbers. During the 2020 pandemic, global life expectancy dropped by roughly two years almost immediately. The recovery took several years and was uneven across countries. Life expectancy tables published in 2019 were essentially worthless for anyone making decisions in 2020. This is not an argument against using these statistics. It is an observation that they are fragile indicators. There are also regions where reliable vital registration data simply does not exist. In some countries, life expectancy figures are estimated through model life tables rather than actual recorded data. The estimates are useful for broad comparisons but should not be treated as precise measurements. I once reviewed a report that cited a life expectancy figure for a country without universal civil registration, and the underlying estimate had a confidence interval spanning nearly eight years. That kind of uncertainty makes the number almost meaningless for individual decision-making. If you need to make decisions based on life expectancy data, the most practical approach is to use it as a reference point rather than a fixed value. Combine it with personal health assessments, consider the methodology behind any published figure, and always account for the possibility that the number could shift significantly in either direction depending on broader health trends and individual circumstances.