Why Traders Care About Commodity Position Data
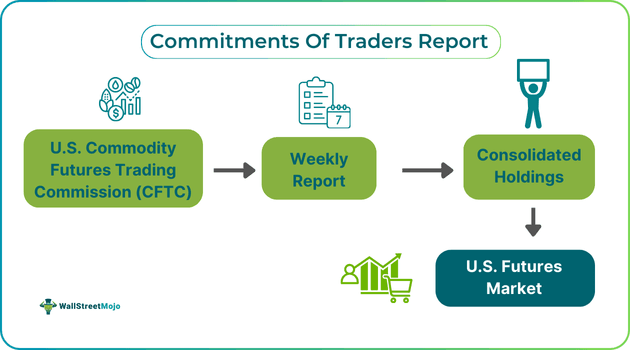
Every Friday, the CFTC releases positioning data from futures markets around 3:30 PM Eastern. The report goes live and within minutes, trading communities scrape it, paste it into spreadsheets, and make assumptions about where prices are headed next. Most of those assumptions are wrong because people treat the raw numbers as directional signals instead of what they actually are: a snapshot of where money sits at a point in time. I have spent years pulling and analyzing this data across corn, crude oil, gold, and the S&P 500 E-mini. The part nobody tells beginners is that the report does not predict moves. It shows accumulation and distribution. You can get crushed if you bet against a huge long position without also looking at price structure, volume, and the actual market context. The numbers are easy to misread when you skip that step.
What Is The Commitment Of Traders Report
It is a weekly census of open interest filed by designated contract markets and reported to the public by the Commodity Futures Trading Commission. Each contract lists three participant categories: commercial traders, non-commercial traders, and nonreportable positions. Commercial traders are usually hedgers. Non-commercial traders are typically large speculators like hedge funds. Nonreportable positions are smaller traders who do not meet the reporting threshold. The CFTC publishes it on their website at www.cftc.gov. The file itself is a PDF and an Excel table you can download after selecting the commodity and trading session. It comes out Friday aftermarkets and the data reflects positions held as of the previous Tuesday.
How To Pull The Data Without Losing Your Mind
Go to the CFTC website and find the Commitment of Traders section. Pick the market you want. Most traders pull the Legacy report because it has longer historical series going back decades. The Disaggregated report gives more detail but has a shorter timeline and breaks contracts into more subcategories. Download the Excel file. Open it. You will see columns for Long, Short, and Open Interest. Note that open interest does not equal the number of contracts traded. It equals the number of outstanding contracts. One long and one short make one open interest contract. Here is the part where most people screw up the math: the net position is long minus short, not long plus short. If you feed the raw numbers into a model without confirming your formulas, your net calculation will be completely wrong and your signal will look inverted. I learned this the hard way in 2019 when I was building a script to track gold positioning and my output showed massive speculative longs during a period where price was clearly being sold into. I had added long and short instead of subtracting them. Took me about forty minutes to catch it after comparing my numbers by hand against a published summary article.
Get the Full Details
Reading Between The Lines
The single most useful metric is the net non-commercial position relative to its own historical range. Not relative to price. Relative to its own history. Hedge funds rarely flip from extreme net long to extreme net short in one week. They accumulate slowly. When the data shows non-commercials hitting the 90th percentile or higher of their historical net position, price is usually extended. That does not mean it will drop immediately. It means the odds are worse for a continuation trade. Another thing beginners miss: commercial hedgers often take the opposite side of extreme speculative positioning. When non-commercials are overwhelmingly long, commercials are overwhelmingly short. That is the nature of hedging. Producers sell to lock in prices. The data does not tell you whether those hedges will be unwound or added to. It just tells you what is currently there. Watch for divergence between open interest growth and price movement. If open interest is rising sharply while price is flat, new money is entering but not pushing the market. That often precedes a directional move, though you cannot tell which direction from the COT alone. You need the chart to decide.
A Real Edge Case I Have Seen Repeatedly
During the 2020 COVID crash, crude oil went negative. The COT data became almost useless for WTI crude for several weeks. Large speculators were scrambling to exit positions before contract expiry. The numbers looked chaotic because traders were squaring exposure for reasons unrelated to fundamental supply demand. I stopped relying on raw net positioning for energy during volatile rollover periods and switched to tracking the weekly change in net position instead. A falling net long over three weeks mattered more than the absolute level during that window. That workaround cuts through the noise when individual weeks are distorted by expiry mechanics. Weekly delta is usually cleaner than absolute levels during rollover months.
Where The Data Falls Short
The report has real blind spots. It excludes OTC derivatives, so total market positioning is incomplete. It covers futures and options on futures, but not swaps or forwards, which institutional players use heavily. A fund might be massively long crude through swaps and show up as neutral on the COT. It is a partial view, not a full one. The lag is another issue. Tuesday data ships Friday afternoon. By the time retail traders parse it, algorithms have already moved on. You are not getting an edge from speed. You are getting an edge from context and patience. Seasonality distorts readings too. Agricultural reports look very different in September harvest months compared to plantings season. Commercial hedging patterns shift with the calendar. If you compare corn non-commercial positioning in March to positioning in August without adjusting for seasonal norms, your analysis will be off.

Practical Workflow That Actually Works
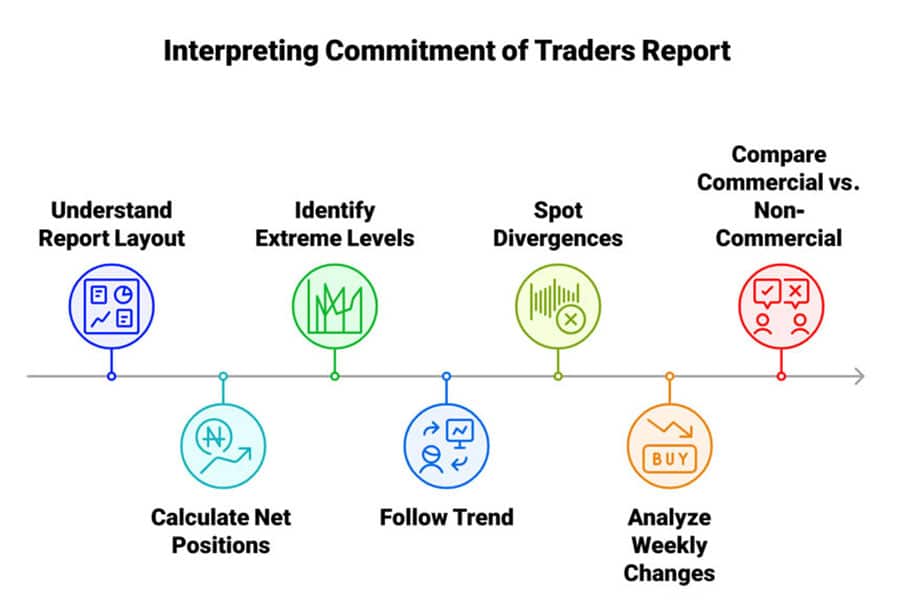
Pull the data every Friday. Calculate the net non-commercial position. Plot it against the last five years on the same chart. Mark the historical extremes. Wait for price to show exhaustion before acting on positioning data. Do not trade the report on release day unless you already have a position you are managing. Use the data as a filter, not a trigger. A speculative net long at the 95th percentile combined with RSI divergence and a failed breakout is a weaker environment for new longs. A speculative net short at the 5th percentile combined with a grinding uptrend and rising open interest tells a different story. Context is everything. Raw numbers without it are just numbers. The CFTC page is the only free and reliable source. Third-party sites republish the data with slight formatting variations, but they occasionally introduce copy-paste errors. I always verify against the official PDF before running any calculation. One wrong digit in a dataset that large can throw off a whole week of tracking.