The Reality of Supply Curves
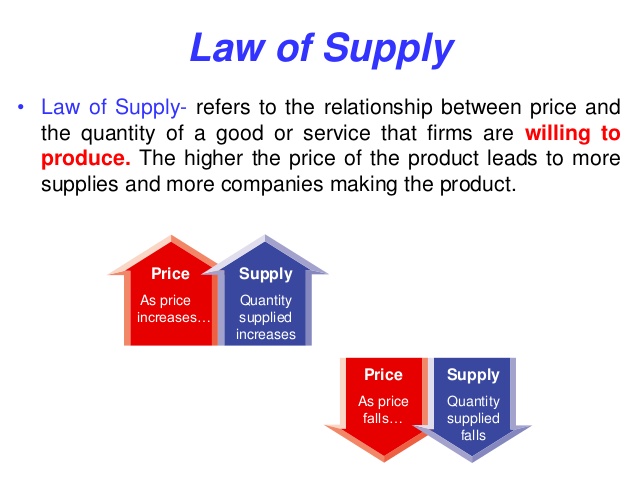
The law of supply is one of those economic principles you learned in your first semester, then immediately forgot because the textbook version made it sound like a universal law of physics. It isn't. It's a shorthand description of how producers generally behave when they're trying to stay profitable, and like any shorthand, it breaks down the moment you try to use it for something real. Here's what the law actually states, stripped of the classroom packaging: when the price of a good or service increases, the quantity supplied by producers also increases, all else being equal. Conversely, when price decreases, quantity supplied decreases. This happens because higher prices make it more worthwhile for producers to allocate resources toward making that particular thing instead of something else.
What Is The Law Of Supply?
At its core, the law of supply rests on profit incentive and cost structure. Producers cover their marginal costs—the cost of producing one additional unit—and if the market price exceeds those marginal costs, producing more adds to total profit. As prices rise, previously unprofitable production becomes viable. Factories that were idling start running. New entrants find the market attractive enough to join. Existing producers push capacity harder. The "all else being equal" part is where people get tripped up in practice. You'll hear economists say ceteris paribus and move on, but nobody ever explains that in any real market, at least three of those "else" variables are changing simultaneously most of the time. I spent a couple of weeks last year working on a pricing model for a regional logistics company and hit this wall pretty hard. They wanted to know how a 15 percent increase in their shipping rates would affect the volume they'd move. The textbook answer said higher price equals lower quantity demanded—that's the demand side, not the supply side, but the principle applies either direction. The problem was that fuel costs had jumped 22 percent in the same quarter, and their main competitor had just gone out of business. The supply curve itself had shifted dramatically while they were trying to use a static model built before either of those events happened. We ended up abandoning the standard equilibrium approach and switched to a scenario-based sensitivity analysis that explicitly modeled the fuel cost shock and the competitive landscape change separately. Took us three days instead of three hours, but the forecast was actually useful instead of mathematically elegant and wrong.
Things That Actually Shift the Supply Curve
A change in the price of the good itself causes a movement along the supply curve, not a shift of the curve. This distinction matters because every analyst I've ever worked with confuses them at least once in their career, and the consequences range from mildly embarrassing to financially expensive depending on the stakes. Input costs are the big one. When the price of raw materials, labor, or energy goes up, the supply curve shifts left—producers are willing to supply less at every price point because their costs have risen. If you're watching the natural gas market, you can see this play out in real time every winter. The price spikes, and suddenly the supply curve recalibrates because everything from fertilizer production to electricity generation depends on that single input. Technology shifts supply the other direction. Better production methods, automation, improved logistics—all of these lower marginal costs and shift the curve right. A concrete example: the fracturing and horizontal drilling revolution in shale oil didn't just increase supply; it fundamentally changed the shape of the supply curve by making previously inaccessible reserves economically viable at much lower price points than conventional drilling ever could.
Get the Full Details

Number of sellers in the market directly affects total supply. More competitors enter, supply increases. A few leave due to regulatory pressure or consolidation, and supply contracts. The pharmaceutical industry demonstrates this with remarkable clarity—when patents expire and generic manufacturers flood in, the supply curve flattens dramatically and prices drop roughly 80 to 90 percent within a few years in most categories. Government policy includes subsidies, taxes, tariffs, quotas, and regulations, and it's the variable that makes supply curve analysis nearly impossible to keep clean. A production tax shifts supply left. A subsidy shifts it right. Quotas are a special case because they create a hard ceiling that the price mechanism can't push through, essentially making the supply curve perfectly vertical at the quota amount until the black market kicks in to fill the gap. Expectations about future prices matter more than most introductory courses will tell you. If producers expect prices to rise next quarter, they may hold back supply now to sell later at the higher price. This is the speculative withholding that shows up in commodity markets regularly, and it's one reason why price signals can become self-reinforcing or self-defeating depending on collective expectations.
Natural conditions apply primarily to agriculture, mining, and anything dependent on weather or geology. A drought doesn't just reduce crop yields temporarily; it can shift the entire supply curve for the growing season because the available output at every price point is genuinely lower than it would have been under normal conditions.
Supply Elasticity Is Where This Gets Interesting
Not all supply responds equally to price changes. Elasticity measures how responsive quantity supplied is to a change in price, and it varies enormously across industries and time horizons. Perfectly elastic supply means producers will supply any quantity at a given price. This mostly exists as a theoretical reference point. In practice, you might approximate it in industries with massive excess capacity where additional production costs nothing marginal—like a software company that's already written the code and just needs to serve one more download. Perfectly inelastic supply means quantity supplied doesn't change regardless of price. The classic example is a unique painting or a plot of land in a fixed location. You can't make more of it no matter how high the price goes. This matters because it means the market price is determined entirely on the demand side—you're essentially bidding against other buyers rather than waiting for supply to respond.

Elastic supply means producers can increase output relatively easily when prices rise. This describes manufacturing industries with flexible production lines and readily available inputs. A T-shirt manufacturer can add shifts, source more fabric, and ramp up output within weeks if wholesale prices move up. Inelastic supply means quantity supplied changes very little even when prices move significantly. This is typical of capital-intensive industries with long lead times. Try telling an oil company that high prices mean they should just produce 20 percent more tomorrow. They can't. A new offshore platform takes three to five years from discovery to first oil, and that's if nothing goes wrong, which is never the case. The time horizon is the hidden variable here. In the immediate term, supply is nearly always inelastic because you can't build factories or drill wells overnight. Over six months to a year, some adjustment becomes possible. Over a decade, the curve looks completely different because the industry has had time to restructure entirely. Most supply analyses fail because they implicitly assume a time horizon that doesn't match the actual question being asked.
The Production Cycle Problem
There's a specific edge case that catches people out regularly, particularly in commodities and agriculture. It's called the cobweb theorem, and it describes what happens when there's a significant time lag between when production decisions are made and when the product actually reaches the market. Producers base their planting or production decisions on current prices. By the time the crop is harvested or the product is manufactured, the price may have changed because supply finally caught up with demand. If prices were high when they planted, everyone planted more. When harvest comes, supply floods the market, prices crash, and producers cut back next cycle. Then supply falls short, prices spike again, and the whole thing oscillates. In some cases it converges toward equilibrium. In others, it diverges and gets worse each cycle. Whether it converges or diverges depends on the relative elasticities of supply and demand, which brings us back to the elasticity discussion above. This isn't just academic. I've seen it play out in live markets. The pork cycle in the United States over the past few decades has been a textbook example. Hog farmers responded to high prices by expanding herds, then when those hogs reached market weight, the oversupply crashed prices, and the whole process repeated with a lag of roughly a year or so depending on breeding cycles.
What Supply Analysis Misses
The law of supply gives you a framework, but it has real limitations that beginners rarely appreciate until they've made a bad decision based on it. It assumes rational profit maximization. This works reasonably well for publicly traded companies answering to shareholders. It works less well for family-owned businesses where the owner's utility function includes things like maintaining employment in their hometown, keeping a certain production level for pride, or simply avoiding the hassle of downsizing. The supply decisions look identical on paper but come from completely different motivations, and the price responsiveness can be qualitatively different. It assumes information flows freely. Producers need to know current prices and have some reasonable expectation of future prices to make supply decisions. In thin markets with opaque pricing—certain agricultural commodity trades, specialized industrial chemicals, some medical supplies—producers are often flying blind, and the supply response becomes erratic rather than predictable.
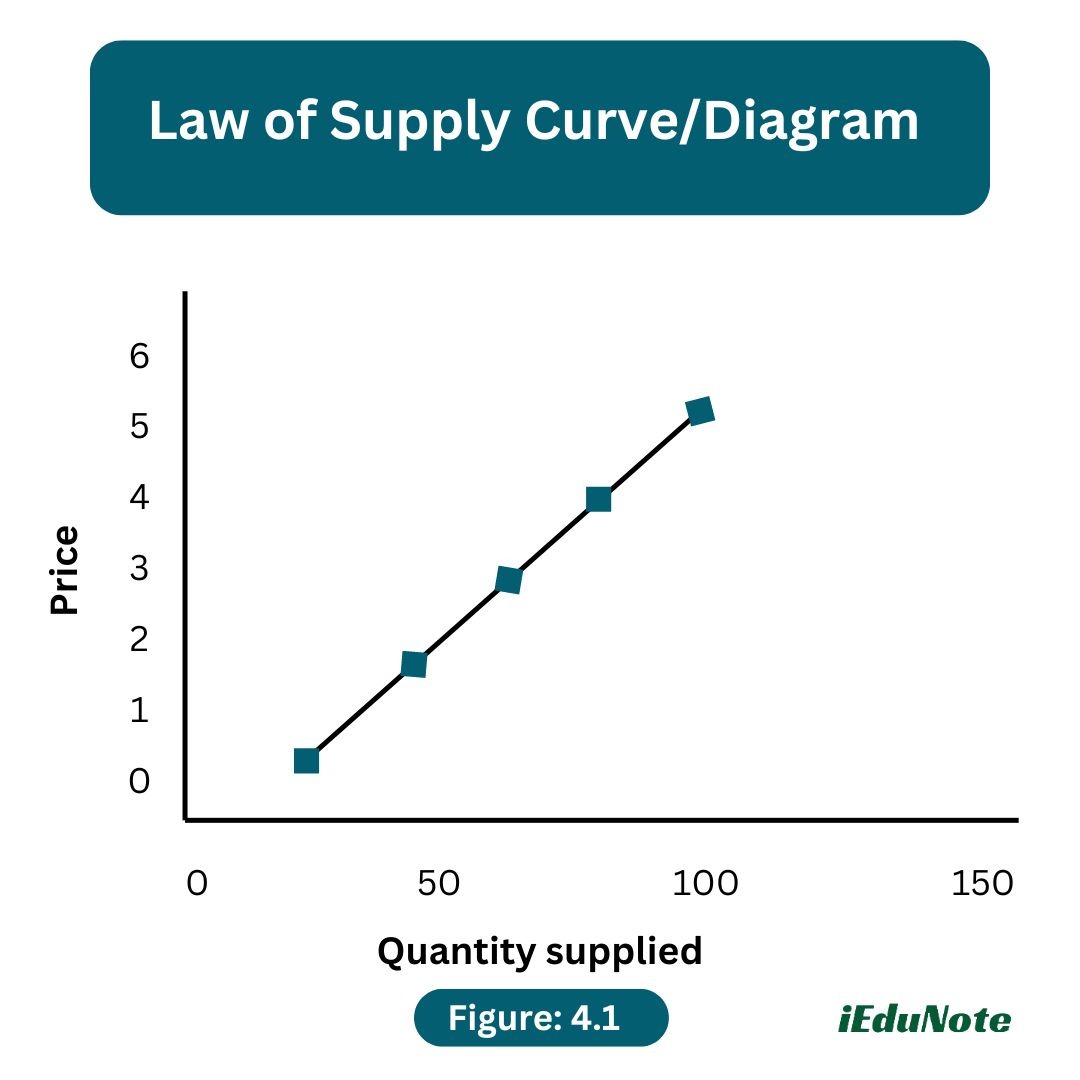
Capacity constraints create discontinuities. Supply curves drawn in textbooks are smooth and continuous. Real supply curves have step functions. A factory has a maximum capacity. Once you hit that ceiling, additional price increases don't produce any additional supply until you invest in new capacity, which is a lump-sum commitment that can take months or years. The result is that small price changes near capacity limits produce large swings, and the smooth curve approximation breaks down entirely. Inventory can decouple price from supply in the short term. When producers have storage capacity and existing inventory, they can respond to price signals by drawing down or building stockpiles rather than changing production. This is why you sometimes see prices stabilize even when production hasn't adjusted yet. The inventory acts as a buffer, and the actual supply curve relationship becomes visible only after the buffer is exhausted.
How to Actually Use This
When you're working with supply data instead of a textbook diagram, here's what tends to work: Get historical price and quantity data for as many periods as you can find. You want at least three to five years of data to separate normal variation from structural shifts. Monthly data is better than annual because it captures more cycles and gives you more observations for regression analysis. Quarterly is acceptable. Anything coarser and you'll be fitting supply curves to noise. Watch for structural breaks in your data. A merger between two major suppliers, a new regulation, a pandemic, a trade agreement, a technology rollout—each of these shifts the supply curve and makes data from before and after the event non-comparable. I've seen people run regressions on pre- and post-regulation data without accounting for the shift and get coefficients that were statistically significant but economically meaningless because they were averaging two different relationships.
Separate movements along the curve from shifts of the curve. This means you need to identify and control for the shift factors—input costs, technology changes, number of sellers—rather than just regressing price against quantity and calling it a supply curve. Without controlling for those exogenous variables, you're estimating a reduced form that mixes supply and demand effects together, and the coefficient you extract tells you nothing reliable about supply behavior specifically. Test your elasticity estimates against known benchmarks in similar industries. If your estimated price elasticity of supply for a manufacturing product comes out to 0.1 when comparable industries show values between 0.5 and 2.0, something is wrong with your specification. Either you're picking up demand-side effects, you have omitted variable bias, or your data covers too short a time horizon for supply to have fully adjusted. Re-examine your approach before you build a decision on it. Remember that the law of supply describes a tendency, not a mechanical relationship. Producers face real constraints, incomplete information, and sometimes motivations that have nothing to do with marginal profit calculations. The curve is a useful abstraction, but the abstraction stops being useful the moment you forget it's an abstraction and start treating it like the territory.