Understanding Economic Resources Beyond the Textbook
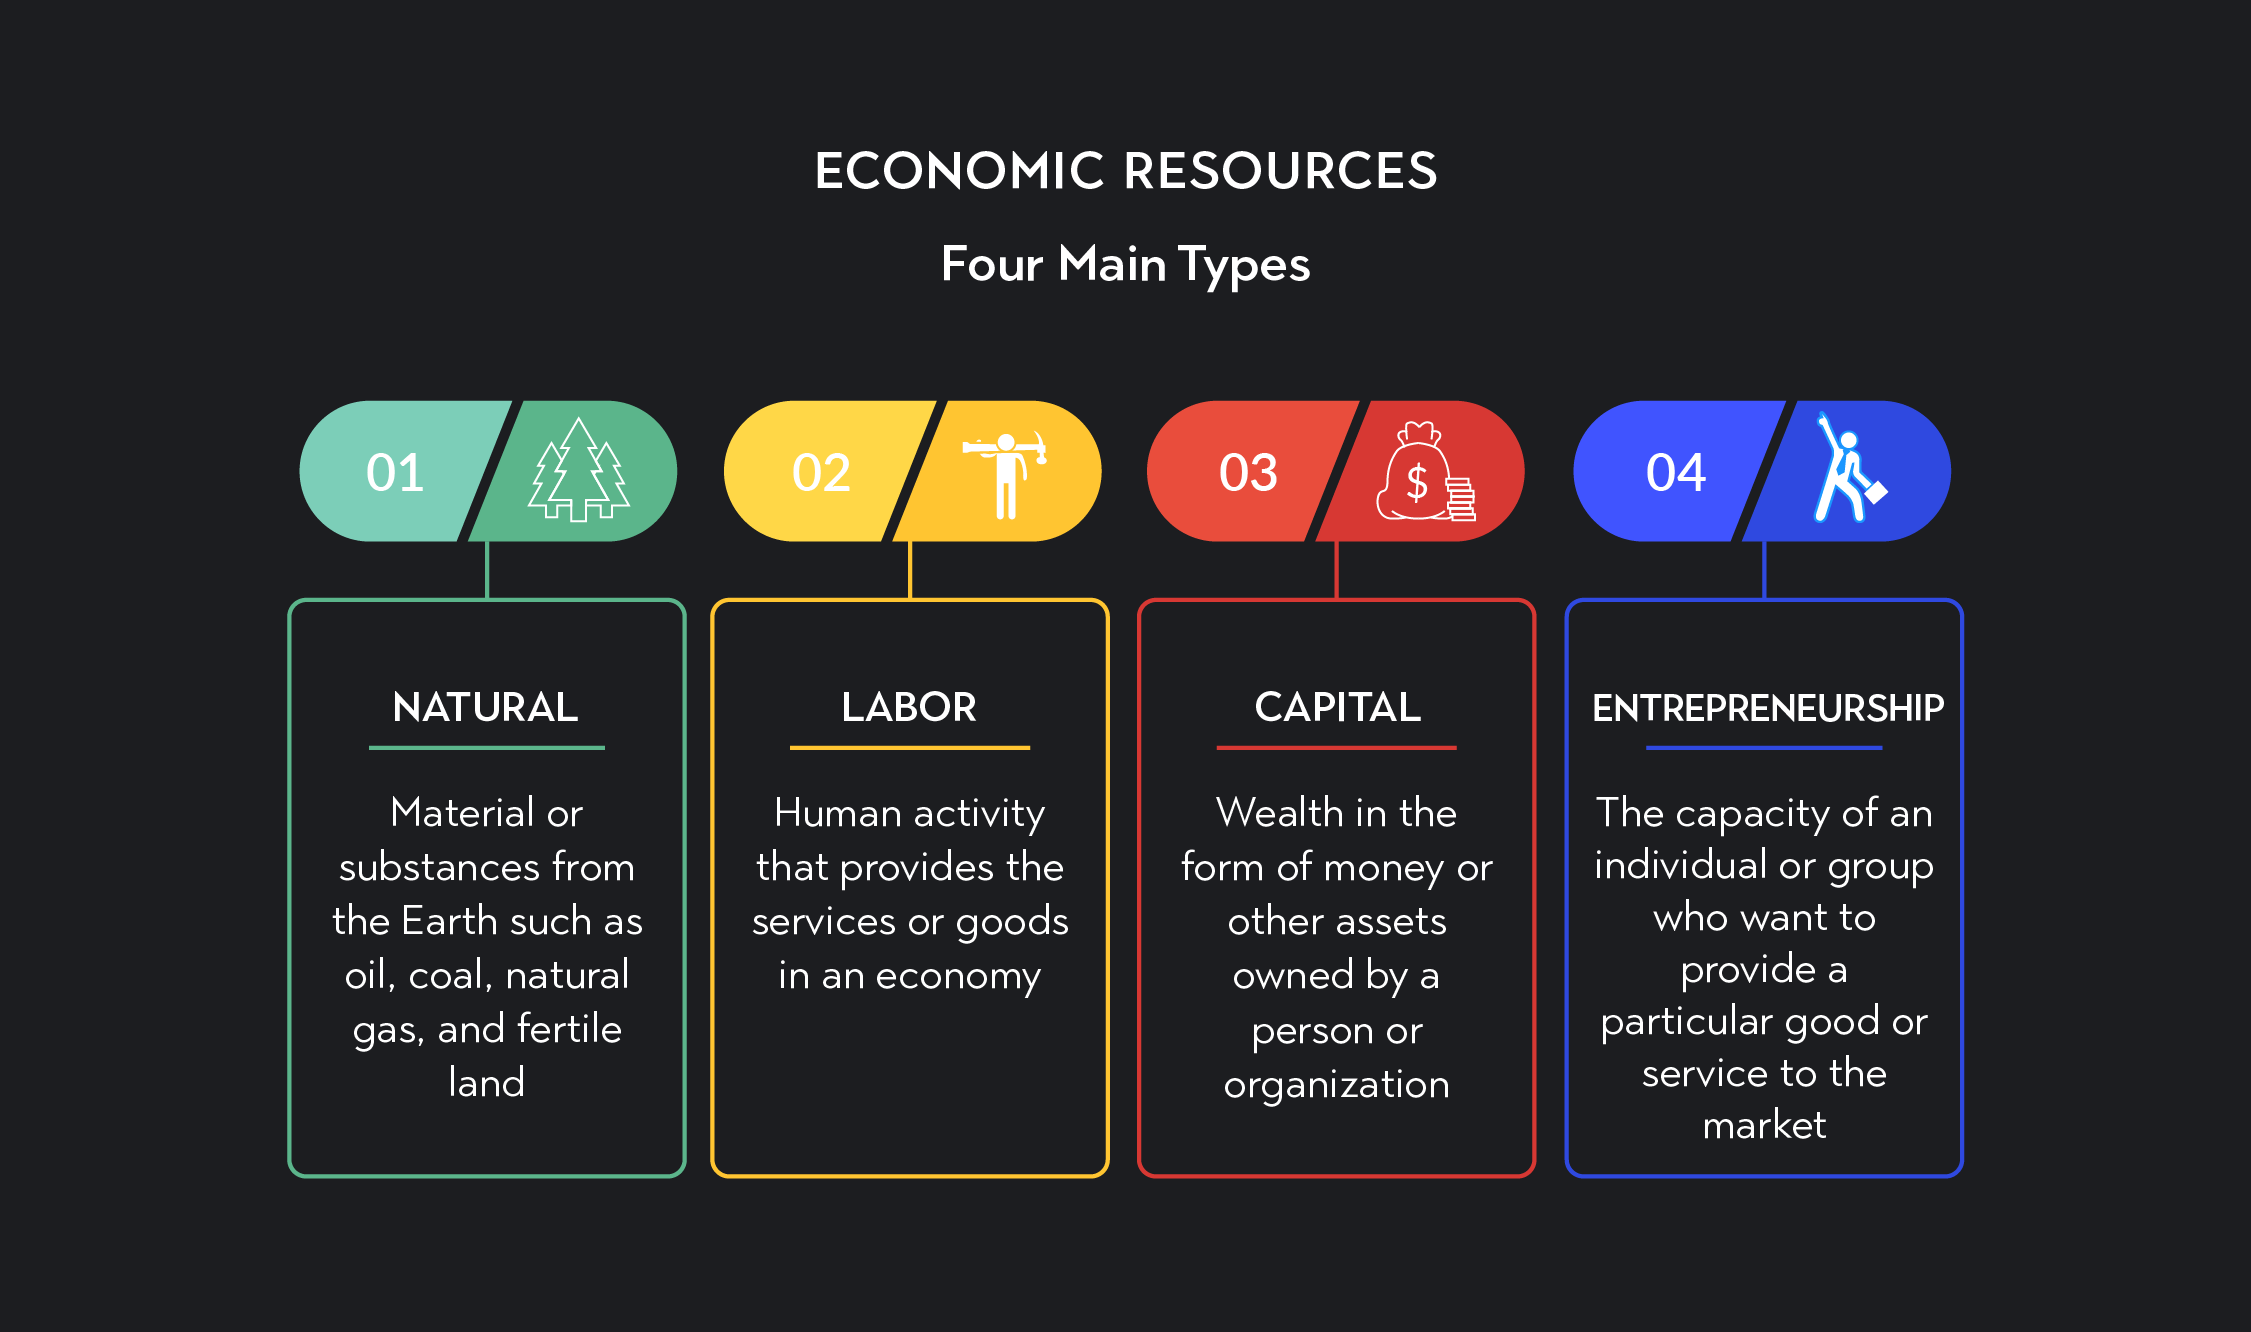
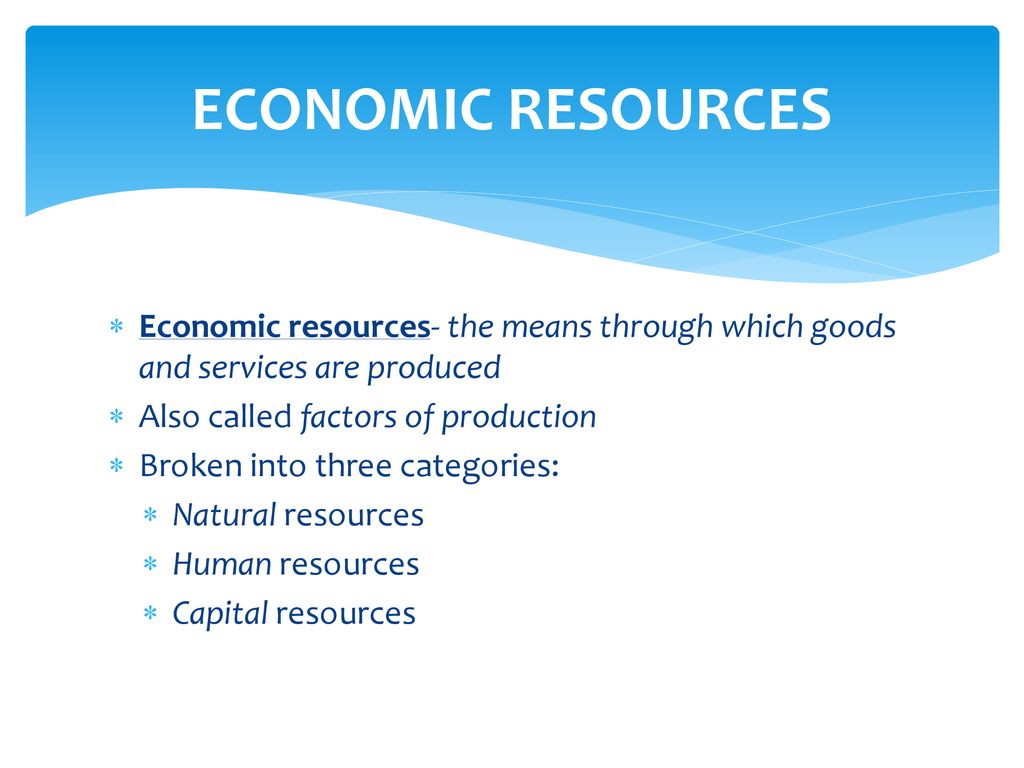
Economic resources are the inputs used to produce goods and services. That's the basic definition you'll find in any intro textbook. The truth is more layered. Resources aren't just land, labor, and capital. There's entrepreneurship as a fourth category, and land isn't limited to actual dirt — it includes every natural resource, from minerals to clean air. Capital isn't just money. Money is financial capital. Real capital is machinery, buildings, tools, the physical stuff that helps produce things. I spent years working in supply chain logistics before moving into consulting, and what I learned there is that most people still confuse financial capital with physical capital. You can have a balance sheet full of cash and still be unable to produce anything if you don't have the factories, equipment, or skilled workers to back it up. This distinction matters more than it should.
What Is True About Economic Resources
One thing that's consistently true: they're all scarce. That's the foundation of economics itself. If something were infinitely abundant, it wouldn't be an economic resource. Air was free for a long time in most places, but that's changing as carbon pricing and pollution regulation come into effect. Even now, in some parts of the world, clean air is becoming a traded commodity rather than a free good. Another truth that gets overlooked: economic resources are complementary. You can't produce much with just one type. A single piece of land means very little without labor to work it, capital to build on it, and entrepreneurship to organize the whole thing. I once worked with a mining company that had figured out a large lithium deposit but couldn't move forward because they had neither the processing equipment nor the technical workforce. The resource was there. The problem was the rest of the production chain. It took two years and about $400 million to build theinfrastructure before anything productive came out of that deposit. The fourth truth, and this one trips up a lot of students: economic resources can change category. Labor becomes capital when you automate a process. Land becomes capital when you build infrastructure on it. Entrepreneurship is the hard one to quantify, but it's what moves the other three around. It's the least tangible and the most consequential.
Common misconception: having more resources always leads to more output. That's not how it works. The law of diminishing returns kicks in pretty fast. Add more workers to a fixed piece of land or a fixed number of machines, and eventually each additional worker contributes less and less. I've seen this repeatedly in manufacturing settings where a plant ran best at about 85 percent capacity. Push past that with overtime and extra shifts, and the cost per unit actually went up because of errors, downtime, and quality issues. Another pitfall: assuming resources are fixed. They're not. New technologies create new resources or make old ones more useful. Fracking changed the entire energy landscape by making previously inaccessible natural gas reserves economically viable. That wasn't about finding new oil. It was about a technique that turned a geological dead end into a major resource base. When I advised a mid-cap energy company on this transition a few years back, the ones that moved fast enough to revalue their asset bases ended up in a much stronger position than the ones that treated their existing reserves as the only resources they had.
Get the Full Details

How to Evaluate Economic Resources in Practice
Here's how I approach resource analysis these days. Start by categorizing every input you're working with using the standard four: land, labor, capital, entrepreneurship. Be specific. "Labor" isn't just headcount. It's skill level, availability, training cost, turnover rate. A warehouse with 200 entry-level packers is fundamentally different from one with 200 experienced forklift operators, even if the number is the same. Then assess substitutability. Can one resource replace another? Labor and capital are often substitutable in ways that matter. Automation trades labor for capital. The question is whether the substitution saves money over the relevant time horizon. Short-term calculations often favor keeping labor. Long-term projections usually favor capital investment. The crossover point depends entirely on your cost of capital, wage growth expectations, and how fast technology is advancing in your sector. Next, check for constraints. The binding constraint is the resource that limits your total output. This is operations management 101, but it gets ignored constantly. I remember reviewing a mid-sized food processing company that was convinced their problem was equipment. They wanted to upgrade to faster packaging lines. When I mapped out their actual production flow, the bottleneck was cold storage capacity, not packaging speed. Throwing more packaging machines at the problem would have only created more unfinished product piling up. We redirected the investment to expand refrigeration, and throughput increased by about 30 percent within six months.
For valuation, use replacement cost rather than historical cost whenever possible. A building purchased ten years ago for $2 million might be worth $8 million to replace today. Using the original figure understates the true capital resource available in your operation. This is especially relevant during inflationary periods when asset prices drift significantly from book values. There's also the human capital angle that most analyses skip. Skills are resources too. Training an employee costs money and time, but that trained worker is a durable resource that appreciates with experience. Losing them is a real economic loss. I've seen companies lay off veteran workers during downturns and then spend three times what they saved to recruit and train replacements when demand recovered. The laid-off workers already had institutional knowledge, established workflows, and relationships. That's an intangible resource that's easy to underestimate until it's gone.
Where Traditional Resource Models Fall Apart
The standard framework works fine for straightforward production decisions. It breaks down in a few situations. First, knowledge-based industries. In software development, data, or research, the primary resource is intellectual capital, which doesn't fit neatly into any of the four categories. Code is reproducible at near-zero marginal cost. A dataset can be used by an infinite number of products simultaneously without being "used up." Traditional resource scarcity logic doesn't apply the same way here. Second, network effects. Some resources gain value as more people use them. A social media platform's user base is a resource that appreciates with scale in a way that a factory floor doesn't. The usual diminishing returns assumption flips on its head. This is why tech valuations operate differently from industrial valuations. Third, environmental and social resources that aren't priced into markets. Clean water, stable climate, social trust — these are real economic resources, but they're often treated as externalities. When they degrade, the cost shows up later, usually as regulation, litigation, or operational disruption. I've seen companies that ignored this face compliance costs that exceeded ten percent of annual revenue within a few years of regulatory action. The resource was there the whole time. It was just invisible on their balance sheet until it wasn't.
If you're trying to apply resource analysis to something outside traditional goods and services — say, public policy or nonprofit work — you'll need to adapt the framework. The categories still hold, but you'll need to define scarcity differently since outputs aren't measured in market prices. Use willingness-to-pay surveys, shadow pricing for non-market goods, or cost-benefit analysis adjusted for distributional effects. None of these methods are perfect. They're the best tools available.