Why Line Items Lose Their Meaning Without a Common Base
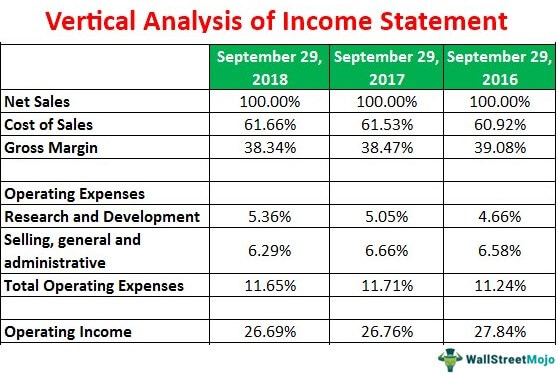
I spend most of my week looking at financial statements that have been massaged into pretzels. You know the type - revenue went up 12%, but net income only went up 3%. The numbers look fine individually, but together they tell a story nobody would draw from them. This is exactly where vertical analysis becomes useful, because it strips away the absolute values and puts every line item on the same scale. The method itself takes about thirty seconds to understand and five minutes to set up in any spreadsheet worth using. You pick a base figure - revenue for the income statement, total assets for the balance sheet - and divide every line item by it. The result is a percentage. That is it. An expense that was $47,000 last year and $51,000 this year means nothing on its own. But if revenue was $500,000 and then $520,000, you can see that expense actually grew from 9.4% of revenue to 9.8%. Something shifted even though the dollar increase looked manageable.
What Is Vertical Analysis In Accounting
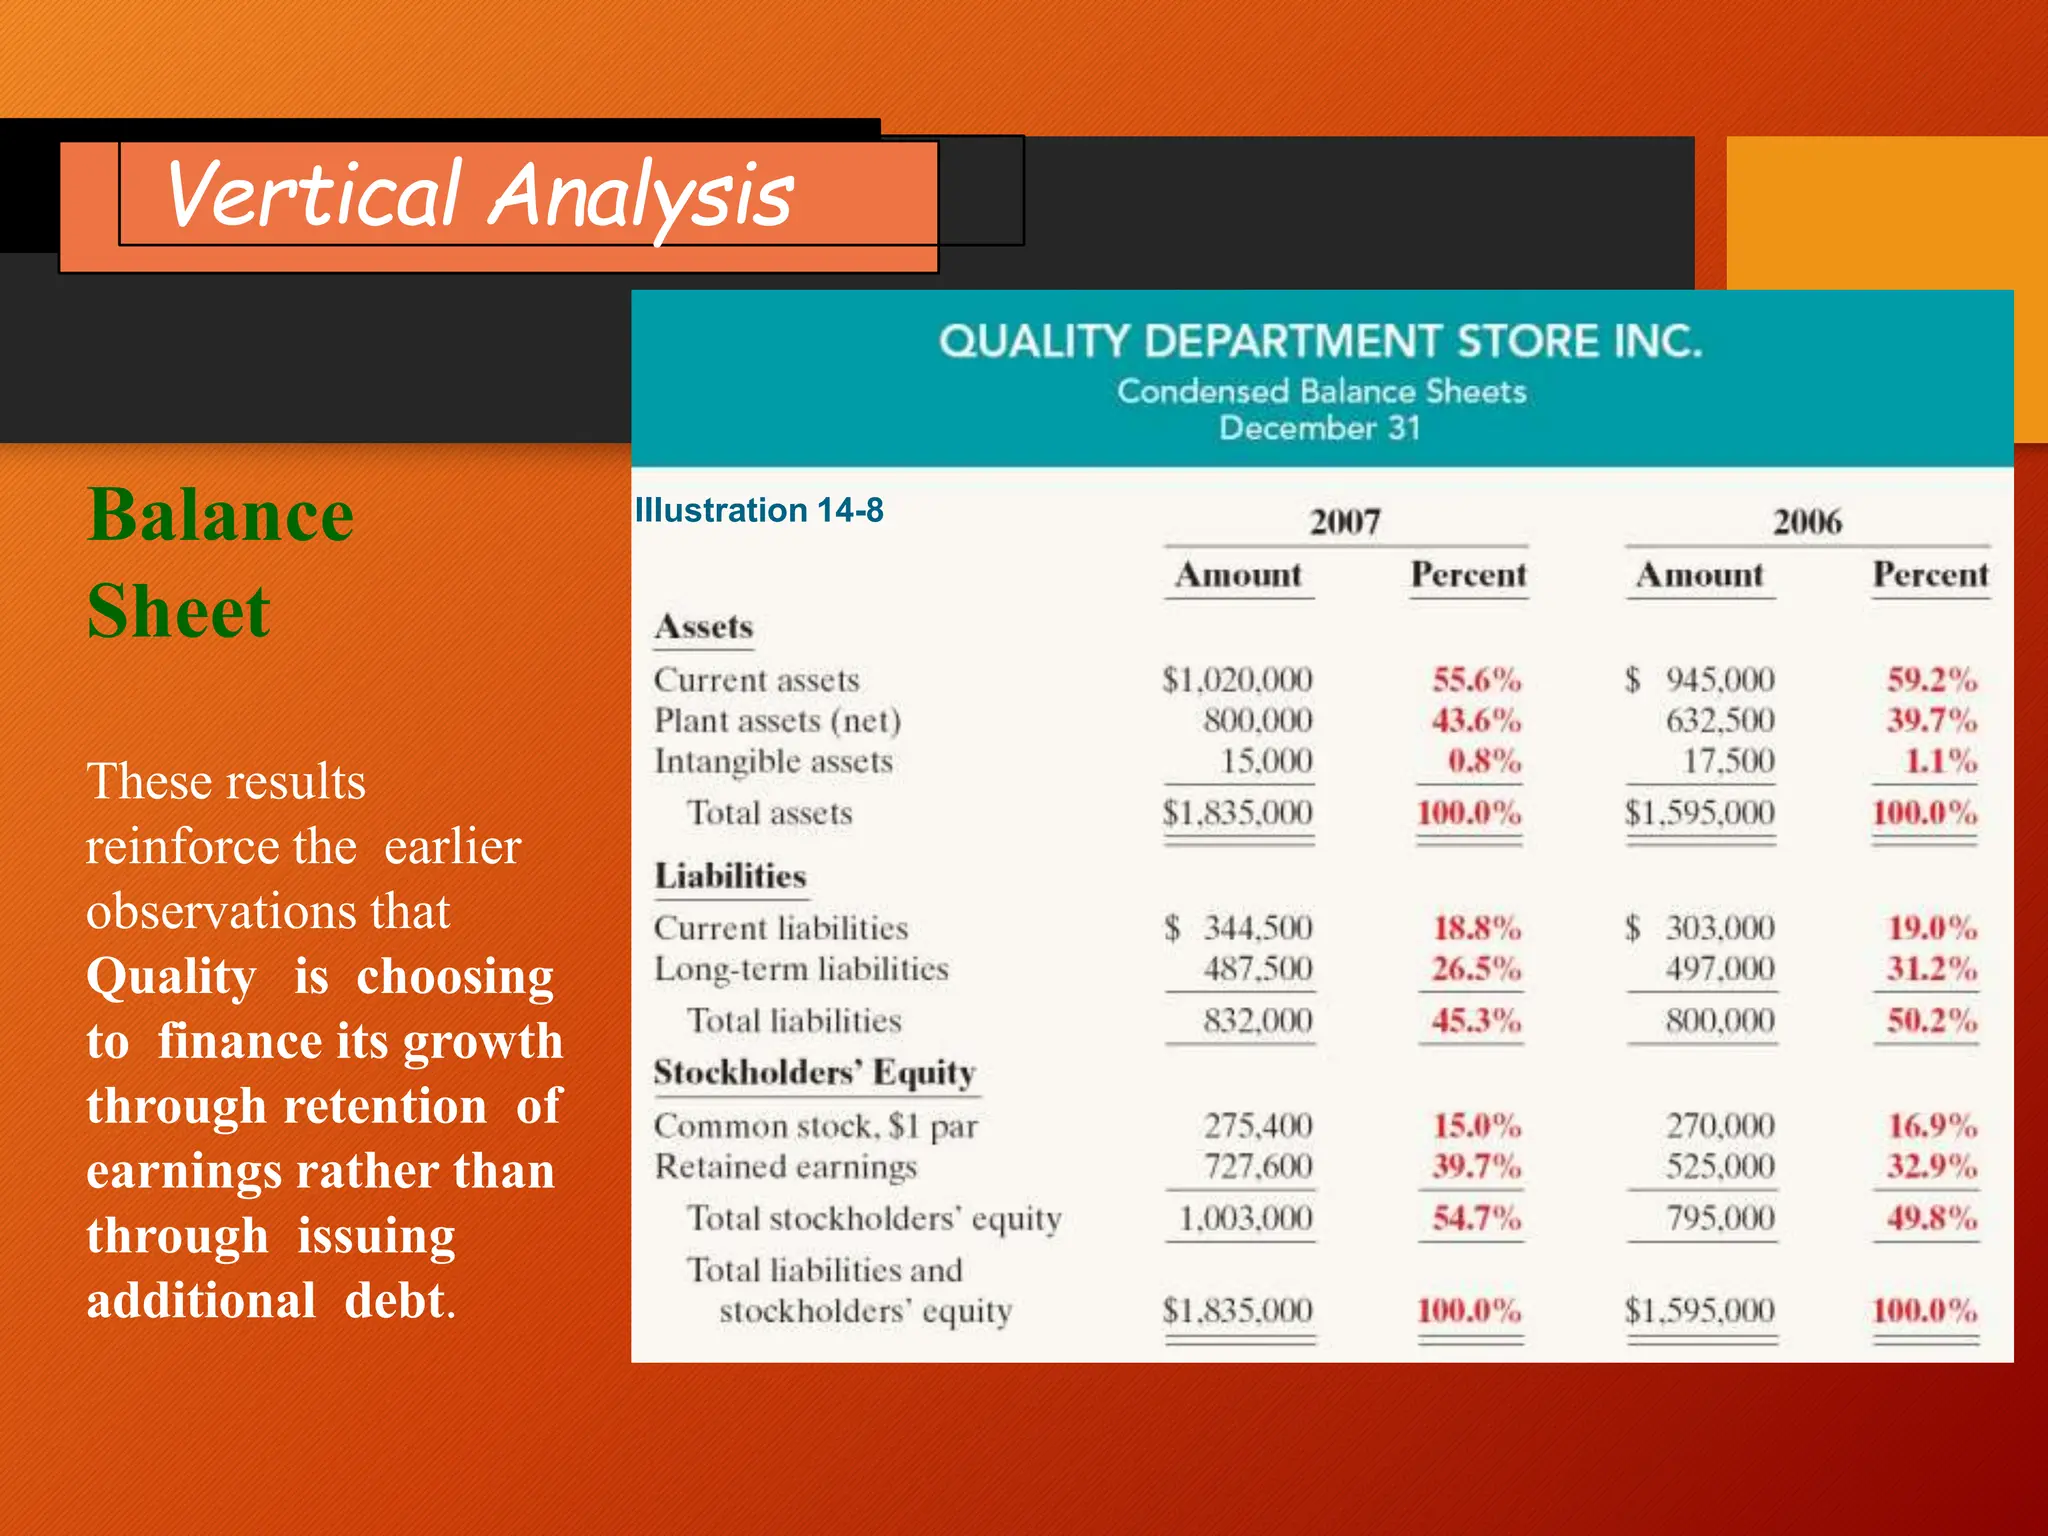
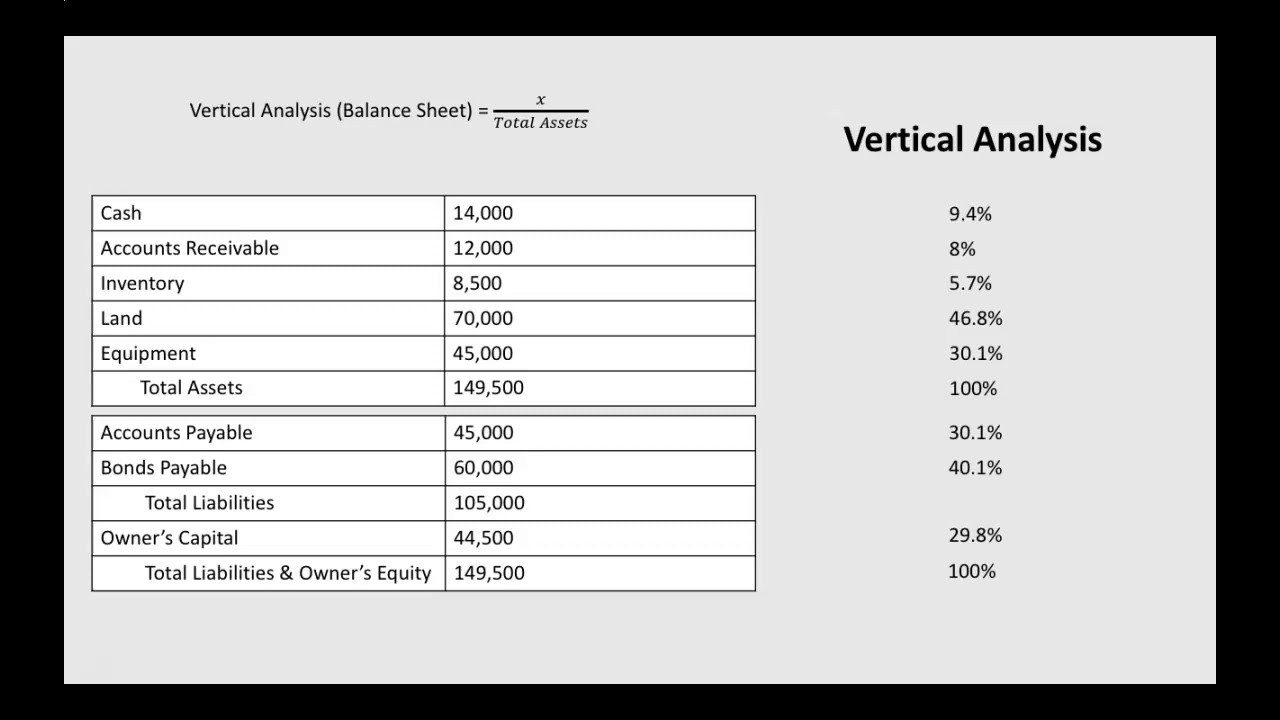
At its core, it is a technique for standardizing financial data so you can compare periods, companies, and categories without the distortion of raw scale. A $10,000 marketing spend is a rounding error for Amazon and a budget crisis for a regional retailer. Vertical analysis collapses both into the same framework by expressing each item as a percentage of its relevant total. Revenue lines become percentages of total revenue. Asset lines become percentages of total assets. It is the accounting equivalent of comparing two recipes by their ingredient ratios rather than their total weight. Beginners usually miss one important detail. The base figure is not fixed across different types of analysis. For the income statement, the base is always revenue. For the balance sheet, it is total assets. For a cash flow statement, some people use net income as the base, others use total cash inflows. Pick one and stick with it for the entire set you are analyzing. Switching midstream will make your percentages incomparable and honestly makes the exercise worthless. Here is a practical example. Take a simplified income statement where revenue is $1,000,000, cost of goods sold is $600,000, operating expenses are $250,000, and net income is $150,000. In vertical format, those become 100%, 60%, 25%, and 15% respectively. Now imagine next year revenue climbs to $1,200,000, COGS to $780,000, operating expenses to $275,000, and net income drops to $145,000. The absolute numbers look like growth. The percentages tell you COGS jumped from 60% to 65% of revenue, operating expenses rose from 25% to 22.9%, and net income fell from 15% to 12.1%. That is the whole point.
The Complications Nobody Warns You About
I ran into a specific problem last year that illustrates why vertical analysis requires more care than the formula suggests. I was analyzing a mid-market manufacturing company across four quarters. The vertical percentages looked clean and consistent on the surface. Then I noticed that inventory had grown from 18% to 24% of total assets over the period. Not alarming on its own. But when I pulled the individual inventory line items - raw materials, work in progress, finished goods - I saw that finished goods had ballooned from 8% to 14% of total assets. The company was producing more than it could sell and burying the problem in a balance sheet that otherwise looked stable. Vertical analysis on the summarized statement would have missed that. You have to drill into the component breakdowns, not just trust the headline percentages. Another issue is intercompany transactions and one-time items. If a company records a $2 million asset impairment in a single quarter, it will distort every percentage on that balance sheet for the period. The impairment skews everything downward relative to assets, making operating metrics look artificially thin. The workaround is to normalize the base. Remove the one-time item from total assets before calculating percentages, or run a parallel vertical analysis with and without the exception. Both versions live in the same model. You decide which one answers the question at hand. There is also the seasonal distortion problem. Retail companies are brutal here. A Q4 vertical analysis for a holiday retailer will show completely different percentage distributions than Q1 because the revenue base is artificially inflated by seasonal spikes. Comparing Q4 percentages to Q1 percentages is misleading unless you adjust for seasonality or compare year-over-year quarters instead of within-year quarters. I used to make this mistake early in my career and spent three weeks chasing phantom trends before realizing the pattern was just Christmas.
Get the Full Details

Where Vertical Analysis Falls Short
The method has real limitations and you should treat it as a starting point, not an answer. It does not account for inflation. A 5% increase in every line item over ten years will produce identical vertical percentages to a 50% increase, even though the business realities are completely different. Horizontal analysis alongside vertical analysis is non-negotiable if you care about real growth versus nominal growth. It also cannot detect fraud on its own. A company can reclassify operating expenses as capital expenditures and the vertical percentages will look healthier. The ratios improve, but the underlying economics did not. The percentages just moved around. You need supplemental analysis - ratio testing, cash flow reconciliation, benchmarking against peers - to catch that kind of manipulation. The biggest practical bottleneck is data quality. Garbage in, garbage out applies harder here than almost anywhere else in financial analysis. If your chart of accounts changes mid-period, if segment reporting shifts, if there are material restatements, the percentages become unreliable. I have spent entire days tracking down why a vendor expense line jumped from 4.2% to 6.8% of revenue only to discover the reclassification happened during a system migration. The analysis was not wrong. The data was.
Setting Up a Working Model
The spreadsheet setup is straightforward if you avoid the most common trap. Do not hardcode the base figure. Reference it. Every percentage cell should divide the line item by a cell reference that points to the total, not by a literal number. When you copy the model across periods, a hardcoded base will lock you into the wrong denominator for later periods. A referenced base updates automatically. Structure your worksheet with actual financial data in the first columns, vertical percentages in the next block, and year-over-year percentage point changes in a third block. The change column catches the signal faster than the percentage column. A shift from 22% to 24% looks small. A plus two percentage point change flashes a warning. For ongoing monitoring, set conditional formatting on the change column. Highlight anything moving more than one percentage point against the prior period in yellow, more than two in orange. This catches anomalies before they become problems. The system is cheap to build and takes roughly ten minutes to set up properly the first time, which saves hours later when you are dealing with a dozen quarters of data.