Handling the immediate aftermath of a death is mostly about paperwork and logistics, not the emotional stuff everyone talks about.
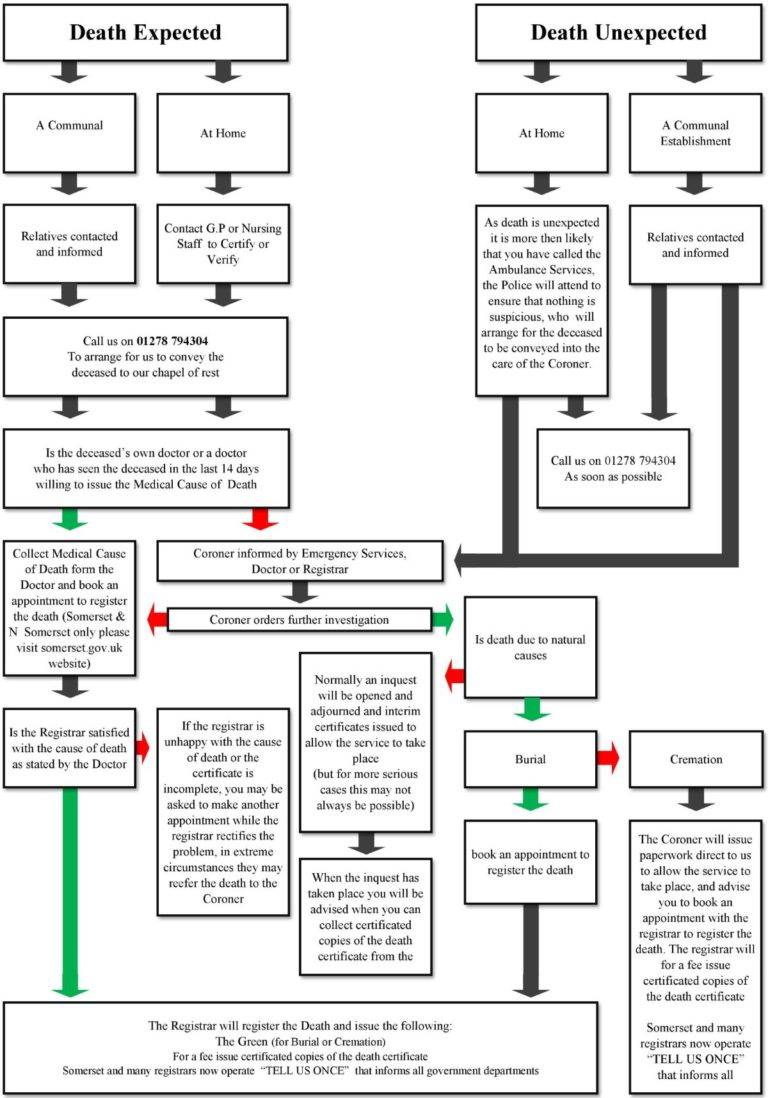
When someone dies at home under hospice care, you call the hospice nurse first. They come out and pronounce the death. That's important because a medical professional has to do that before anything else can happen. Once they've done it, they tell you to call a funeral home. You don't call 911 or the police unless the death is unexpected or suspicious. If you do call the police for an unexpected death, they'll secure the scene and then you're waiting around for hours while the coroner's office sorts it out. That's a different process entirely and it adds days to everything.
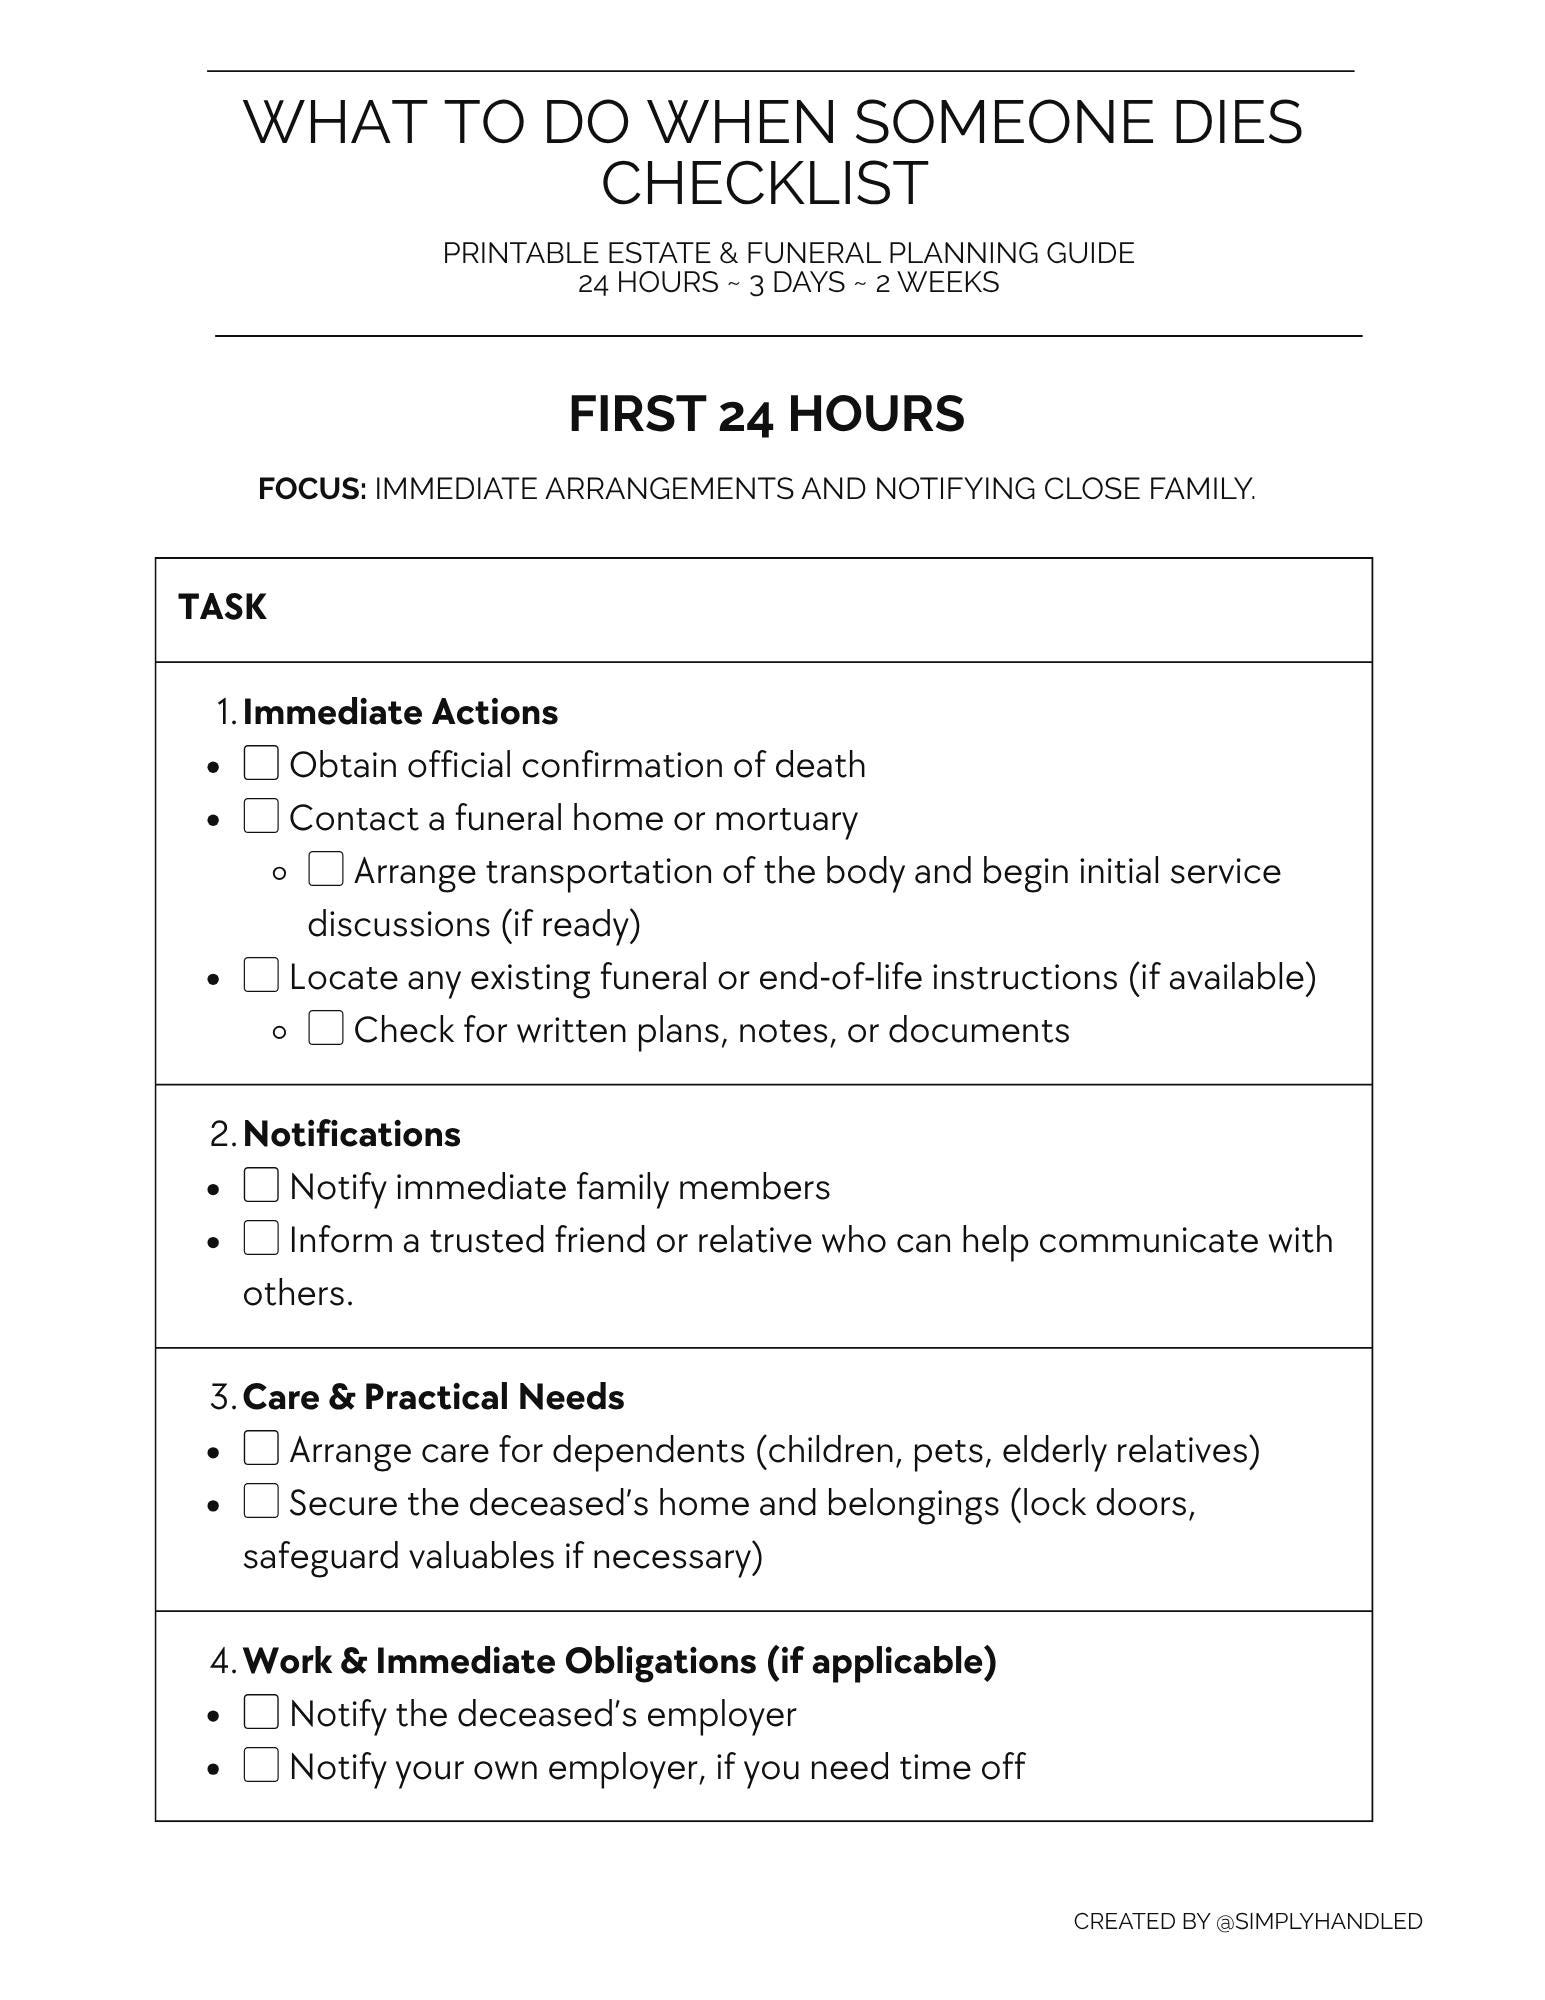
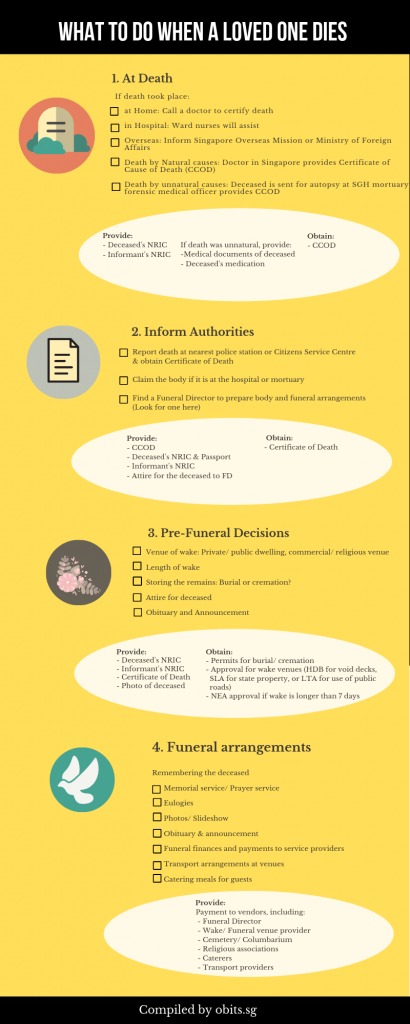
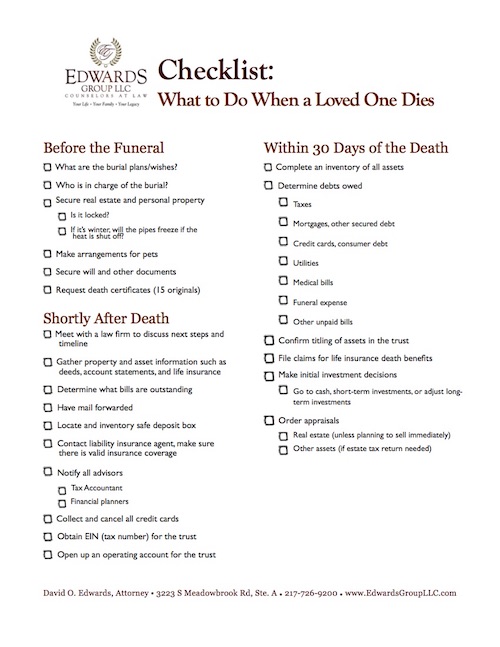
What To Do When Someone Dies
The funeral home you choose handles the body transport, which typically arrives at their facility within two to four hours of the call. From there, you'll make decisions about burial versus cremation, casket selection, and whether there's going to be a viewing or service. The funeral director will guide you through a lot of this but they also have products to sell, so you should know what you're actually required to buy. The Federal Trade Commission's Funeral Rule requires them to give you a price list upfront. You can refuse embalming in most states unless local law requires it, which it doesn't in most cases. You can also rent a casket for a viewing if you want the appearance without the purchase price. Most people don't know these options exist. There's a specific issue that comes up when the death happens in a hospital or care facility. The staff will often suggest you contact a particular funeral home because they have a longstanding arrangement with the facility. That's not illegal, but it's worth knowing about so you aren't steering toward an option you didn't independently research. I had a case where a family called after a hospital discharge and the only number they had was the one the discharge planner gave them. By the time they realized they could shop around, the paperwork trail was already pointing in one direction. It just takes five minutes to call around before you commit. The Social Security Administration side of this is straightforward but easy to miss. You report the death to get the death benefit, which is a one-time payment of two hundred and forty dollars, and to stop any ongoing benefits. You need the deceased person's Social Security number for this. You can do it by calling the SSA at 1-800-772-1213 or by visiting a local office. Many people don't realize the funeral home can report the death to the SSA on your behalf if you authorize it, but getting it done yourself prevents it from falling through the cracks. I once saw a case where a veteran's death wasn't reported quickly enough and the family was billed for a month of pension payments they should never have received. Correcting it took six months and a lot of phone calls.
Bank accounts and financial assets are where things get complicated. You cannot access a deceased person's accounts using their debit card or online login. That's technically still unauthorized use of an account even though you're the surviving spouse or child. The proper path is through probate, which opens up a whole separate process. If the accounts have designated beneficiaries, those assets pass directly to the named person and bypass probate entirely. That's why keeping beneficiary designations updated on retirement accounts and life insurance matters more than most people realize. For accounts without beneficiaries, you'll need to go through probate court to get letters testamentary, which gives you the authority to access and distribute those funds. This process can take anywhere from three months to over a year depending on the state and the complexity of the estate. Digital assets are another area people overlook. Social media accounts, cloud storage, email, cryptocurrency wallets. Each platform has its own process for handling a deceased user's account. Facebook and Instagram allow you to request memorialization or deletion with a death certificate and proof of relationship. Google has a memorialization process too but also lets an appointed legacy contact access certain data. The real problem is cryptocurrency. If someone had Bitcoin or other crypto and you don't have their private keys or seed phrase, that money is gone forever. There's no customer service to call. I handled a case last year where a family inherited roughly eighty thousand dollars in Bitcoin that they couldn't access because the deceased had written the seed phrase on a piece of paper that was in a safety deposit box neither of them had keys for. The bank wouldn't open it without a court order, and the court order process dragged on for months. All the while the wallet sat there with no one able to touch it. There's also the matter of physical mail and subscriptions. You can request the USPS to notify senders of a death by filling out a specific form at the post office. It's not automatic. Creditors and collection agencies will continue to send bills until you formally notify them with a death certificate copy. Some will close the accounts, some will insist on payment from the estate. You should close credit cards proactively rather than waiting for a statement to arrive. A missed payment on a deceased person's account can damage their credit rating and create complications for the estate.
The timeline for most of this compresses into the first two weeks, but the administrative tail can stretch for months or years depending on the estate. If there's a will, probate court supervises the distribution. If there's a trust, the trustee handles things outside of court, which is faster and keeps more of the details private. Neither approach is universally better. A trust costs more to set up initially but saves on court fees and legal time later. A will is simpler to create but exposes the estate's details to public record and requires court involvement. The one thing nobody warns you about is how many different death certificates you'll need. The funeral home will file one with the state, but you'll need multiple certified copies for banks, insurance companies, the SSA, the VA if applicable, and any other institutions. Each one costs between ten and twenty-five dollars depending on the state. Order at least ten to fifteen copies upfront. You'll end up needing more. I learned this the hard way when a single life insurance company required three separate certified copies and we'd only ordered one extra at the time. Emotional support resources exist but they're not part of the logistical checklist. Grief counseling, support groups, bereavement leave policies at work. These matter but they're separate from the actual procedural work of handling a death. Most people figure out the paperwork stress first and think about the emotional piece later when they're already exhausted from everything else.
Get the Full Details