The Saudi Economy Is More Complicated Than Oil
Most people hear Saudi Arabia and immediately think oil. That's not wrong, but it's also not the whole picture. The country runs a hybrid system that's officially called a mixed economy, though calling it that feels like understating the situation the way you'd call a wildfire "warm." It's a rentier state at its core, meaning government revenue comes primarily from external rents rather than domestic taxation, and that shapes everything about how the economy actually functions day to day. The technical answer is a state-directed mixed economy with strong elements of a rentier model. The government controls the majority of productive capacity through state-owned enterprises, most notably Aramco, which alone accounts for roughly 85% of export revenues and about 40% of GDP at its peak. Private sector participation exists but operates within a framework where regulatory direction from the state is essentially mandatory rather than optional. The currency is pegged to the US dollar at 3.75 riyals per dollar, which means monetary policy is effectively outsourced to the Federal Reserve. When I was working on a cross-border trade compliance project a few years back, I ran into a specific problem with Saudi import licensing under this system. The Saudi Standards, Metrology and Quality Organization (SASO) requires product certification through their SABER platform before goods can clear customs, and the rules change frequently without much advance notice. For a particular shipment of industrial equipment, the required standards documentation had been updated mid-process. The workaround was straightforward but expensive: we had to pull the shipment, get a new conformity certificate through an authorized certification body, and pay the associated fees before resubmitting. This added roughly 10 days and about $4,200 in costs. The broader issue is that the SABER system itself has had uptime problems, and during outages you can't submit anything, which creates bottlenecks that have nothing to do with your actual readiness to comply.
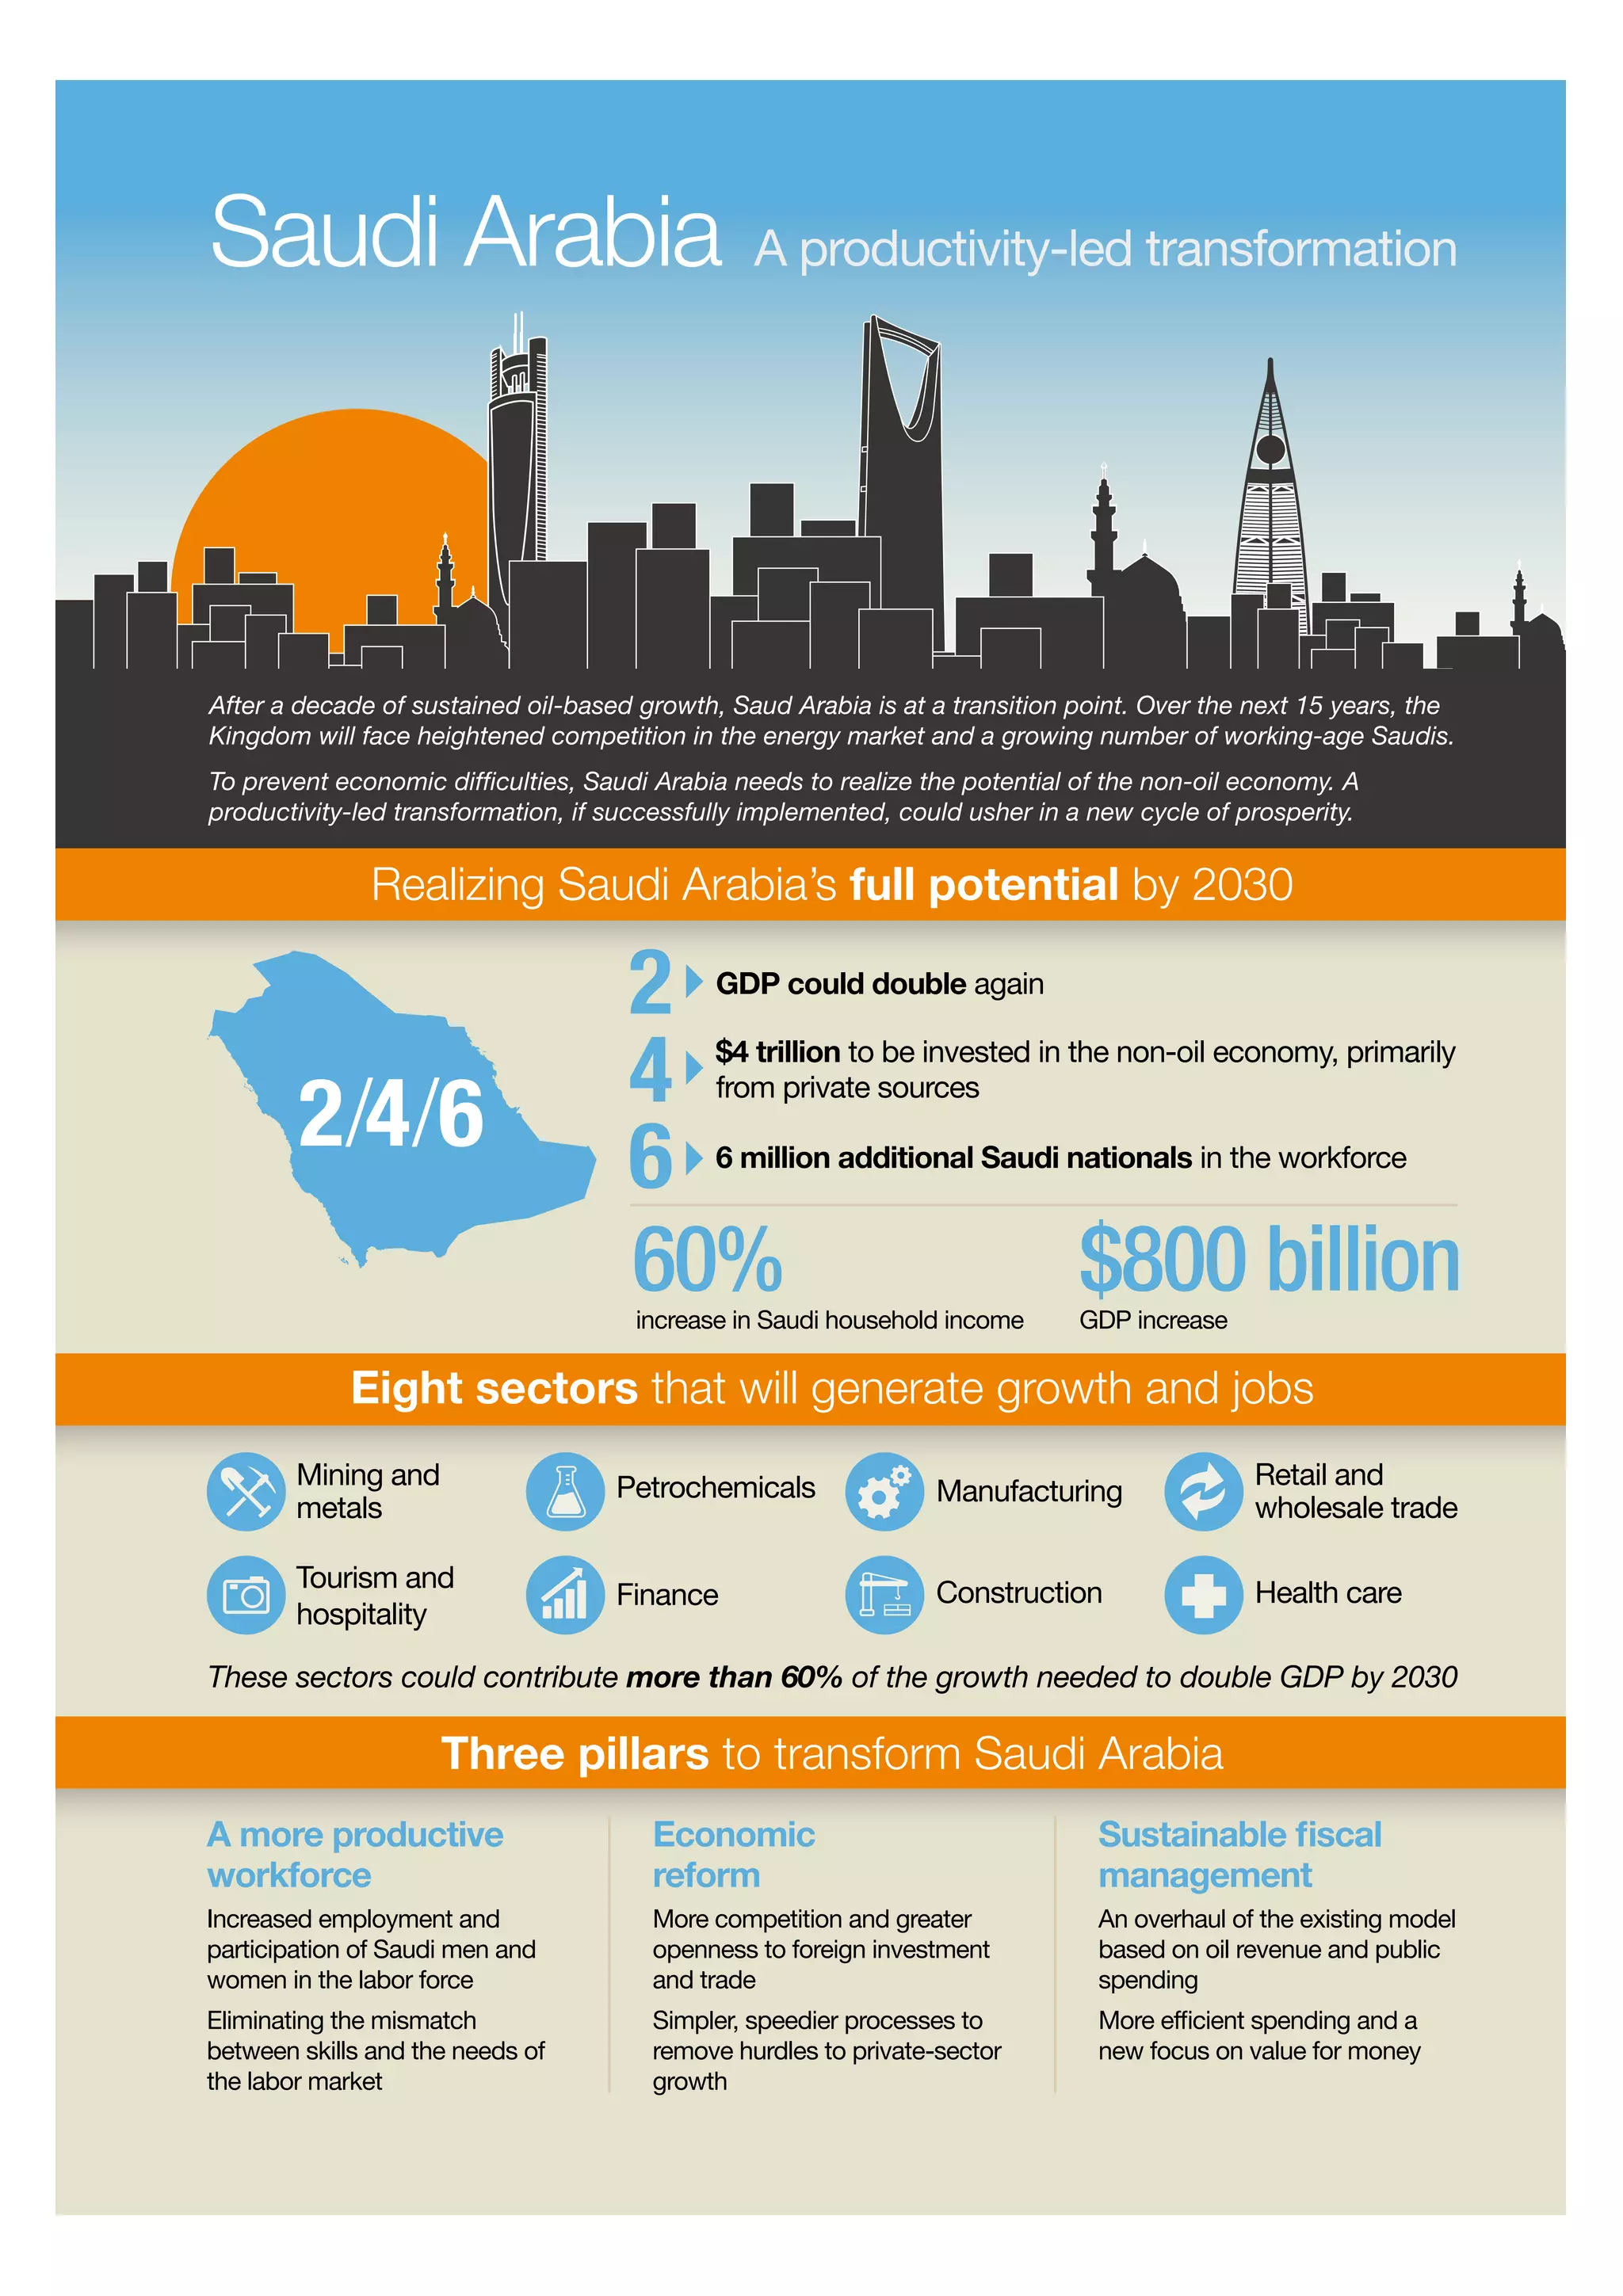
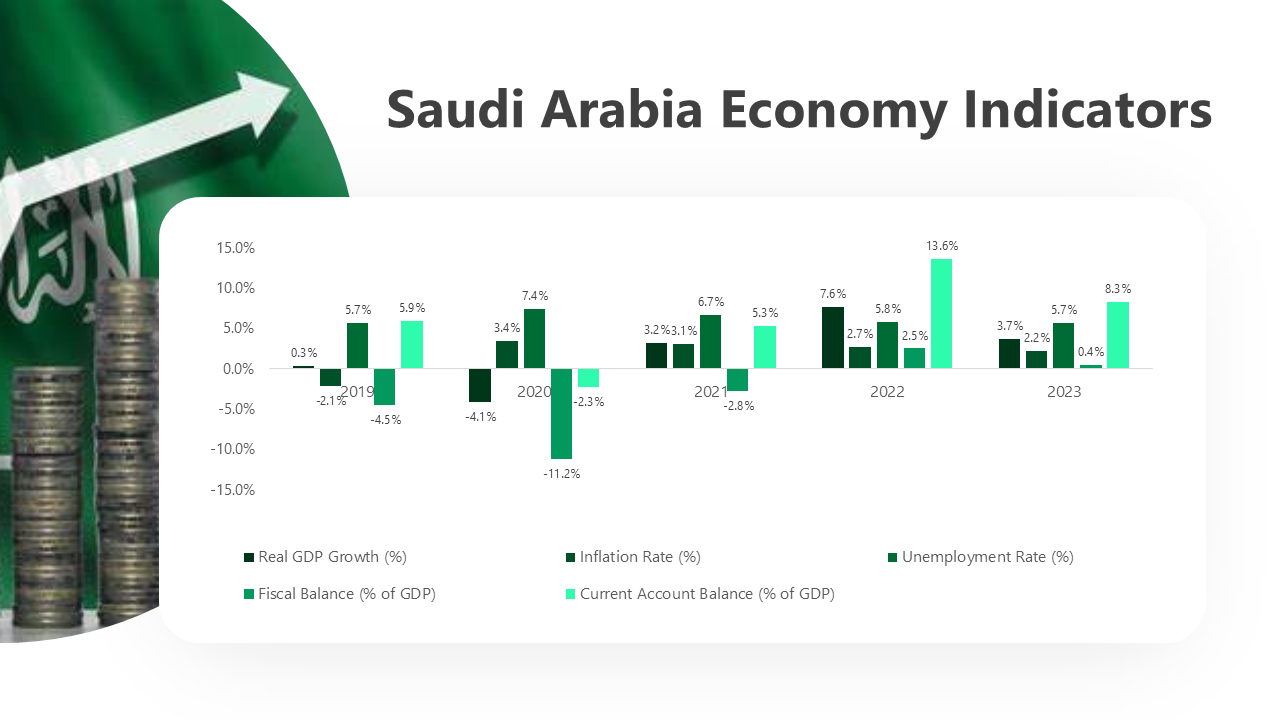
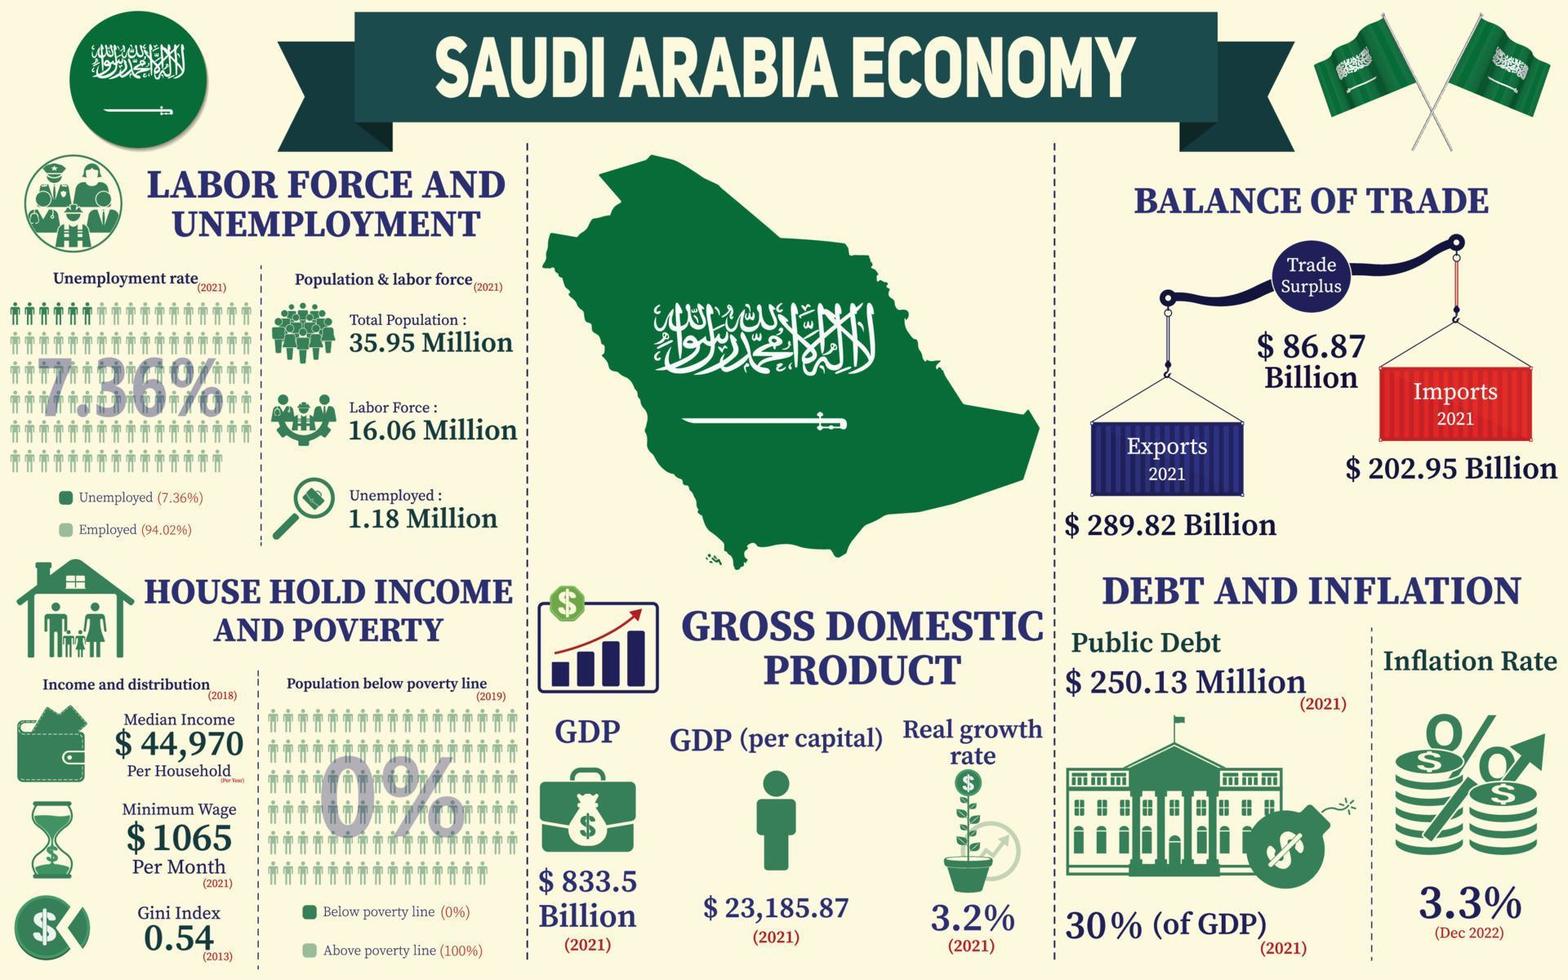
The structural reality is that Saudi Arabia's economy operates on what economists call a Dutch disease pattern. Oil revenues strengthen the currency and make non-oil exports uncompetitive, which disincentivizes diversification even when the government explicitly wants it. Vision 2030, launched in 2016, was an attempt to break that pattern through massive sovereign spending on projects like NEOM, the Red Sea development, and Qiddiya. The problem with that approach is that it substitutes one form of state dependency for another. You're no longer dependent solely on oil exports, but you become dependent on oil prices funding mega-projects that need to generate returns on timelines that don't match typical infrastructure returns. Another thing beginners miss about this system is the role of wasta, or connections, in economic activity. The official rules look reasonable on paper. The Private Investments Law was updated in 2022 to guarantee equal treatment for foreign and domestic investors, establish a single window for licensing, and protect against expropriation. The Legal Framework for startups provides additional scaffolding. In practice, these protections matter less than informal networks do. A foreign company might have every document in order and still face delays that a locally partnered competitor doesn't experience, not because of any written regulation but because the decision-makers operate through relationship-based channels that aren't documented anywhere. The tax system reflects the rentier nature of the state. There's no personal income tax for Saudi citizens, which is remarkable for a country of 36 million people. Corporate tax exists at 20% for foreign-owned companies, but there's also a Zakat rate of 2.5% on 40% of equity for Saudi and Gulf-owned businesses, which effectively comes out to 10% on total equity, though the calculation method differs. The VAT introduced in 2018 sits at 15%, which is among the highest in the Gulf Cooperation Council. The government has been gradually introducing taxation precisely because the rentier model is becoming unsustainable given population growth and spending obligations.
The labor market tells another part of the story. Saudization, or Nitaqat, mandates minimum percentages of Saudi nationals that companies must employ in various sectors. This isn't just policy rhetoric. The enforcement has real teeth. Companies face restrictions on government contracts, visa processing for expatriate staff, and other operational permissions based on their compliance status. The system has succeeded in increasing Saudi employment in the public sector and some private sectors, but it's created a dual labor market where Saudi nationals disproportionately occupy higher-paying government and quasi-government positions while the private sector remains heavily reliant on expatriate labor for routine operations. This creates a structural mismatch that no amount of vocational training programs has resolved yet. If you're looking at this from an investment perspective, the main risk isn't volatility in the traditional sense. The currency peg stabilizes exchange rate risk, and the government has enormous sovereign wealth through the Public Investment Fund, which manages assets estimated at over $700 billion. The real risk is policy unpredictability. Decisions can shift quickly based on leadership priorities rather than institutional processes. I've seen business plans that were solid on paper become obsolete overnight when a regulatory directive changed without consultation period. The workaround, honestly, is to build relationships with local partners who have institutional knowledge of how decisions are actually made and to structure agreements with explicit change-of-law clauses that account for regulatory shifts. The banking sector is predominantly Islamic finance compliant, though conventional banking exists alongside it. The Saudi Arabian Monetary Authority (SAMA) regulates everything, and the capital requirements are relatively stringent compared to some regional peers. Non-performing loans have been kept low through active oversight, but this also means credit access for smaller enterprises is tighter than you'd expect from a country with this level of wealth.
Get the Full Details
So the bottom line is that Saudi Arabia has a mixed economy in structure but a rentier economy in function, and understanding the difference matters more than the textbook classification. The system is transitioning, slowly, toward something more diversified, but the transition itself is funded by the old model, which creates a circular dependency that hasn't been resolved yet.