The Voluntaryism Problem
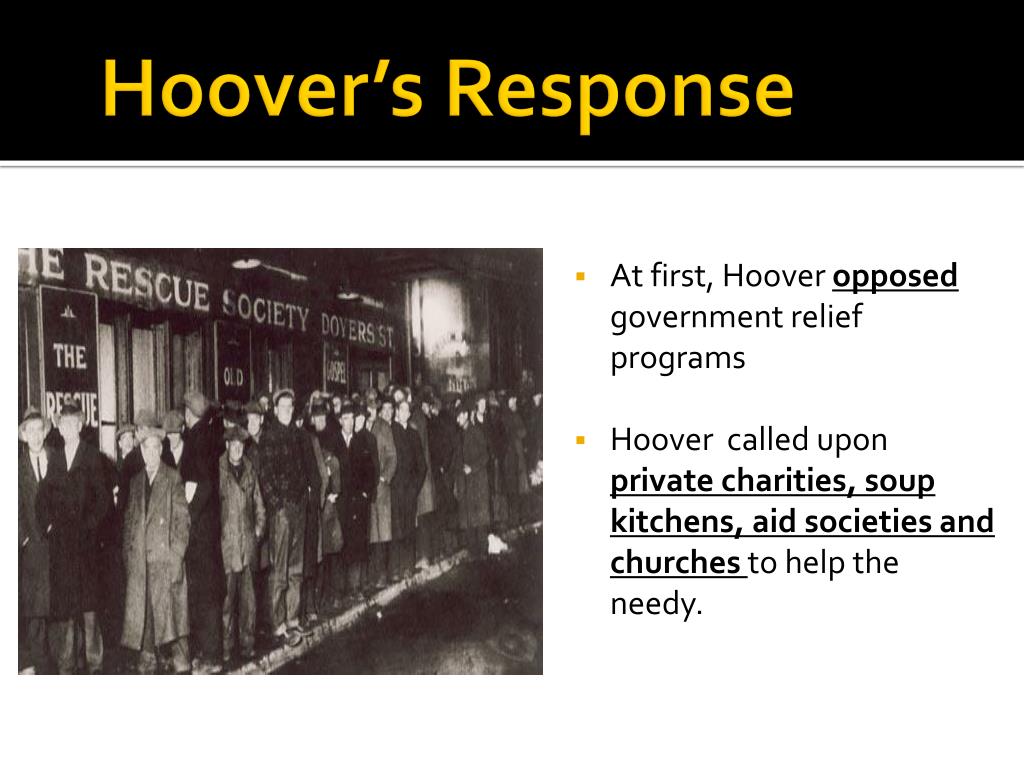
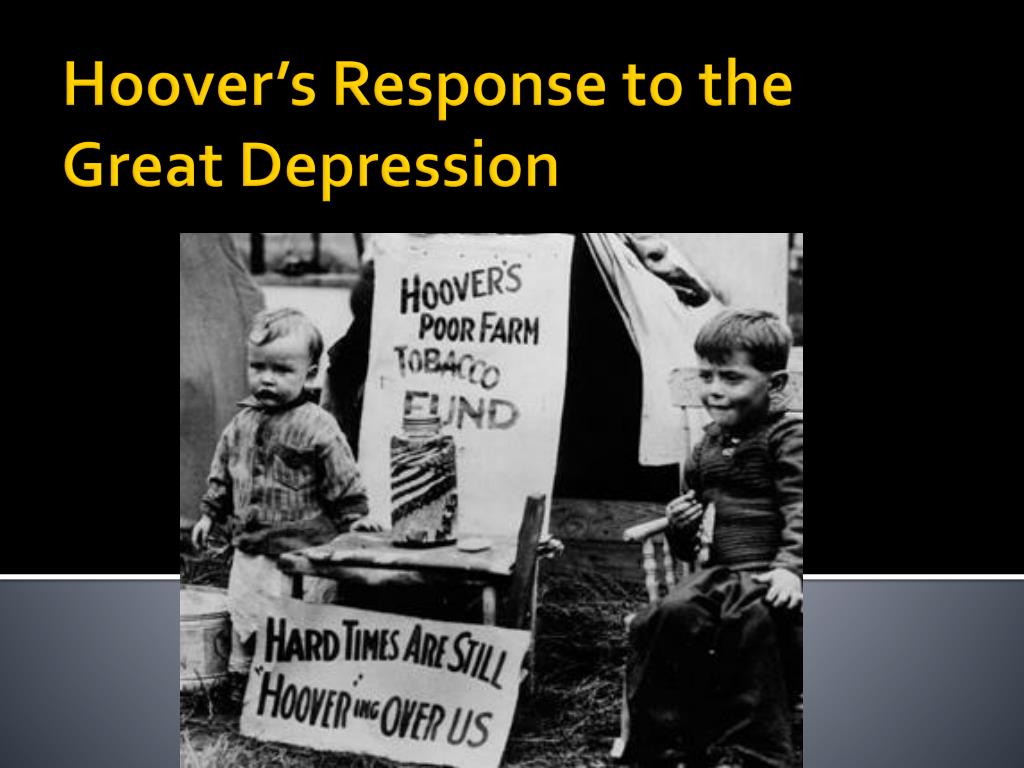
Herbert Hoover's response to the Great Depression is one of those topics where people immediately jump to "he did nothing," and that's wrong. He did a lot of things. Most of them failed, but saying he did nothing is just lazy shorthand that doesn't help you understand what actually happened or why it mattered. The core of his approach was something called voluntarism. Hoover believed the federal government should encourage and coordinate action but not directly intervene in the economy. He called it "rugged individualism." He spent 1929 and most of 1930 holding conferences with business leaders, trying to get them to agree not to cut wages or lay off workers. They agreed. Then they broke those agreements within months. The whole system collapsed because voluntary compacts don't hold when survival is on the line. His signature legislative act was the Smoot-Hawley Tariff, which he signed in June 1930 despite privately knowing it was a bad idea. He thought it would protect American farmers and workers from foreign competition. It raised duties on over 20,000 imported goods to historically high levels. Other countries retaliated immediately. U.S. imports and exports both collapsed by roughly two-thirds between 1929 and 1933. That made the depression deeper and longer than it needed to be. Economists still cite this as one of the worst trade policy decisions in modern history. He also signed the Revenue Act of 1932, which raised taxes across the board at a time when the economy was actively contracting. This is the part that still trips people up. Hoover was obsessed with balancing the federal budget. When tax revenues fell during the depression, his instinct was to raise rates, not to run a deficit. The tax increases pulled more money out of an economy that had almost no money left. It was pro-cyclical fiscal policy, which is the technical term for making a downturn worse instead of better. Most modern economists would consider that a basic error. Hoover knew it was risky. He also thought it was necessary to maintain confidence in the government's fiscal discipline. Confidence turned out not to be enough.
The Reconstruction Finance Corporation, created in 1932, was probably his most significant structural response. The RFC was a federal lending agency. It could lend up to $2 billion to banks, railroads, insurance companies, and other financial institutions. The idea was that if you bailed out the big institutions, the credit system would stabilize and the economy would follow. It was a trickle-down mechanism before the term existed. The RFC did lend money, and it prevented some bank failures that otherwise would have happened. But it was deliberately constrained. It couldn't give direct relief to individuals. It couldn't fund public works on a large scale. It was designed to prop up the financial system, not the people inside it. That design choice mattered enormously. By the time FDR expanded the RFC's powers in 1933, it had already been operating for over a year with its hands tied behind its back.
The Federal Farm Board and the Price Collapse
Before the RFC, Hoover created the Federal Farm Board in 1929. Its job was to stabilize agricultural prices, which had been falling since the mid-1920s. The board tried to buy up surplus crops and livestock to support prices. It didn't work. Farmers kept producing more because they needed the volume to cover their costs even as prices dropped. The board's purchases couldn't keep up with the surplus. Agricultural prices continued to fall. This was an early signal that market interventions without structural controls on production were going to fail at scale. I worked on a research project a few years ago where we were analyzing county-level data on bank failures and RFC lending patterns in the Midwest. One thing I found that surprised me was how uneven the RFC's impact was. Some counties got loans and stabilized. Others got nothing because the institutions they were connected to were already insolvent, and the RFC wouldn't lend to insolvent entities. This created a geographic pattern of recovery that had nothing to do with local conditions and everything to do with whether a regional bank happened to have enough collateral. People in the right counties with the right institutions felt relief. People elsewhere felt abandoned. That distributional asymmetry is something you don't see in textbook summaries, but it shaped the political landscape that followed. Voters in the affected counties tended to blame Hoover personally, even though the RFC was doing exactly what it was designed to do. Design matters more than intent in these situations.
Get the Full Details
The Bonus Army and the Breaking Point
The Bonus Army incident in the summer of 1932 was a turning point, not because of what Hoover did but because of how he responded. World War I veterans had marched on Washington demanding early payment of a bonus that had been legislated for 1945. They set up camps and stayed for months. Hoover offered them some modest relief and told them to disperse. When they refused, he ordered the army to clear the camps. General Douglas MacArthur led troops with tanks and cavalry into the protest encampment. Veterans were burned out, injured, and displaced. The images and stories spread quickly. Public opinion turned sharply against Hoover. This wasn't a policy failure in the traditional sense. It was a judgment failure. The decision to use military force against American citizens crossed a line that most people didn't recover from. Hoover's fundamental problem wasn't that he lacked information. He had access to the same economic data as anyone. His problem was that his philosophical framework prevented him from acting in ways that might have helped. He believed in balanced budgets, voluntary cooperation, limited federal power, and the moral hazard of direct government relief. These weren't empty slogans. They were deeply held convictions shaped by his upbringing as a Quaker and his experience running humanitarian relief operations during World War I. Those operations had worked. The question was whether the same approach scaled to a national economic collapse. It didn't. The scale was different. The nature of the crisis was different. Voluntary coordination breaks down when everyone is trying to survive alone. There's a common misconception that Hoover simply refused to do anything. That's not accurate. Government spending actually increased during his term. The federal budget grew from about $3 billion to $5 billion. But that increase came mostly from the RFC and emergency programs, and it was offset by collapsing revenues and tax increases that pulled money out of the private sector. The net effect was still contractionary. Hoover's budget balancing obsession meant that every dollar the government took in through higher taxes was a dollar that couldn't circulate in the economy. This is the same dynamic that Keynes would later formalize, but the framework didn't exist in mainstream policy circles when Hoover was making these decisions.
Why This Still Matters
Hoover's response to the depression established patterns that repeated in 2008 and in other crises since. The initial instinct to rely on private institutions, to avoid direct relief, to fear the moral hazard of government intervention, to prioritize balance sheets over human outcomes. Each time, the pattern plays out similarly. Interventions come too late, are too constrained, and are directed at the wrong parts of the system. Hoover's specific mistake was believing that the financial system could be stabilized without also addressing the demand collapse on the ground. You can lend to banks all day. If nobody has income to spend, the loans don't circulate. They sit in reserves or get used to pay off old debts. That's not a new insight. It's just one that politicians keep having to relearn. Hoover lost the 1932 election to Franklin Roosevelt in a landslide. The electoral mandate shifted decisively toward active federal intervention. The New Deal programs that followed were in many ways reactions against Hoover's approach, even though some of them, like the RFC expansion, built directly on his institutional innovations. Understanding Hoover's response isn't about assigning blame. It's about understanding the constraints that shaped policy choices and the consequences of those constraints. The ideas that seemed reasonable in 1930 proved inadequate in practice. That gap between theory and outcome is where most economic policy failures happen.