Why Economists Still Avoid Pinning Down the Term
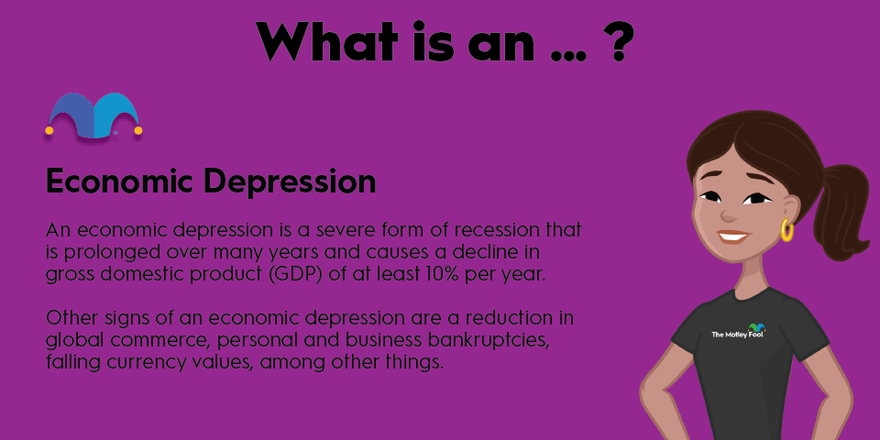
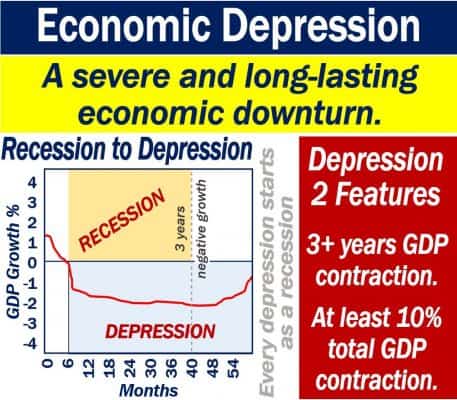
The term "depression" shows up in textbooks and news headlines, but the reality of defining it is messier than most people realize. I spent years working in macroeconomic forecasting before moving into policy advisory roles, and one thing became clear early on: there is no universally accepted threshold for what qualifies as a depression. That creates real problems when you're trying to classify events, compare them across decades, or communicate with policymakers who want a clean answer. The standard working definition you will find in most economics references is a severe downturn lasting at least two years with a decline in GDP exceeding 10 percent. This came largely from the work of economists who tried to impose structure on an imprecise concept. Milton Friedman and Anna Schwartz briefly touched on it in their Great Depression research, but they never proposed a formal numerical boundary. Later economists like Barry Eichengreen have written extensively about the term without ever codifying it.
Whats The Definition Of An Economic Depression
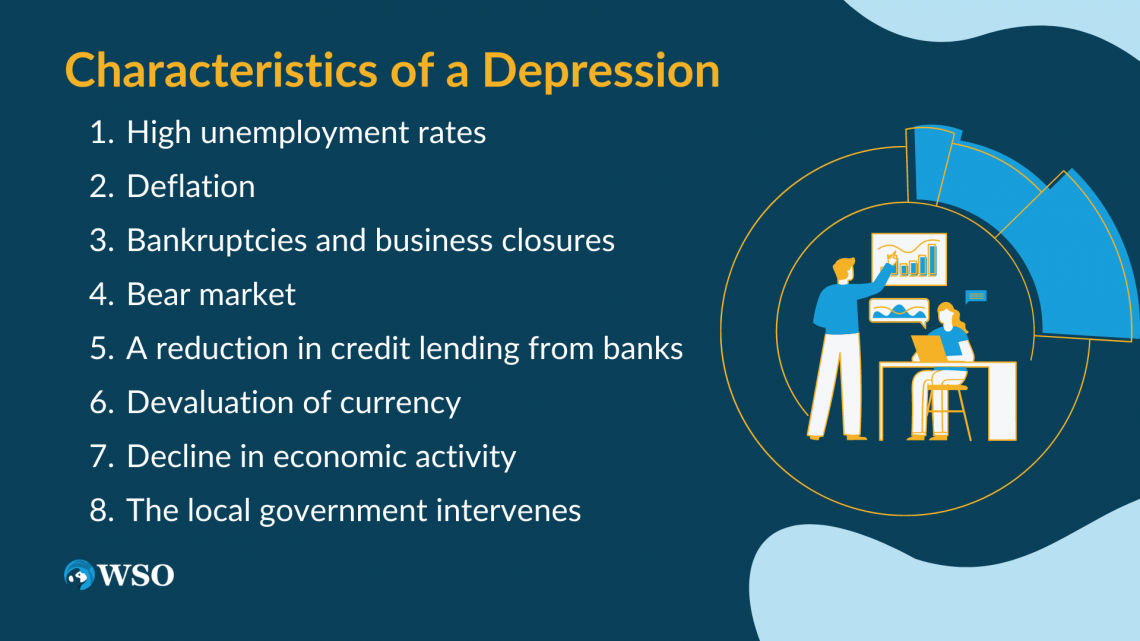
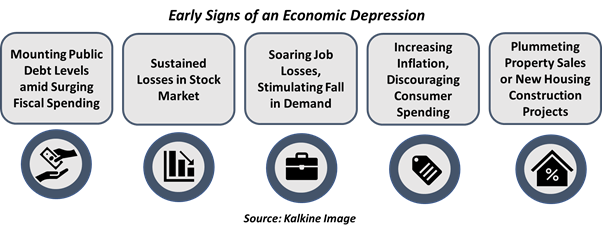
There is no formal definition established by any government or international organization. The IMF, the World Bank, and national statistical agencies do not publish criteria for labeling an episode a depression. When you look at what economists actually use in practice, it comes down to a rough cluster of characteristics rather than a checklist. A depression involves a collapse in output far deeper than a normal recession, sustained and elevated unemployment, widespread business failures, and financial system disruption. The Great Depression of the 1930s remains the reference point that everything else gets compared against. I ran into a specific problem once while building a dataset of economic contractions spanning 1950 to 2020. A researcher from a university in Southeast Asia sent me a spreadsheet arguing that Indonesia's 1998 downturn should be classified as a depression. The GDP drop was steep, the banking system collapsed, and unemployment spiked. But by the commonly cited 10 percent threshold, it missed by a small margin depending on which quarter you measured from. I spent about three weeks recalibrating the data, checking for base effects, and running alternative definitions before we settled on describing it as a severe crisis with depression-like characteristics rather than labeling it cleanly. The workaround was to use a composite indicator combining output decline, unemployment duration, and financial sector stress rather than relying on a single GDP number. That approach gave us a more accurate picture and revealed that several other countries in the region had episodes that would qualify under a broader framework but not under the narrow threshold.
What Makes a Depression Different From a Recession
The distinction matters because the policy responses are fundamentally different. Recessions are managed with interest rate adjustments and fiscal stimulus. Depressions often require structural reforms, banking system recapitalization, and sometimes international intervention. The difference is not just severity. It is about duration, the breakdown of normal economic mechanisms, and the difficulty of returning to previous trends. Duration is the primary differentiator. A recession typically lasts several months to a couple of years. A depression persists for multiple years, often with periods of marginal recovery that stall out. The Great Depression lasted roughly a decade in the United States before World War II spending revived the economy. Even after the worst period ended, the unemployment rate did not return to normal levels until the late 1930s. Financial system damage separates the two categories. Recessions may involve tight credit conditions, but depressions often feature bank failures, currency crises, or sovereign debt defaults. The structural damage to the financial sector means recovery is slower and more complicated. When banks fail in large numbers, the credit channel breaks down completely, and monetary policy becomes less effective because there is no healthy banking system to transmit stimulus.
Get the Full Details

The Counter-Intuitive Part Most People Miss
Here is something that does not get enough attention: an economy can experience a depression-level contraction and still not be officially classified as such by statisticians. This happens because GDP measurements have limitations that become especially visible during severe downturns. Price deflation, changes in the quality of goods produced, and shifts in informal economic activity can distort the numbers. I encountered this directly when analyzing deflationary periods. Falling prices can make nominal GDP drops look worse than real output drops, or the reverse, depending on which price index you use. The choice of deflator can swing a classification by several percentage points, which is the difference between calling something a severe recession and a depression. Another thing beginners miss is that not all deep contractions are caused by the same mechanisms. Some depressions are demand-driven, like the 1930s. Others are supply-driven or structural, like post-Soviet transitions. The 1990s in several Eastern European countries saw output decline for five or six years straight, but calling it a depression using Western metrics is misleading because the structural transformation involved dismantling an entire economic system. The numbers looked like a depression, but the dynamics were different. Understanding the underlying cause changes how you interpret the data and what policy lessons you draw from it.
How Analysts Actually Approach This Today
Most modern analysts do not try to define a depression with a single threshold. Instead, they use frameworks that capture severity across multiple dimensions. The World Economics Association maintains a list of depressions going back to the 19th century, and their methodology considers both the depth and duration of output declines. According to their list, only a handful of episodes since 1870 qualify, including the Great Depression, the Irish Depression of the 1980s, and the Russian depression of the 1990s. Their criteria are stricter than the casual 10 percent GDP decline rule, requiring prolonged and exceptionally deep contractions. The main limitation of any definition is that it is inherently arbitrary. Picking 10 percent or 15 percent as a cutoff is a political choice as much as an analytical one. Different thresholds produce different lists of depressions. If you lower the threshold, you include more countries and episodes but dilute the meaning of the term. If you raise it, you end up with an almost empty category that loses practical usefulness. There is no neutral position here. For practical purposes, I recommend focusing on what the term signals rather than treating it as a precise classification. When someone describes an economic situation as a depression, the useful information is about severity, duration, and systemic disruption. The exact label matters less than understanding the mechanisms at work and the policy implications. If you need a working definition for analysis, use a composite approach that combines output decline, unemployment persistence, and financial stress indicators. This gives you more reliable results than any single threshold.
The term "depression" survives because it communicates something important about extreme economic hardship that "severe recession" does not quite capture. Whether or not we can define it precisely, the underlying phenomenon is real and well-documented. The effort to define it rigorously is useful but ultimately constrained by the nature of economic data and the diversity of historical cases. That is where the concept stands today.