Why Accounting Journal
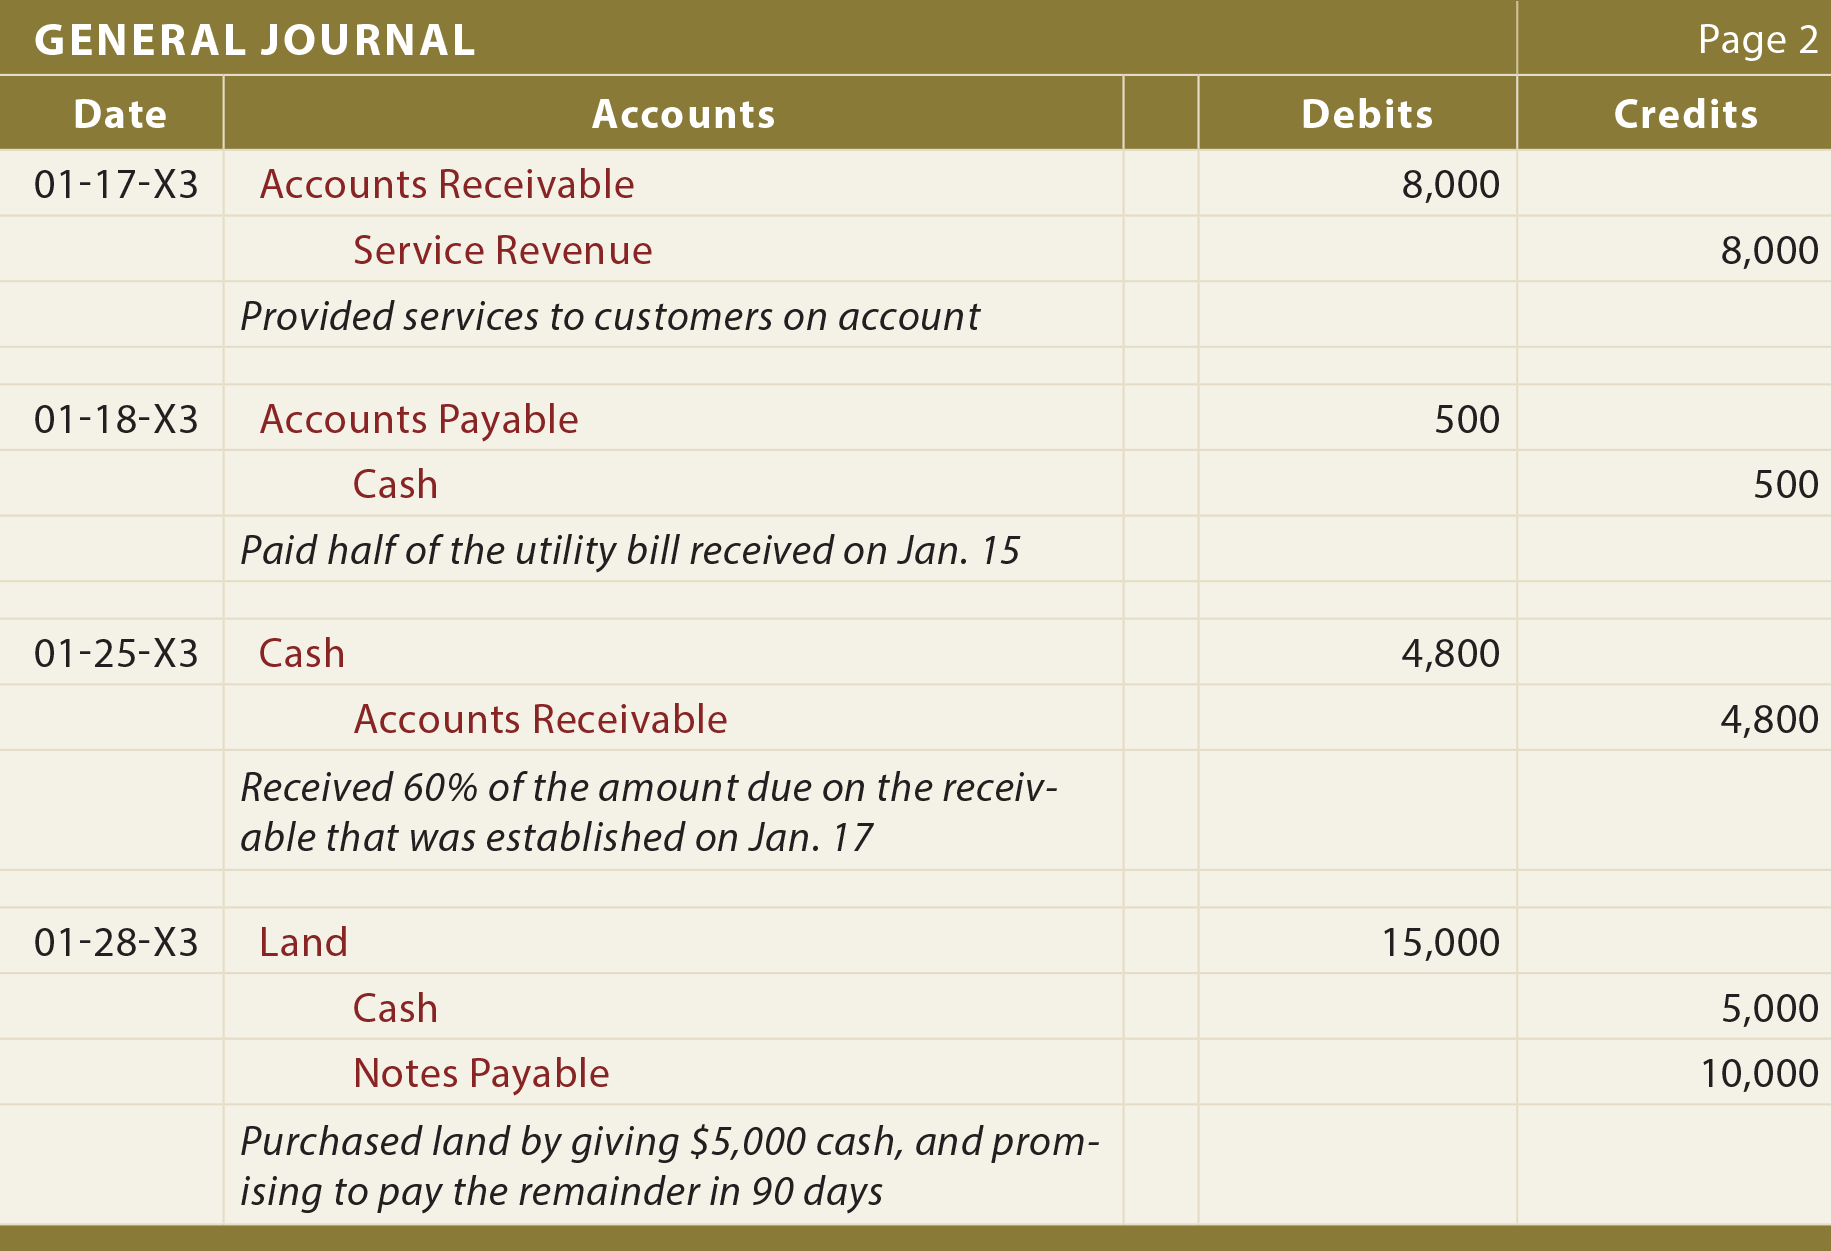
Accounting journals are where every transaction gets recorded before it ever touches the ledger. You write the entry, you credit something, you debit something else, and the whole system depends on those entries being clean. I stopped arguing about this years ago after watching a mid-size firm try to skip journal entries and just push everything through their bank reconciliation. Took them six months to find a $40,000 discrepancy and still didn't close it properly. The basic structure is straightforward. Debit on the left, credit on the right. Every entry has to balance. But the real reason people care about this topic is less about the mechanics and more about what happens when those mechanics fail under pressure.
Why Accounting Journal matters when things go sideways
I once dealt with a client who had been using spreadsheets instead of proper journal entries for about three years. When I asked to see their trial balance, it didn't tie to the general ledger. The problem was a series of adjusting entries that were recorded as memos rather than formal journal transactions. They weren't invisible to the software, but they were invisible to anyone trying to audit or review the books. The workaround was tedious. I rebuilt their chart of accounts to match what they were actually doing, then went back month by month and created correcting journal entries for each memo that should have been a real entry. It took about forty hours across two weeks. They could have saved most of it by just letting the software handle it properly from the start. This is the part nobody tells you: your accounting journal isn't just a record. It's a diagnostic tool. When your entries are granular and consistent, you can spot problems by looking at the journal itself. Misclassified expenses, duplicate payments, revenue recognition issues — they all show up as patterns in the data. Skip proper journal entries and you lose that visibility.
What people miss about journal entries
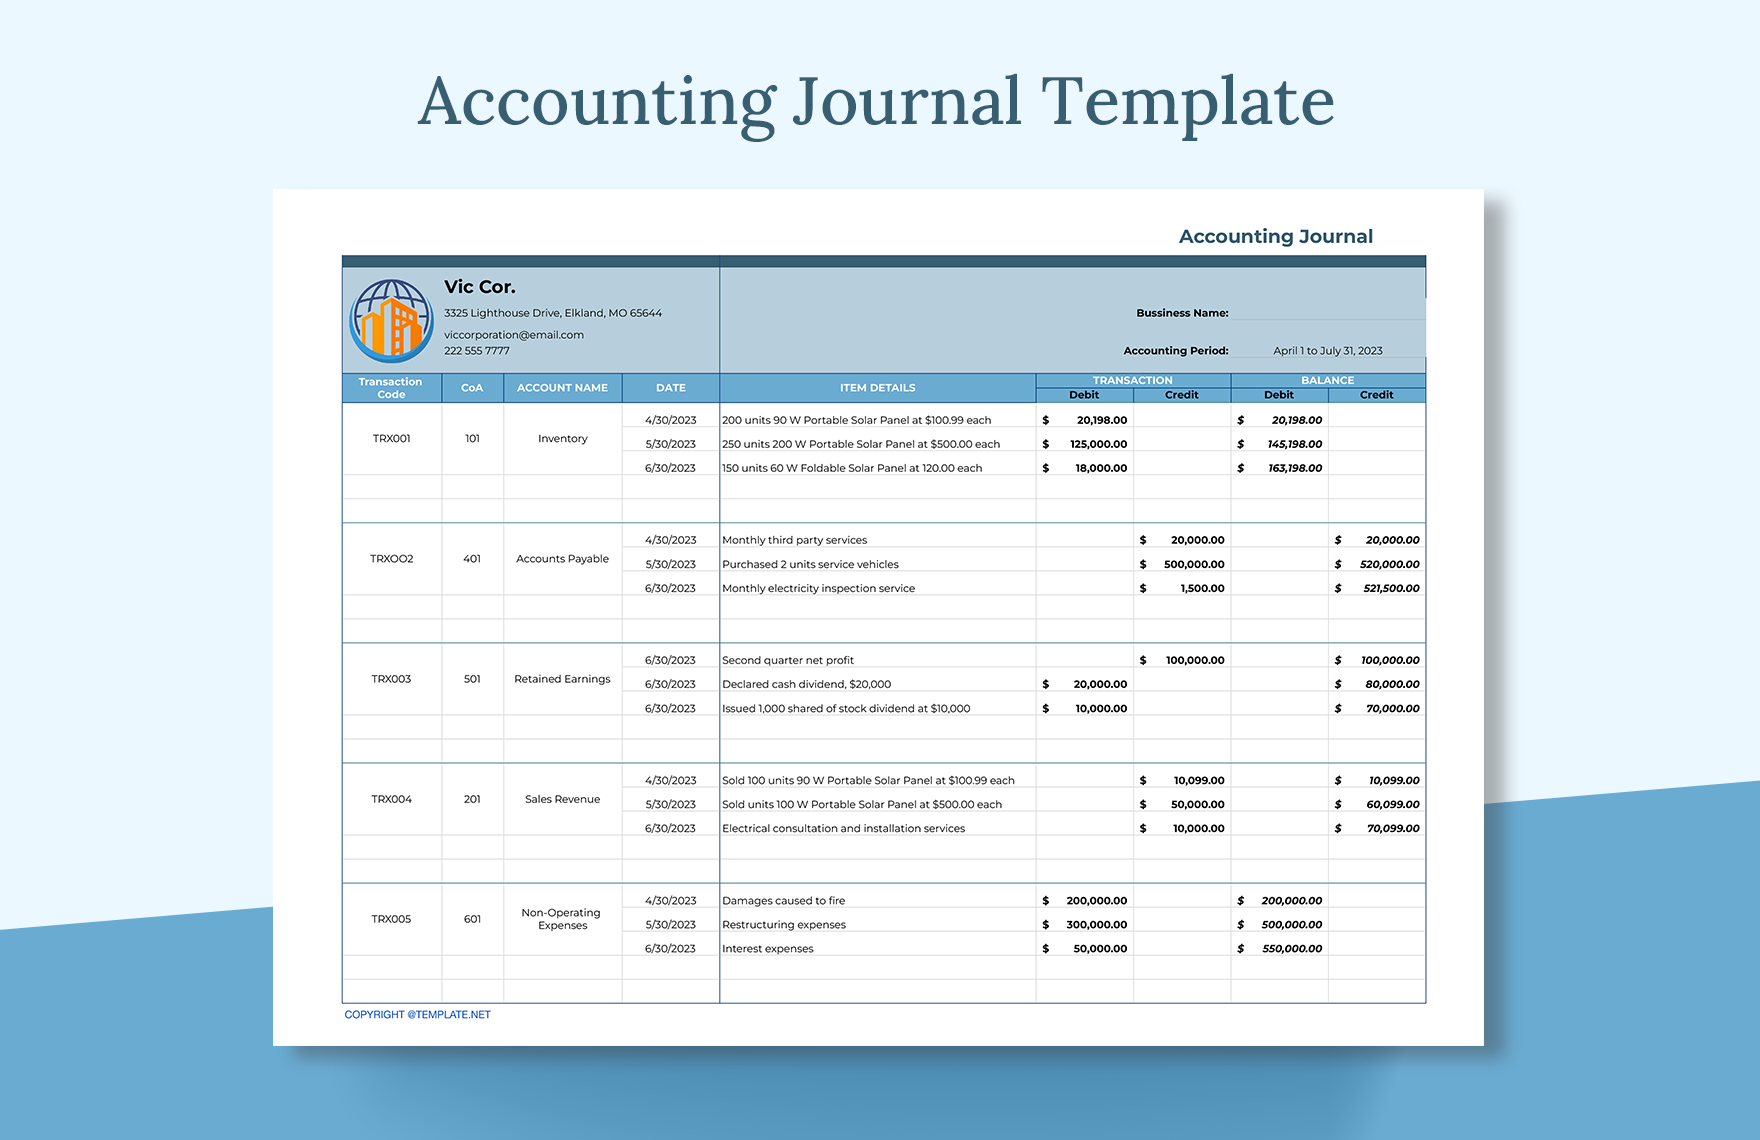
Most beginners focus on getting the debit and credit to balance, which is the bare minimum. The thing that separates decent bookwork from solid accounting is how you handle the reference information. Every journal entry should have a clear description, a supporting document reference, and the right account mapping. I've seen entries that just say "transfer" with no additional context, and finding the source of those becomes a nightmare during close. Another overlooked area is accruals. A lot of small business owners record expenses when they pay them instead of when they incur them. That works fine until you're trying to produce financial statements for a lender or investor. They want to see accrual-based figures, and if your journal doesn't reflect the actual timing of economic events, your statements will be wrong in ways that matter. The counter-intuitive part is that journal entries are harder to maintain than some alternatives, but they're also more defensible. Audit trails built from proper journal entries hold up much better than reconstructed summaries. I once had a tax auditor ask me to walk through every entry for a particular quarter. If we'd been using a simplified approach, I would have had nothing to show. Instead, the entries told the full story in about twenty minutes.
Get the Full Details

Practical workflow
Here's how I actually approach journal entries in a real setup. First, I make sure the chart of accounts is mapped correctly for the business. A mismatched account structure causes most of the problems downstream. Then I enter transactions as they happen, not in batches at the end of the month. Batch entering leads to errors because you lose the context of each individual transaction. For recurring entries like depreciation or prepaid expenses, I set up templates in the software rather than recreating them each period. This cuts the time spent on monthly close from around three hours down to about forty-five minutes for a small business with moderate activity. The one place this breaks down is in multi-entity structures. Consolidation entries need to be handled carefully, and journal entries across entities can create intercompany balancing problems. I usually recommend setting up separate but linked books for each entity and using a consolidation module rather than trying to manage everything through manual journal entries.
If you're working with something like QuickBooks, Xero, or NetSuite, the journal functionality is built in. You don't need a separate download or plugin. The software handles the validation automatically, which removes a lot of the risk. The main thing you control is discipline — making sure every transaction gets a proper entry instead of getting swept under the rug. I don't have a single file to hand you. This isn't something you can install. It's a process you build into your accounting routine, and it takes about two weeks of consistent effort to make it stick once you decide to do it right. After that, it's just part of how you work.