The Practical Walkthrough Most People Skip
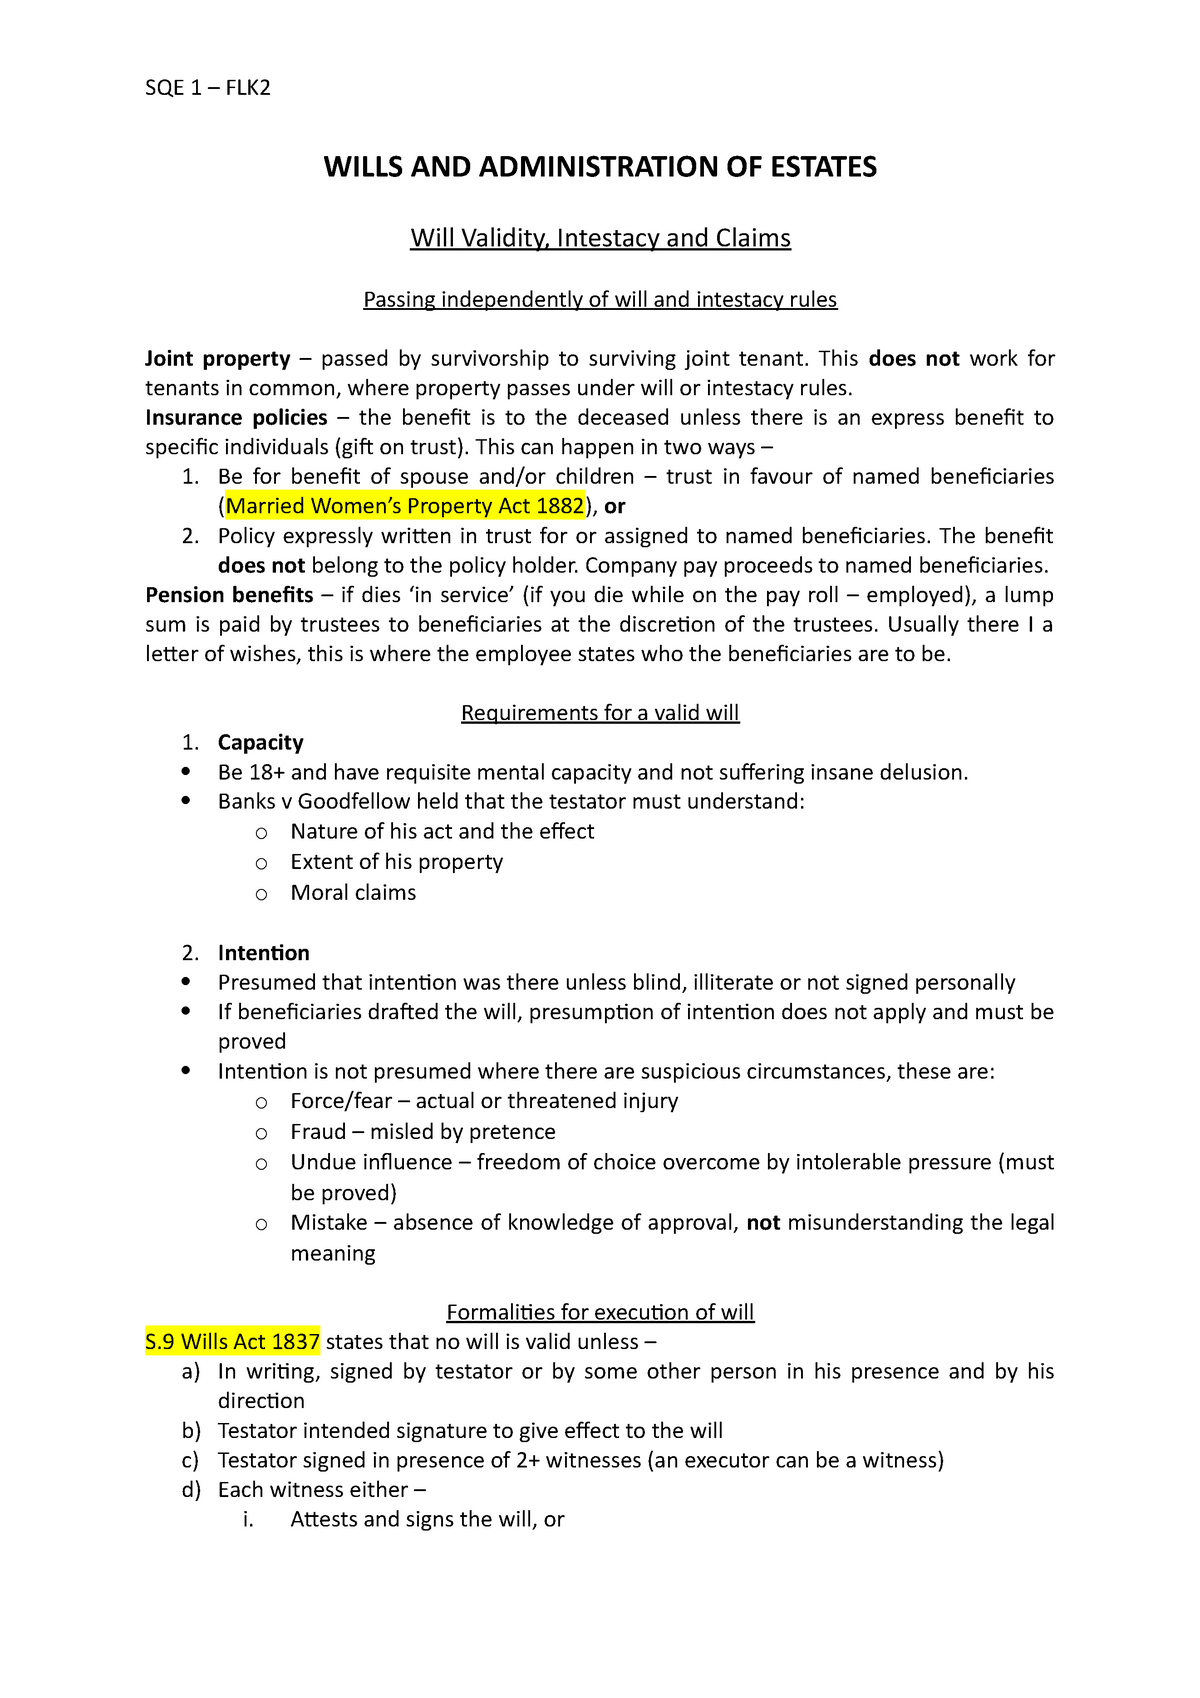
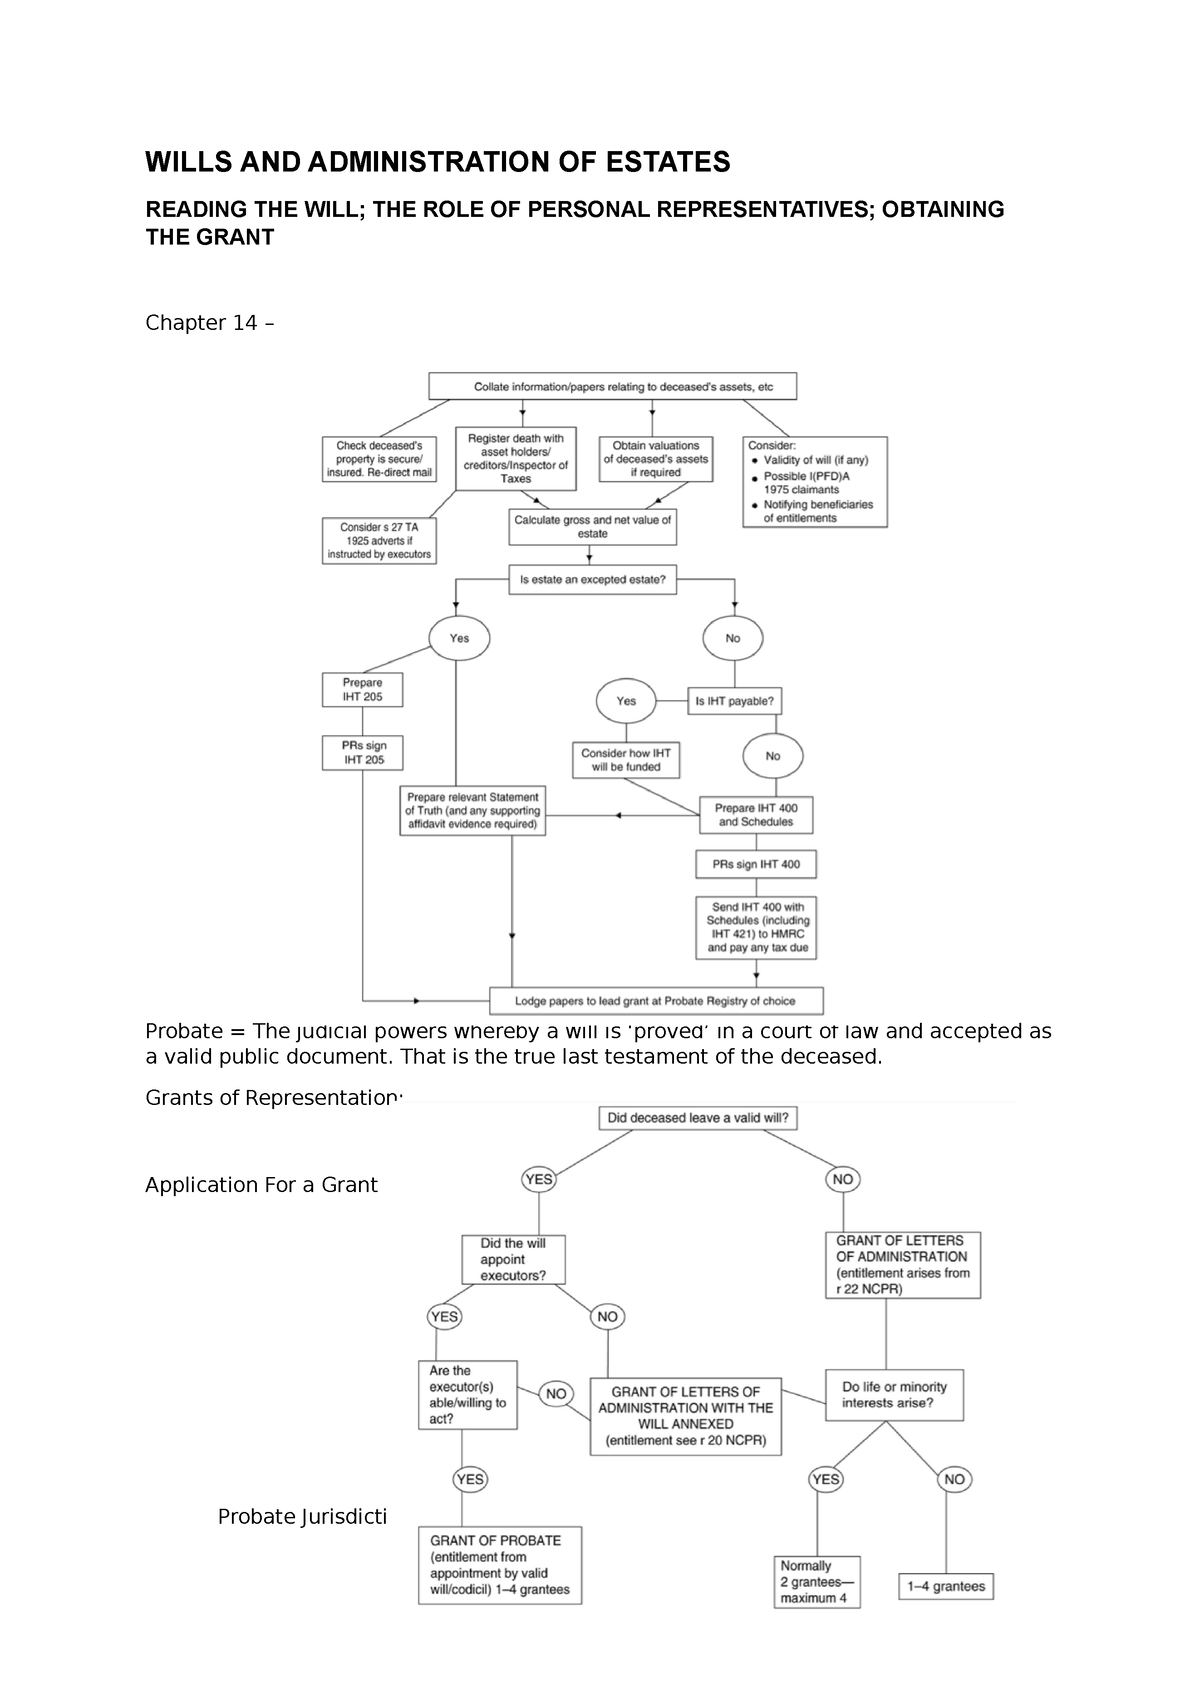
Most people treat probate as if it is a single step. It is not. It is a sequence of administrative tasks, each with its own deadlines, creditor notifications, and asset valuation requirements. If you are dealing with Wills And Administration Of Estates for the first time, the confusion usually comes from treating the whole process as one big problem instead of a series of small ones that stack up against you. In practice, administration begins the moment you decide whether a will exists. If there is a will, you are the executor named in it. If there is no will, the court appoints an administrator. The difference matters because the letters you receive from the probate registry carry different names and slightly different powers, even though the end result looks similar. A probate grant in England and Wales takes around six to eight weeks from application to receipt if everything is clean. It takes four to nine months if the estate includes foreign property, trusts with overlapping interests, or disputed valuations. That gap is where most people get stuck. I dealt with a case recently where a client submitted a standard IHT205 form on a £380,000 estate with a buy-to-let property. Everything looked straightforward. The estate office returned it asking for a full IHT account because the property had been owned for less than four years before death and they suspected a capital gains tax element from a prior period. The client had not kept records of the original purchase price properly. I had them trace the conveyancing files from the solicitor who handled the purchase fourteen years earlier, locate the original transfer deed, and reconstruct the base cost from the land registry copy. It added three weeks to the process but saved the entire submission from being rejected outright. That is the kind of thing that does not show up in any guide.
The counter-intuitive part most people miss is that ordering the grant first does not give you free access to every institution. Banks and building societies have their own internal probate thresholds. Halifax, for example, will accept a grant for estates over £50,000. NatWest requires it over £10,000. Some smaller lenders will release funds without any grant at all if the balance is under £5,000. You need to check each institution individually before you assume the grant solves everything. It does not. It is a key, not a master override.
Starting the Application
The first practical decision is whether you need a full grant or a grant of administration. If the will names you as executor and the will is valid, you apply for probate. If there is no will, you apply for letters of administration. The forms are different. The HP4 is for probate. The PA1P is for when there is a will and you need to appoint someone who was not named in it. The PA1A is for intestacy. Using the wrong form gets your application returned within days. I once saw a solicitor's office send a PA1P to a client with a clear will naming them executor and get it bounced back with a note that simply said "wrong form." That is a five-week delay on top of whatever else is happening. Before you fill anything out, gather the estate values. Not estimates. Actual values as at the date of death. Joint accounts should be split according to beneficial ownership, not just divided equally. A joint account with your partner where you contributed 80 percent of the deposits does not become a 50-50 split for probate purposes.HMRC expects the split to reflect the true beneficial interest. If you write 50-50 without the documentation to support it, you are creating a discrepancy that later triggers an enquiry. The inheritance tax calculation is where most first-time applicants make mistakes. The standard IHT nil-rate band is £325,000. The residence nil-rate band adds another £175,000 if you leave your home to direct descendants. That gives you a combined threshold of £500,000 for many people. Anything above that is taxed at 40 percent. But the estate can claim a 10 percent discount on the value of certain assets if they are quoted shares or interests in funds, which can shift a borderline estate from owing tax to owing none. Most people do not know this exists. It is buried in the IHT400 notes.
Get the Full Details
Notifying Creditors and Claimants
Once you have the grant, you publish a creditors notice in the London Gazette and a local newspaper. This protects you from unknown claims. The notice period is two months from publication. If a creditor comes forward after that window, you are generally safe. If they come before, you have to consider their claim before distributing anything. Skipping this step is one of the most common errors. I have seen executors distribute funds to beneficiaries and then get hit six months later by a credit card company claiming an unpaid balance on a deceased person's account. The executor becomes personally liable for the debt if they distributed before properly notifying creditors. For Wills And Administration Of Estates, this step is where the process slows down the most. Solicitors who handle these regularly will tell you that creditor notification accounts for roughly 30 to 40 percent of the total timeline in mid-complexity estates. It is not the paperwork. It is the waiting. Banks take two to four weeks to confirm balances. Pension providers can take longer if the pension fund is under a trust structure. You need to send formal written requests, not just call and ask. Verbal enquiries do not create a paper trail. If a dispute arises later, the paper trail is what protects you.
Distribution and Closing Out
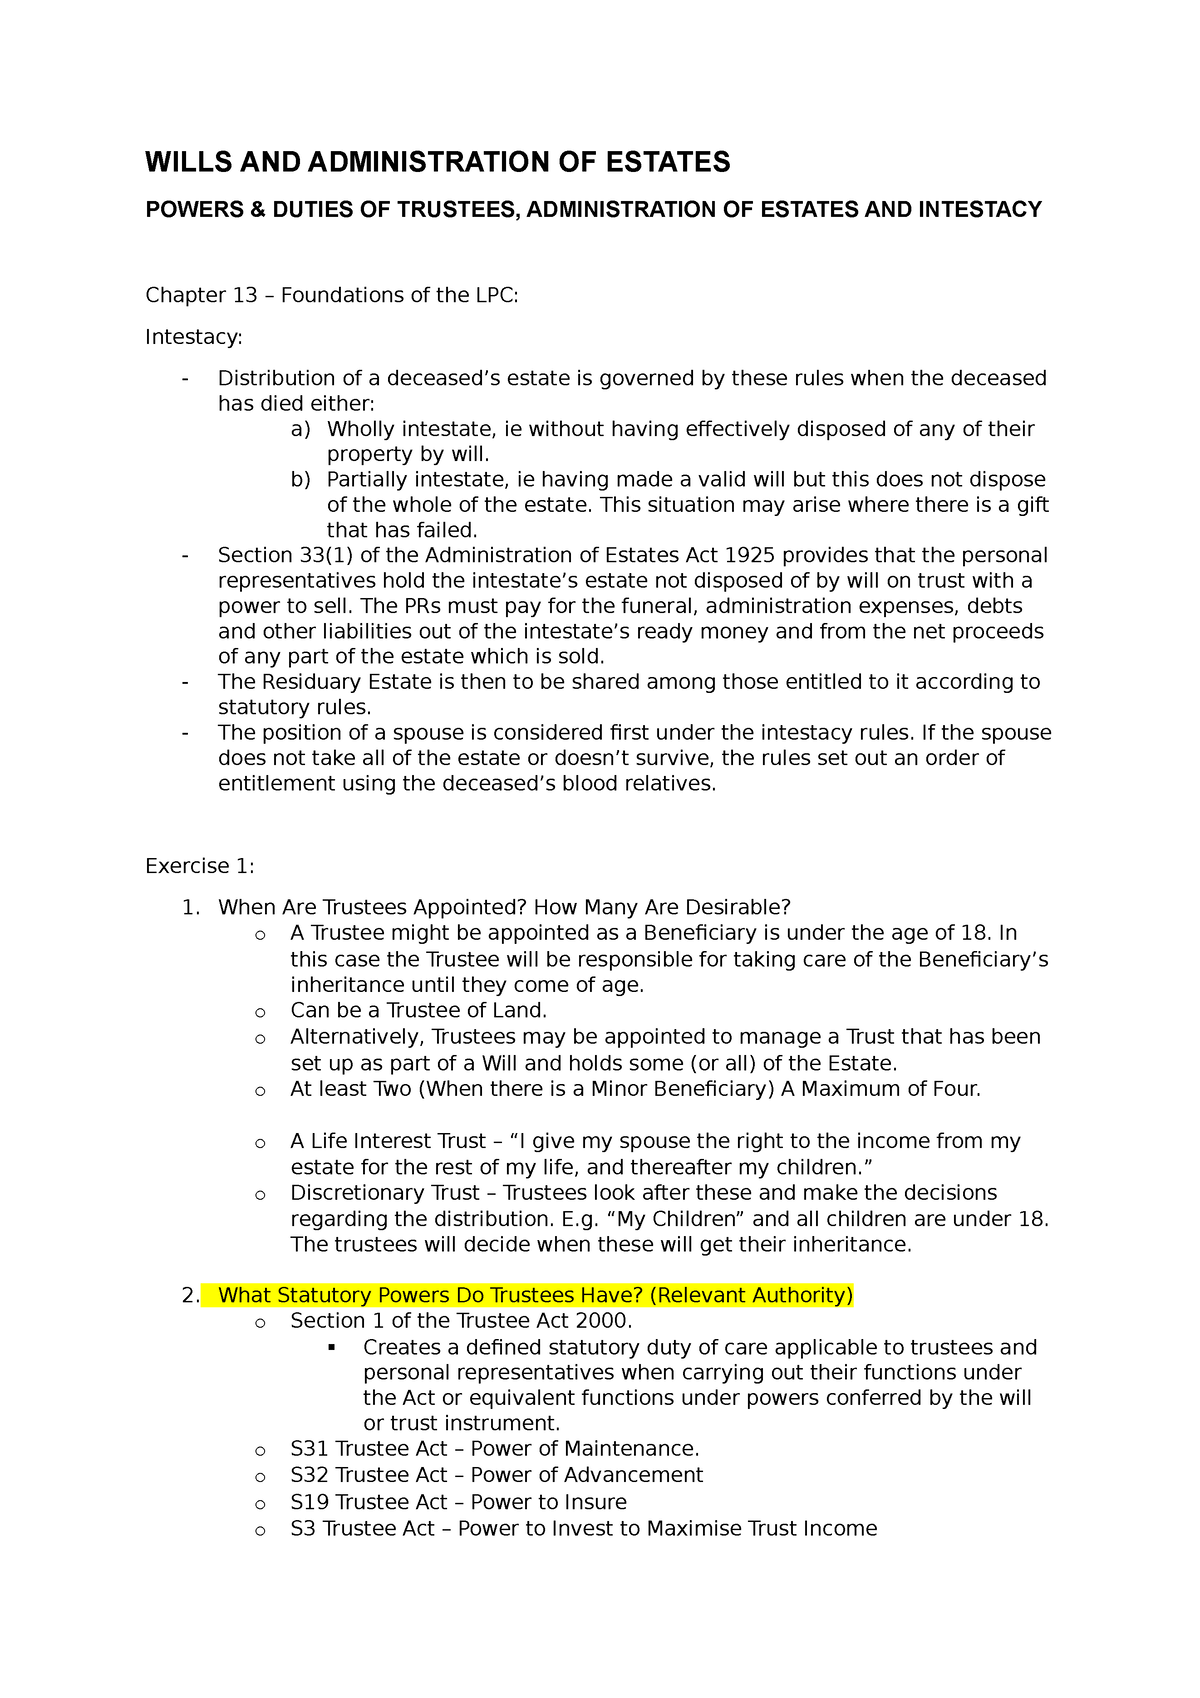
Distribution should follow the will exactly. If the will leaves a specific sum to a sibling and the residue to a partner, you pay the specific legacy first, then calculate the residue. You do not divide everything equally unless the will says to. Beneficiaries often assume equal division is the default. It is not. The will controls everything. If there is no will, intestacy rules apply, and those rules follow a strict hierarchy: spouse or civil partner first, then children, then parents, then siblings. It is rigid and does not account for modern family structures in every case. The final step is preparing the estate account for the beneficiaries. This should show every asset collected, every liability paid, and every distribution made. Keep receipts. Keep bank statements. Keep copies of all correspondence. An estate account that is unclear creates doubt, and doubt creates disputes. I handled an estate where the executor kept poor records and a beneficiary asked for a full audit of the administration. It took the executor another four months and roughly £2,800 in professional fees to reconstruct the account from bank statements alone. The alternative would have been to maintain proper records from day one. There are limits to what this process can handle smoothly. Complex trusts, contested wills, overseas assets, and estates with business interests often require specialist input that goes well beyond standard probate practice. In those cases, a standard DIY approach through the government portal will not work. You need a solicitor who specialises in contentious probate or a qualified trust and estate planner. The cost is higher, but it prevents errors that are far more expensive to fix later.
If you need the official forms, they are available directly from the UK government website. The probate application portal is free to use. The fee for a grant is £275 if the estate is over £5,000. There is no fee if the estate is under £5,000 and has no property. The portal walks you through each section, but it does not explain the edge cases. That is where experience matters.