Getting Your Work History Report Social Security
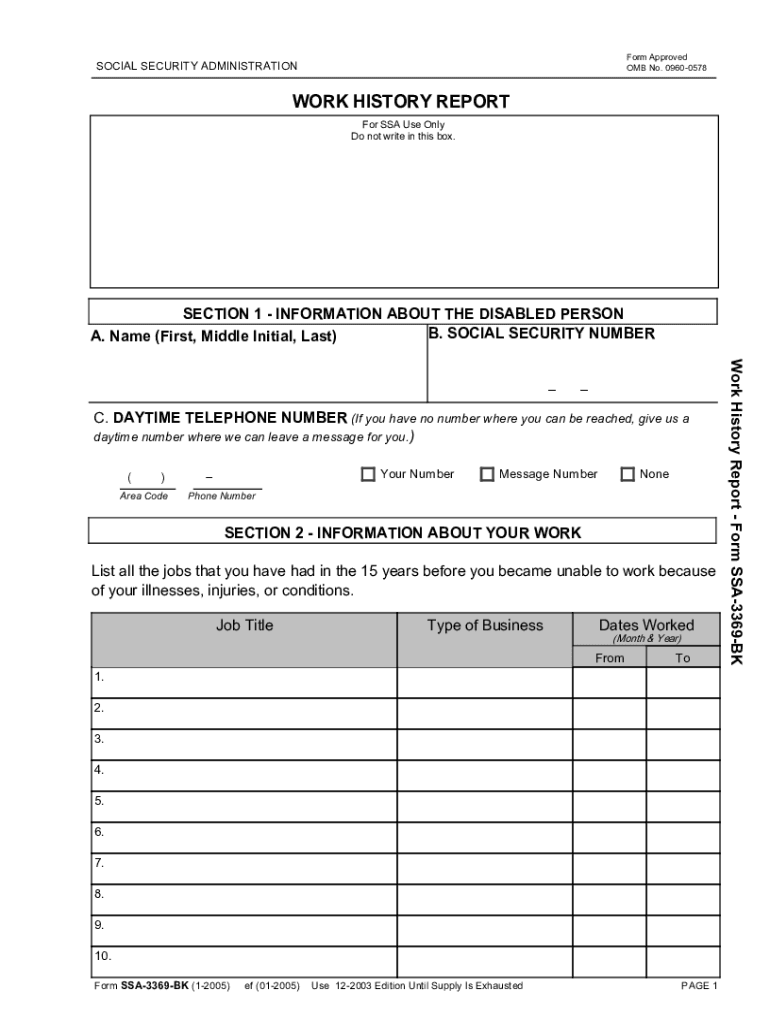
The Social Security Administration doesn't actually call it a "work history report" officially. It's called a Social Security Statement, but everyone in the disability field and most claimants refer to it by that nickname. You can get it free at ssa.gov/myaccount. The whole process takes about three minutes if your login credentials are current. It's a document showing every job where you paid Social Security taxes, with your annual earnings for each year going back to 1978. The SSA calculates your Average Indexed Monthly Earnings from this data, which determines both your retirement benefit and whether you qualify for disability. One claimant I worked with had her benefits cut by $200 a month because the SSA had two different earnings entries for the same year from 1994. She spent six months and three phone calls getting it corrected. The statement also shows your estimated retirement benefit at full retirement age and at age 62, plus your disability insurance amount. None of these numbers are guarantees. They're projections based on current law and your past earnings pattern. If you change jobs frequently, switch between W-2 and 1099 work, or have gaps where you didn't file taxes, those projections become less reliable.
How to Access It Without the Normal Hassle
Create a my SSA account at ssa.gov. You need to verify your identity with a few pieces of information plus a mobile phone or landline they can call to confirm. The verification step trips up a lot of people. The system asks for your driver's license number, full address history for the past few years, and sometimes your mother's maiden name. If you've moved recently or changed your name due to marriage, make sure the address history matches what SSA has on file. One common mistake is listing your current address instead of your address at the time of previous claims. SSA's system cross-references this data, and mismatches trigger manual review that adds 2-3 weeks. Once verified, download the PDF version of your statement. The online view shows the same data but printing it gives you a permanent record. Keep it somewhere safe. You'll need to reference specific years and earnings amounts when filing for disability or appealing a benefit determination. Having the exact figures prevents disputes about whether your earnings were properly indexed.
Indexing and Earnings Credits Explained
Your past earnings get adjusted for inflation using a specific formula the SSA updates each year. This is called indexing, and it's why a dollar earned in 1978 counts differently than a dollar earned in 2023. The indexing preserves the purchasing power of your earnings when calculating your benefit. Without it, older workers would be penalized simply for working decades ago. For disability claims, you need enough work credits. Generally, you need 40 credits, 20 of which were earned in the last 10 years ending when your disability began. Credits are based on your annual earnings. In 2024, you earn one credit for each $1,730 in covered earnings, up to four credits per year. The threshold adjusts annually with wage growth. If you worked part-time or had irregular income, you might not reach four credits in a given year. That doesn't disqualify you immediately, but it affects your eligibility calculation.
Get the Full Details
Common Problems and How I Fix Them
Mismatched earnings is the biggest issue. Employers sometimes report wages to SSA under the wrong Social Security number, or they misclassify independent contractor payments. When I encounter this, I pull theearnings record from my SSA statement, note the specific years with discrepancies, and file Form SSA-1311 for correction. The process takes 60-90 days typically. Having documentation like W-2s, 1099s, or pay stubs speeds things up considerably. Another frequent problem is missing years. Self-employed individuals sometimes forget to report income to SSA if they didn't pay estimated taxes. Without reported earnings, those years don't count toward your work history. I've seen cases where people had gaps spanning 5-7 years that eliminated potential credits. The fix is to file amended tax returns if you're within the statute of limitations, or provide alternative documentation like bank records showing income deposits. Indexed versus non-indexed earnings confusion causes disputes during appeals. The SSA uses indexed earnings for benefit calculations but reports both indexed and non-indexed amounts on your statement. When someone questions why their benefit seems lower than expected based on their nominal earnings, showing the difference between the two columns usually resolves the misunderstanding. Print both the online view and the PDF, and highlight the indexed earnings column.
When the Statement Doesn't Help
The Social Security Statement is useful but limited. It only shows covered earnings, meaning income from jobs where Social Security taxes were withheld. Tips, cash payments, and some foreign earnings might not appear. If you worked for a foreign government or an international organization, your earnings might be excluded entirely. The SSA can't correct what it never received, so having your own records is essential. Projections on the statement assume you continue earning at your current pattern. If you're self-employed with variable income, or if you plan to work fewer hours before retirement, those estimates become irrelevant. Some people rely too heavily on the projected benefit amount and make financial decisions based on numbers that never materialize. Treat the projections as rough guides, not commitments. The statement doesn't show your detailed work chart, which lists your quarterly earnings breakdown. Disability examiners sometimes request the work chart specifically to verify your recent activity. You can request it by calling SSA or submitting Form SSA-8115. Processing takes 2-4 weeks. If you're awaiting a disability hearing, request it early enough to include it in your file.
Practical Tips from Years of Dealing With This
Download your statement every year. Earnings get added gradually throughout the year, and late submissions from employers can appear months after the fact. Annual checks catch errors before they compound. I recommend bookmarking the my SSA page and setting a calendar reminder for January each year. Keep personal tax records for at least six years after filing. SSA can revise earnings records up to three years after the return was filed, plus additional time if there's an error. Having your original documents prevents situations where you can't prove income for a specific year. Digital copies stored in cloud backup work fine, but keep the originals somewhere accessible. If you're appealing a denial or facing a benefit reduction, request a copy of your entire file from SSA. The statement alone doesn't include internal notes, examiner recommendations, or medical evidence considerations. The full record shows exactly what decisions were based on and where gaps might exist. Submit a Freedom of Information Act request if SSA won't provide it voluntarily. Processing takes 10-20 business days.

Don't assume the statement is accurate just because it exists. People get complacent seeing their earnings listed and stop verifying them against their own records. I've reviewed cases where workers had incorrect years listed, duplicate entries, or missing quarters that affected their credit calculations. A five-minute check against your tax returns prevents headaches later. Cross-reference each year's earnings with your W-2 or 1099 totals, and note any discrepancies immediately.