How I Learned to Stop Worrying and Love Credit Repair
The first time I tried disputing a tradeline for a client, I sent the letter to the wrong bureau. Not close. Wrong one. The consumer had a Collection 1 sitting on TransUnion while I mailed my request to Equifax like a complete amateur. That cost me three weeks and an irate phone call. You'll make smaller mistakes later. The good news is none of them are fatal. Starting from home isn't some viral dream. It's mostly filling out CTEC requests, waiting fourteen days, and arguing with automated portals that pretend to read attachments. Here's what it actually looks like on a Tuesday morning. I use Credit Buro Pro for dispute generation. It's $49 a month. The free tier lets you run one client before asking for a credit card. The software prints disputes that are within the letter of the law, which matters more than most people realize. A poorly worded dispute gives the bureau a perfect excuse to deny everything. Good wording forces them to actually investigate.
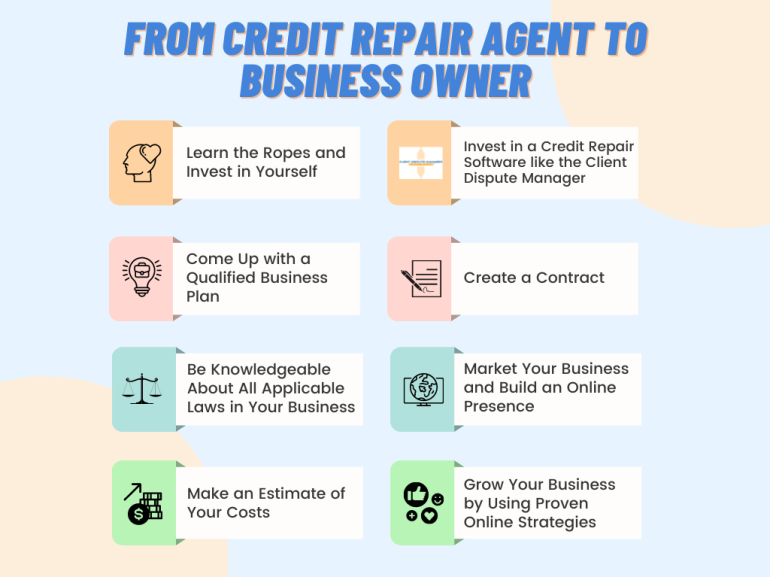
Here's the part nobody tells you: most credit repair failures aren't about the disputes. They're about client documentation. You need proof of identity, proof of address, and a signed agreement before you touch a single trade line. I learned this the hard way when a client disappeared mid-process and I had no written authorization to continue. The FTC requires that contract. State laws vary. California requires a three-day right of cancellation at minimum. Texas has no such requirement. Florida sits somewhere in between. Don't guess about this.
The Actual Workflow
Step one is pulling the client's credit reports from all three bureaus. AnnualCreditReport.com is free. It gives you the full report, not the score-only preview they sell to beginners. Print or save them as PDFs. Don't scan paper copies. Scans introduce noise that delays automated processing. Step two is going through each report and flagging items that look questionable. I look for:
Get the Full Details
- Accounts reported by collections agencies that don't match any original creditor on file
- Payment histories showing late payments when the client has bank records proving timely payment
- Addresses attached to accounts that the client never lived at
- Duplicate accounts showing up under slightly different naming conventions
Some of these are real errors. Some are just confusing. Your job is to separate them and dispute the ones that have a reasonable chance of moving. The rest get flagged for the client to deal with directly. Disputes take 30 days by law. Most resolve in 14 to 21. You'll get a response letter from the bureau saying they verified or deleted the item. Sometimes they say they investigated and found nothing. That's not the end. You can resend with additional documentation or escalate to a secondary dispute if the initial one fails. Here's where people get stuck: they think one dispute per item is enough. It's not. Bureaus often approve the first checkmark without really investigating. Second-round disputes with fresh evidence actually move things. I send round two disputes about 40 percent of the time. They succeed roughly 60 percent of that second batch. That math alone changes the whole business.
What Actually Works (And What Doesn't)
Good faith letters work. Templates that ask the bureau to "verify this debt" work. Letters that threaten legal action without basis don't. The FDCPA gives you leverage, but using it incorrectly opens you to countersuits. I've seen a firm get hit with a $15,000 claim because a dispute letter contained language that could be read as intimidation rather than inquiry. Don't do that. Mail matters more than email. Bureaus treat emailed disputes differently than postal ones. Certified mail with return receipt gives you proof of delivery. If the bureau claims they never received your dispute, that receipt is your only shield. I mail every dispute via USPS certified mail and track the delivery myself. Takes 4 minutes and saves you from a hundred headaches. Here's a counter-intuitive thing: sometimes deleting a positive account helps. I know that sounds wrong. But if a client has a collection account dragging them down and a perfectly healthy tradeline from five years ago, removing the positive item can actually improve their score by cleaning up the "age of accounts" calculation. The score dip is temporary. Most clients see recovery within 60 days. Not every client needs every account preserved.
Pricing and Getting Clients
The industry standard is $80 to $150 per disputed item per month, or a flat fee of $300 to $500 per month for unlimited disputes on active accounts. I charge $120 per item, billed monthly for up to 90 days. If we're still working at day 91, the price goes up 20 percent. Most clients finish in 60 to 75 days. The penalty clause keeps them from signing up with ten items and disappearing. Getting clients is the hard part. Facebook groups work better than you'd think. Post helpful threads about credit score fixes without selling anything. People will DM you. Convert them to a consultation call. The call should be 15 minutes maximum. Longer calls signal desperation. Short calls signal competence. Your website needs to be simple. Services, pricing, FAQ, contact form. Nothing else. Blog posts about credit topics help with SEO but they take six months to show results. Don't build a content strategy as your primary acquisition channel. That's a trap.
Legal Requirements You Can't Skip
You need a written client agreement signed before providing any service. This isn't optional. The Credit Repair Organizations Act (CROA) requires it. The agreement must include: Form your LLC. Get an EIN. Open a business bank account. Keep personal and business finances separate from day one. Commingling accounts is how people lose protection from the liability shield they spent money creating. It happens more often than you'd expect. Do not promise specific score improvements. The FTC cracked down on this hard. "We guarantee a 100 point increase" gets you sued. "We dispute inaccurate items to the best of our ability" is truthful and legal. The difference matters in court.
Tools I Actually Use
Beyond Credit Buro Pro, I use: LexisNexis SoftID for identity verification. Costs about $2 per check. Worth every penny. Fake IDs and stolen identities show up at a rate of roughly 1 in 50 applicants. Skipping verification costs you more in chargebacks than the tool costs monthly. QuickBooks Self-Employed for bookkeeping. Tracks mileage automatically. Mileage is deductible. Most credit repair owners don't claim it because they forget. Track every drive to the post office.
Docusign for client signatures. Paper signatures work too, but scanning and storing PDFs gets messy fast. Docusign keeps everything organized and provides an audit trail.

When This Business Won't Work For You
If you hate reading, skip this. Credit repair is 90 percent document review. You'll be looking at payment histories, account statements, and correspondence between creditors and consumers. If that sounds fun, you're in the wrong line of work. If you can't handle rejection, don't start. Your disputes will fail. Some clients will churn. The bureaus will deny legitimate claims. The system is designed to resist change. You're fighting institutional inertia, not a simple error. Revenue is back-loaded. Most new firms see their first meaningful month of income at month four or five. Before that, you're spending time on setup, learning the software, and building a pipeline. If you need money next month, this isn't the path.
The Bottom Line
Credit repair is a service business with low overhead and high margins once you figure out the workflow. The first year is about learning. The second year is about scaling. The mistake most people make is treating it like a get-rich-quick scheme instead of a skills business. It's not either. It's neither. Just a regular business that happens to deal with other people's financial problems. I've been doing this for seven years. My busiest month ever was 47 active clients and 312 individual disputes. My slowest was 8 clients and 12 disputes. Both were profitable. The variability is normal. Plan for it. If you want to start, pick a niche. Medical debt disputes. Student loan rehabilitation. Mortgage rewrites. General credit repair works, but specialization lets you charge more and builds referral networks faster. I started general. I niche down to medical debt and collections five years ago. Revenue doubled without working harder.