Setting Up an Accounting Worksheet That Actually Works
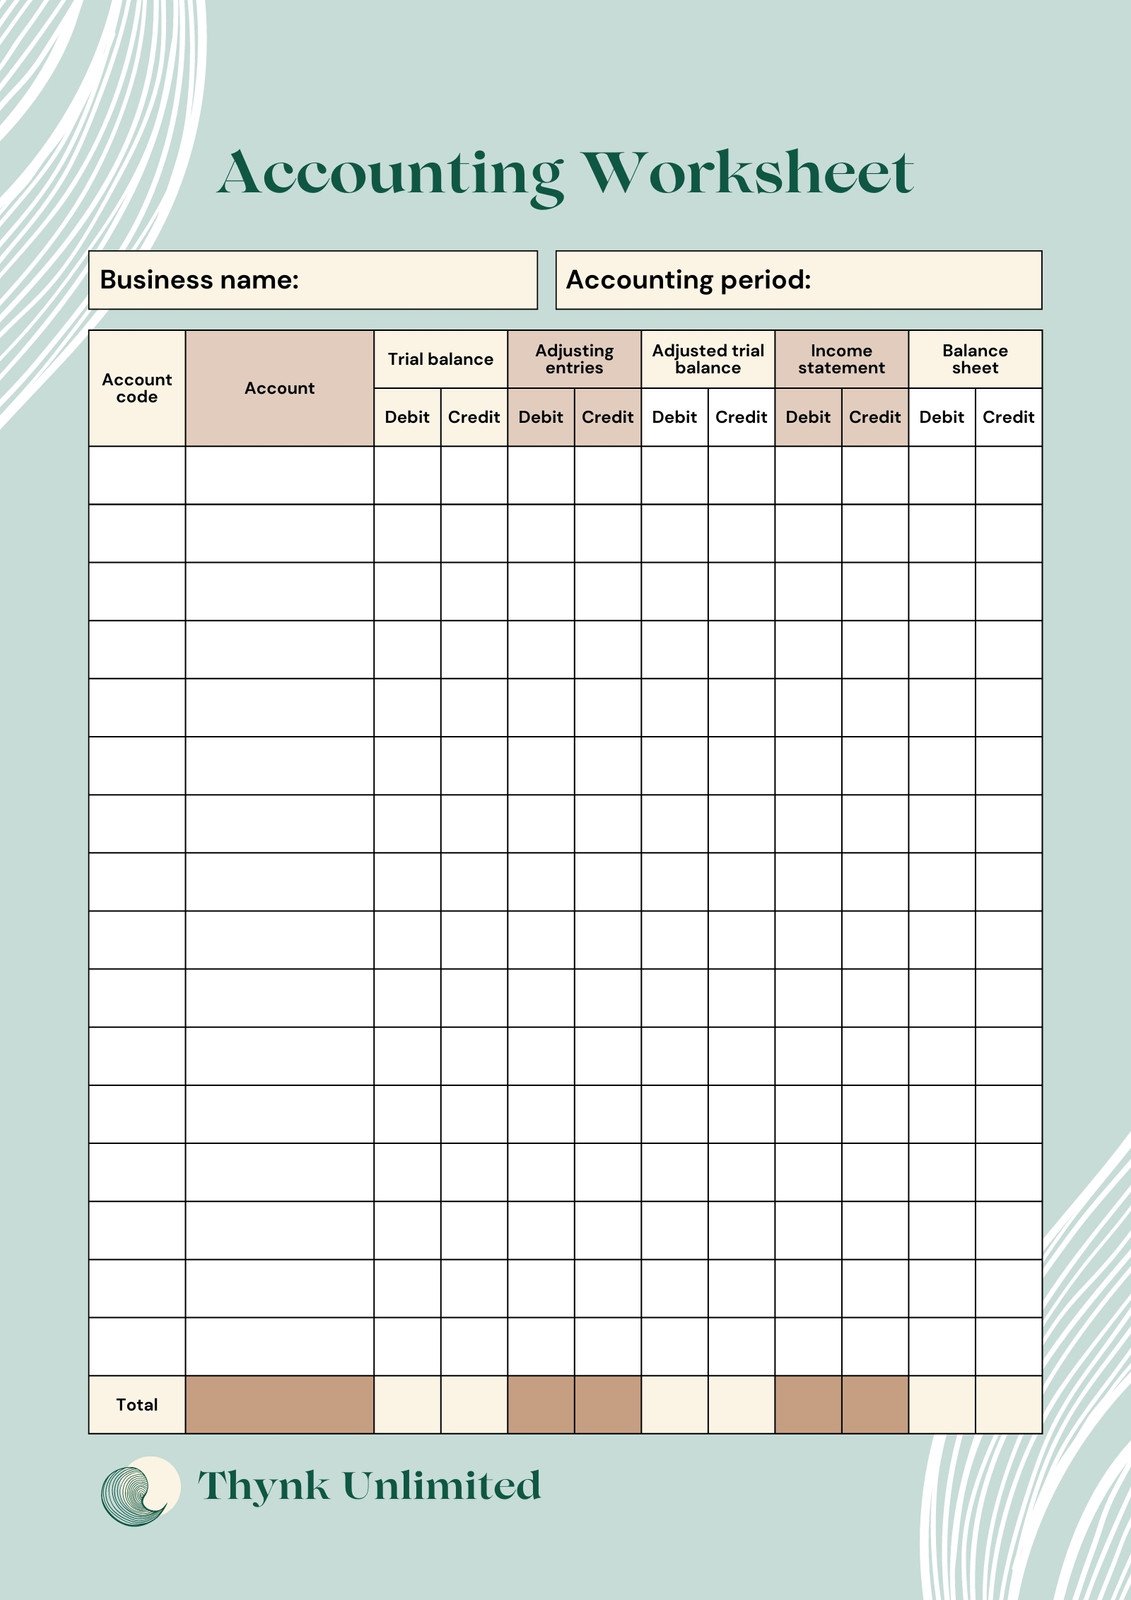
The basic spreadsheet accounting worksheet is just a grid with columns for unadjusted trial balance, adjustments, adjusted trial balance, income statement, and balance sheet. I know that sounds like a textbook definition, but most people I talk to who use these have no idea what goes in the bottom two columns or why they exist at all. It's not magic, it's just organized chaos on paper, and I've seen enough botched ones to know where people trip up. I usually start with a simple 12-column layout. Debits on the left, credits on the right, split across five major sections. The first section pulls from your general ledger before any adjusting entries. The adjustment column is where things get messy. That's where people make mistakes, and I learned that the hard way when I was dealing with a client who had prepayments scattered across three different revenue accounts with no real tracking system in place. The problem hit me when the adjusted trial balance didn't match the financial statements. Turns out, one of their deferred revenue adjustments was entered as a debit to revenue instead of a credit, and because the worksheet wasn't set up to flag debits against credits in the same account, it went completely unnoticed through the first review. The workaround was simple: add a column that shows the net change per account after adjustments. Now any account that shifts in the wrong direction from its normal balance shows up immediately in red. Takes maybe five extra minutes to set up but saves hours of debugging later.
Here's the structure I recommend, and this has been my standard for about a decade now: Columns 1-2: Account names with debit and credit balances from the unadjusted trial balance. This is just a snapshot of your ledger before any month-end or year-end adjustments. It should match your GL exactly at this point, and if it doesn't, stop right there and figure out why before moving forward. Columns 3-4: Adjusting entries. This is where accruals, deferrals, depreciation, and reclassifications live. Each entry needs to balance across columns 3 and 4 before you move to the next section. If they don't balance, nothing below this point will be correct, no matter how careful you are in the other columns.
Columns 5-6: Adjusted trial balance. These columns are calculated by combining the first four. For each account, you add or subtract depending on whether the adjustment is in the same direction as the original balance. A debit balance account with a debit adjustment becomes a larger debit. A credit balance account with a debit adjustment becomes smaller. This arithmetic is straightforward, but people rush it and make sign errors that cascade through everything below. Columns 7-8: Income statement column. Revenue and expense accounts drop here. Simple enough, but watch out for accounts that sit in a gray area, like gains and losses on asset sales, or interest income that might be classified differently depending on your company structure. Don't let miscategorized accounts wander into the wrong section. Columns 9-10: Balance sheet column. Assets, liabilities, and equity accounts land here. Net income or loss from the income statement columns gets posted here as retained earnings or current period earnings. The two columns must balance at the end, or you've made a mistake somewhere above.
Get the Full Details

The whole process, once you're comfortable with it, takes roughly 30 to 45 minutes for a small business with under 50 accounts. If you're doing it for the first time, plan on two hours. That's not slow, that's just reality. One thing people miss is that this worksheet format works best when you build it in a tool that can do basic validation without you writing custom scripts. Excel does it fine, but Google Sheets has some advantages if you're collaborating, since multiple people can spot errors simultaneously. I switched my team to Sheets partly for that reason, and partly because the version history caught an error once where someone had deleted an entire row of depreciation entries without telling anyone. Saved me a full audit headache. Now, is this approach perfect? No. Here's where it breaks down: if you're working with 200 or more accounts, the manual spreadsheet approach starts to feel like pushing boulders uphill. The risk of human error increases exponentially because every adjustment has to be traced across multiple columns by hand. At that scale, dedicated accounting software with built-in trial balance and adjustment workflows makes more sense, even though it costs money. A worksheet spreadsheet is fine for small operations, sole proprietors, or anyone whose chart of accounts fits comfortably on one screen without scrolling.
Another edge case is multi-entity work. If you have more than one business unit or subsidiary, combining everything onto a single worksheet creates a mess very quickly. I've seen people try to manage three entities on one sheet and end up with column widths that make the whole thing unreadable. Better to keep each entity on its own tab or separate file and consolidate only at the adjusted trial balance stage. If you want to download a starter template, there are plenty of free ones online, but most of them are overcomplicated or missing the validation columns I mentioned earlier. The one I use has a clean 12-column layout with conditional formatting that highlights any account where the adjusted balance flips sign compared to the unadjusted version. It's not fancy, but it catches the kind of error that would otherwise hide until you were trying to reconcile the bank statement three weeks later. The biggest tip I can give is this: test your worksheet before you consider it done. Run the numbers both ways. Start from the adjusted trial balance and work backward through the adjustments, or start from the income statement and balance sheet columns and verify they tie out to the adjusted trial balance. If both paths land on the same numbers, you're probably in good shape. If they don't, you've got work to do, and it's infinitely easier to find the error now than after you've finalized the financial statements.
I've also learned that keeping a separate schedule for each adjustment type helps. Deferred revenue, prepaid expenses, accrued liabilities, depreciation, reclassifications, bad debt reserve changes. When each adjustment type has its own supporting schedule, it's much easier to explain to an auditor why a number moved. A bare worksheet with no documentation underneath is a liability in itself, especially if anything ever gets reviewed. This is just the straightforward version. For more complex situations involving intercompany transactions, foreign currency translation, or lease accounting under newer standards, the worksheet needs significant expansion and often benefits from being built in a proper ERP system rather than a spreadsheet. But for most small to medium businesses preparing monthly or annual financials, this setup covers the core requirements without unnecessary complexity.
When to Move Beyond the Spreadsheet
The worksheet is a tool, not a strategy. It gives you visibility into your numbers and a structured way to document adjustments, but it doesn't replace having good underlying processes. If your general ledger entries are sloppy or your chart of accounts is disorganized, a worksheet won't fix that. It'll just make the sloppiness more visible. I've walked into offices where the owner was proud of their elaborate spreadsheet setup, only to find the source data was unreliable because nobody had a consistent process for recording transactions throughout the month. The worksheet was beautiful, precise, and completely wrong. Garbage in, garbage out, regardless of how well-designed the output format is. For teams that are growing past the spreadsheet stage, look into lightweight accounting platforms like QuickBooks Online or Xero. They handle the trial balance and adjustment workflows automatically and generate financial statements with one click. The tradeoff is less flexibility and a monthly subscription cost, but for a business with meaningful transaction volume, that tradeoff usually pays for itself within the first month of reduced manual effort.
There's also a middle ground. Some smaller firms use a combination approach, maintaining a master spreadsheet for adjustments and analysis while running their transactional data through a basic accounting system. The spreadsheet becomes the analytical layer on top of clean source data, which is exactly how it's supposed to work. The bottom line is that a well-constructed accounting worksheet is a practical, low-cost solution that works well for simple operations. It teaches you how your numbers connect, gives you a permanent record of every adjustment, and produces financial statements without expensive software. Just don't let it become a crutch that hides deeper problems in your accounting process. If you find yourself spending more time fixing the worksheet than learning from it, that's usually a sign the real issue is upstream, not in the format you're using to present the data. Build it clean, test it thoroughly, document your adjustments, and know when it's time to move to something more robust. That's basically the whole thing.


