What Actually Goes Into a Weekly Accounting Worksheet
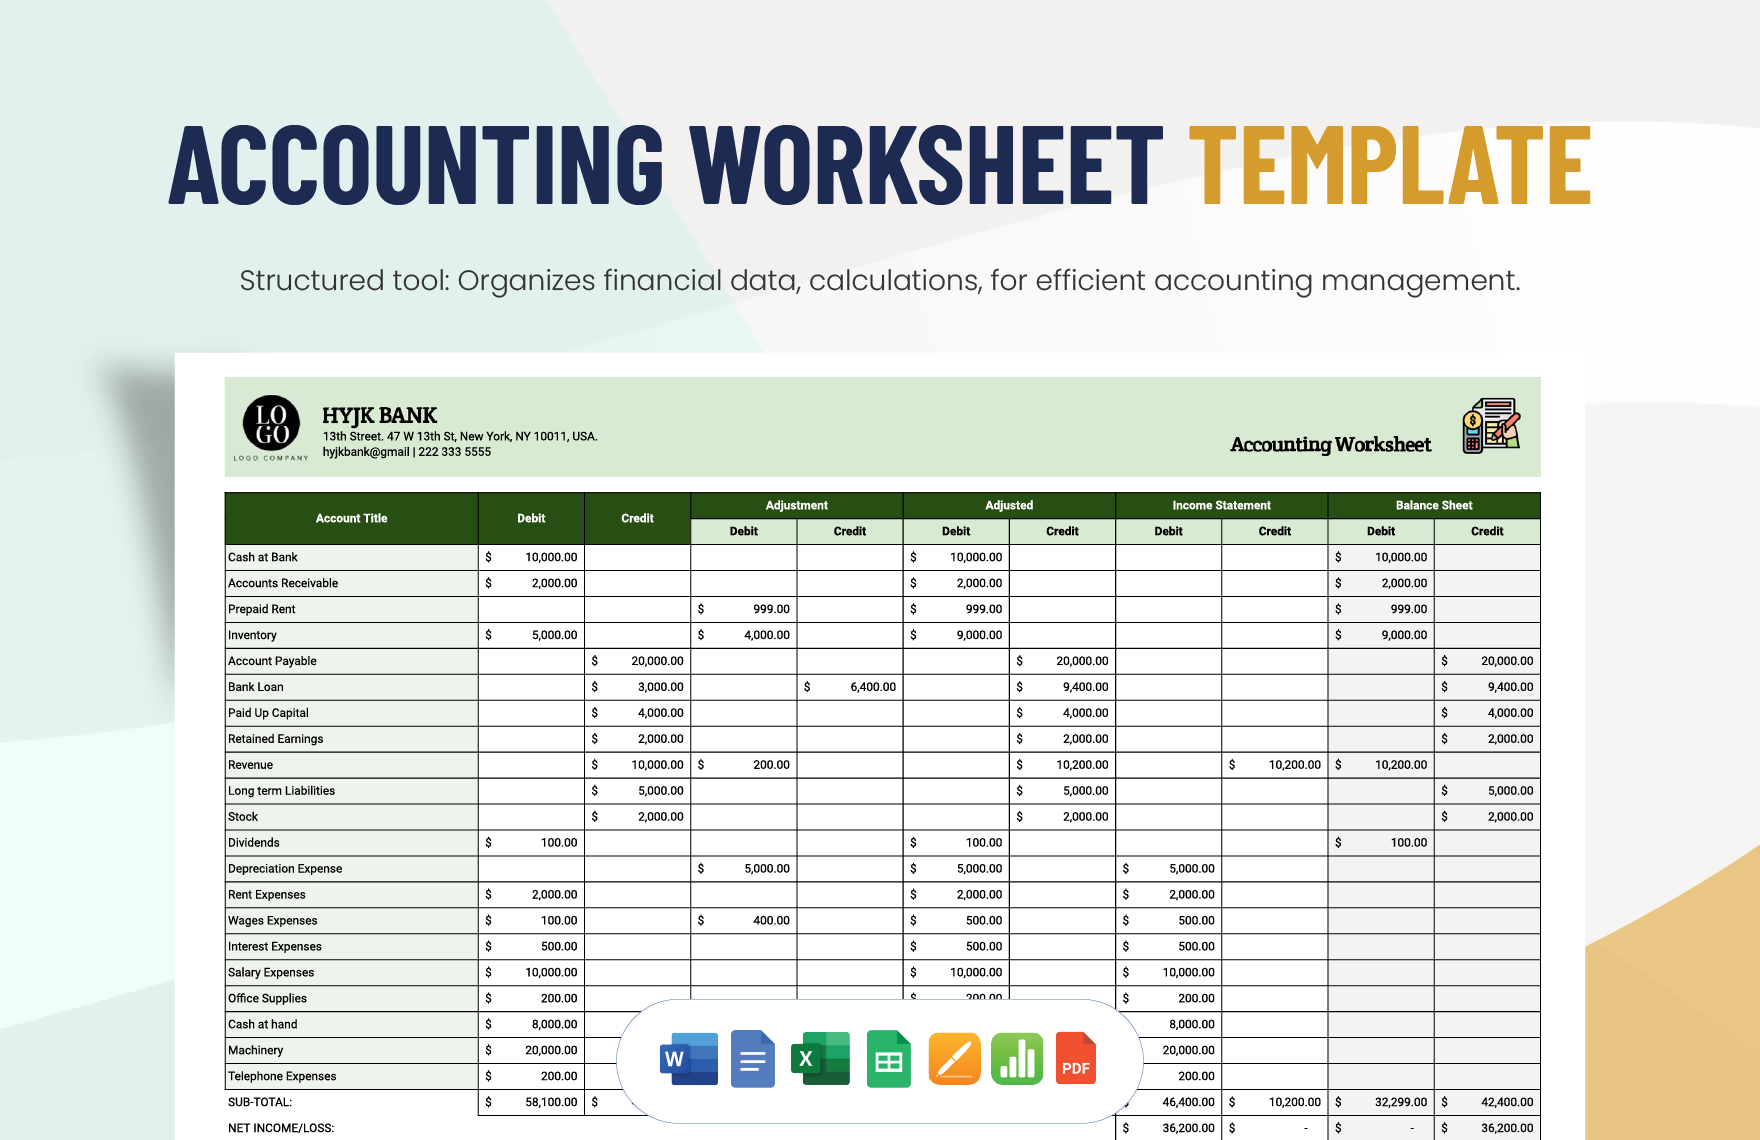
A Worksheet For Accounting Weekly is a living document that sits between your raw transaction data and your formal financial statements. It is not a report you hand to anyone. It is a working sheet you build, adjust, and sometimes tear apart when something does not balance. Most small businesses try to skip it because it looks like extra work. What they end up doing is manually fixing entries in the ledger after the fact, which takes longer and introduces errors that are harder to catch. The worksheet exists so you can see the adjustments before they become permanent. Here is how it typically works. You pull your trial balance at the end of the week. You list each account on the left. You place four columns to the right: unadjusted trial balance, adjustments, adjusted trial balance, income statement, and balance sheet. Then you go line by line, matching deposits against invoices, reconciling accounts receivable aging, and noting any prepaid expenses or accrued liabilities that need to be recognized for the period.
Building Your Worksheet For Accounting Weekly
Start by exporting your general ledger for the current week. Do not rely on whatever the bank statement shows because banks do not capture everything, especially accruals. If you are using QuickBooks, Xero, or FreshBooks, export the transaction detail for each account you maintain. Open that export in a spreadsheet program and create a master list with columns for date, reference number, description, debit, and credit. Next, build your account list. This should match the chart of accounts in your software, but I usually add a column called "class" or "department" if you track things that way. Keep it simple in the beginning. Revenue, cost of goods sold, operating expenses, accounts receivable, accounts payable, credit card liabilities, loans, equity, cash, and fixed assets cover about 90 percent of what most small firms actually deal with each week. Once you have the account list, fill in the unadjusted trial balance. This is just a sum of each account for the week so far. Do not worry if it looks wrong compared to what your software shows. That is the point. The worksheet is where you find the differences and fix them.
The adjustment phase is where most people make mistakes. The adjustments you will encounter every single week are fairly standard. Accrued wages if anyone worked hours that were not yet entered. Accrued revenue for work done but not yet invoiced. Prepaid expenses that need to be amortized across the period. Depreciation on fixed assets. Bad debt reserves if you write off receivables. Inventory adjustments if you track stock. Sales tax accruals if you collect and remit on a weekly cycle. Each of these needs its own line item with a clear description and a date stamp so you can trace it later. One thing beginners consistently get wrong is the direction of the adjustment. When you accrue an expense, you debit the expense account and credit the liability. When you defer revenue, you debit the revenue account and credit deferred revenue. When you record depreciation, you debit depreciation expense and credit accumulated depreciation. These entries feel backward because they are counter-intuitive to how cash actually moves, but the worksheet makes it visible before the journal entry gets posted.
Get the Full Details
A Problem I Ran Into With a Weekly Worksheet
Early on I had a client who used a payment processor that held funds for a rolling 48-hour settlement window. Their Stripe account showed transactions on the day the customer paid, but the cash did not actually land in the bank until the next business day. This created a persistent mismatch every Monday morning when the prior Friday and Saturday sales would appear in the bank feed but not yet in the processor's settlement report. I solved this by adding a "processor holding" clearing account to the worksheet. At the end of each week, I pulled the processor's reconciliation report and compared it to the bank deposit. The difference went into that clearing account as an adjustment line. The next Monday, when the funds hit the bank, I reversed the adjusting entry and the accounts auto-aligned. It sounds like extra work, but it saved about 20 minutes per week that was previously spent chasing down phantom missing deposits. Without that clearing account, the variance would show up as an unexplained fluctuation in cash, which looked like a theft issue to anyone reviewing the numbers without context.
What Happens After the Adjustments
Once every line is adjusted, you move the totals across into the adjusted trial balance. Then you split those numbers into the income statement columns and the balance sheet columns. Revenue and expense accounts go to the income statement. Assets, liabilities, and equity go to the balance sheet. The two sides should each balance independently. If they do not, you have an error in the adjustments, not a real accounting problem. Go back and check your debits and credits one more time. This step is also where you catch timing issues. If your accounts receivable balance grew by $15,000 this week but your revenue only grew by $8,000, you are collecting slower than you are billing. That does not show up in the worksheet alone, but once the numbers are laid out side by side, the discrepancy becomes obvious and you can investigate whether it is a collection problem, a billing error, or something else entirely.
Using a Template and Making It Sustainable
There is no reason to rebuild this from scratch every week. Create a template once with your chart of accounts locked in the first column, then duplicate it each Monday. Protect the structure columns so you do not accidentally delete formulas. Leave the transaction entry columns open. If you use Google Sheets or Excel, set up data validation dropdowns for the account names so you are not typing them out manually each time. That alone cuts the setup time from about 45 minutes to roughly 10 minutes for a typical small business. If you are doing this for a single business, one spreadsheet is enough. If you are managing multiple clients, I recommend a master workbook with one tab per client and a summary tab that pulls the key figures from each. This keeps your weekly review from turning into a filing exercise. You should be able to open the file and see everything that needs attention in under five minutes.
Where This Method Breaks Down
A manual Worksheet For Accounting Weekly is fine for businesses with fewer than about 200 transactions per week. Beyond that, the time investment grows disproportionately and the risk of manual entry errors increases. If you are processing invoices through a system like Bill.com, paying employees through Gusto or ADP, and reconciling three or more bank accounts each week, the worksheet becomes a bottleneck rather than a control. In that case, you are better off relying on automated reconciliation tools and using the spreadsheet only as a diagnostic when the software flags something unusual. Another limitation is that a weekly worksheet does not replace monthly close procedures. It catches timing and classification issues early, but it does not validate intercompany eliminations, inventory sub-ledger totals, or tax provision calculations. Those still require a dedicated monthly close process. Think of the weekly worksheet as an early warning system, not a substitute for the actual close. Also, if your business operates across multiple currencies or has significant foreign exchange exposure, the worksheet adds a layer of complexity that most template-based approaches do not handle well. You would need a separate adjustment column for currency gains and losses, and the unadjusted trial balance would need to be converted at the correct spot rate for each transaction date. That pushes this method toward being more of a monthly exercise than a weekly one for those kinds of operations.
What to Download or Build
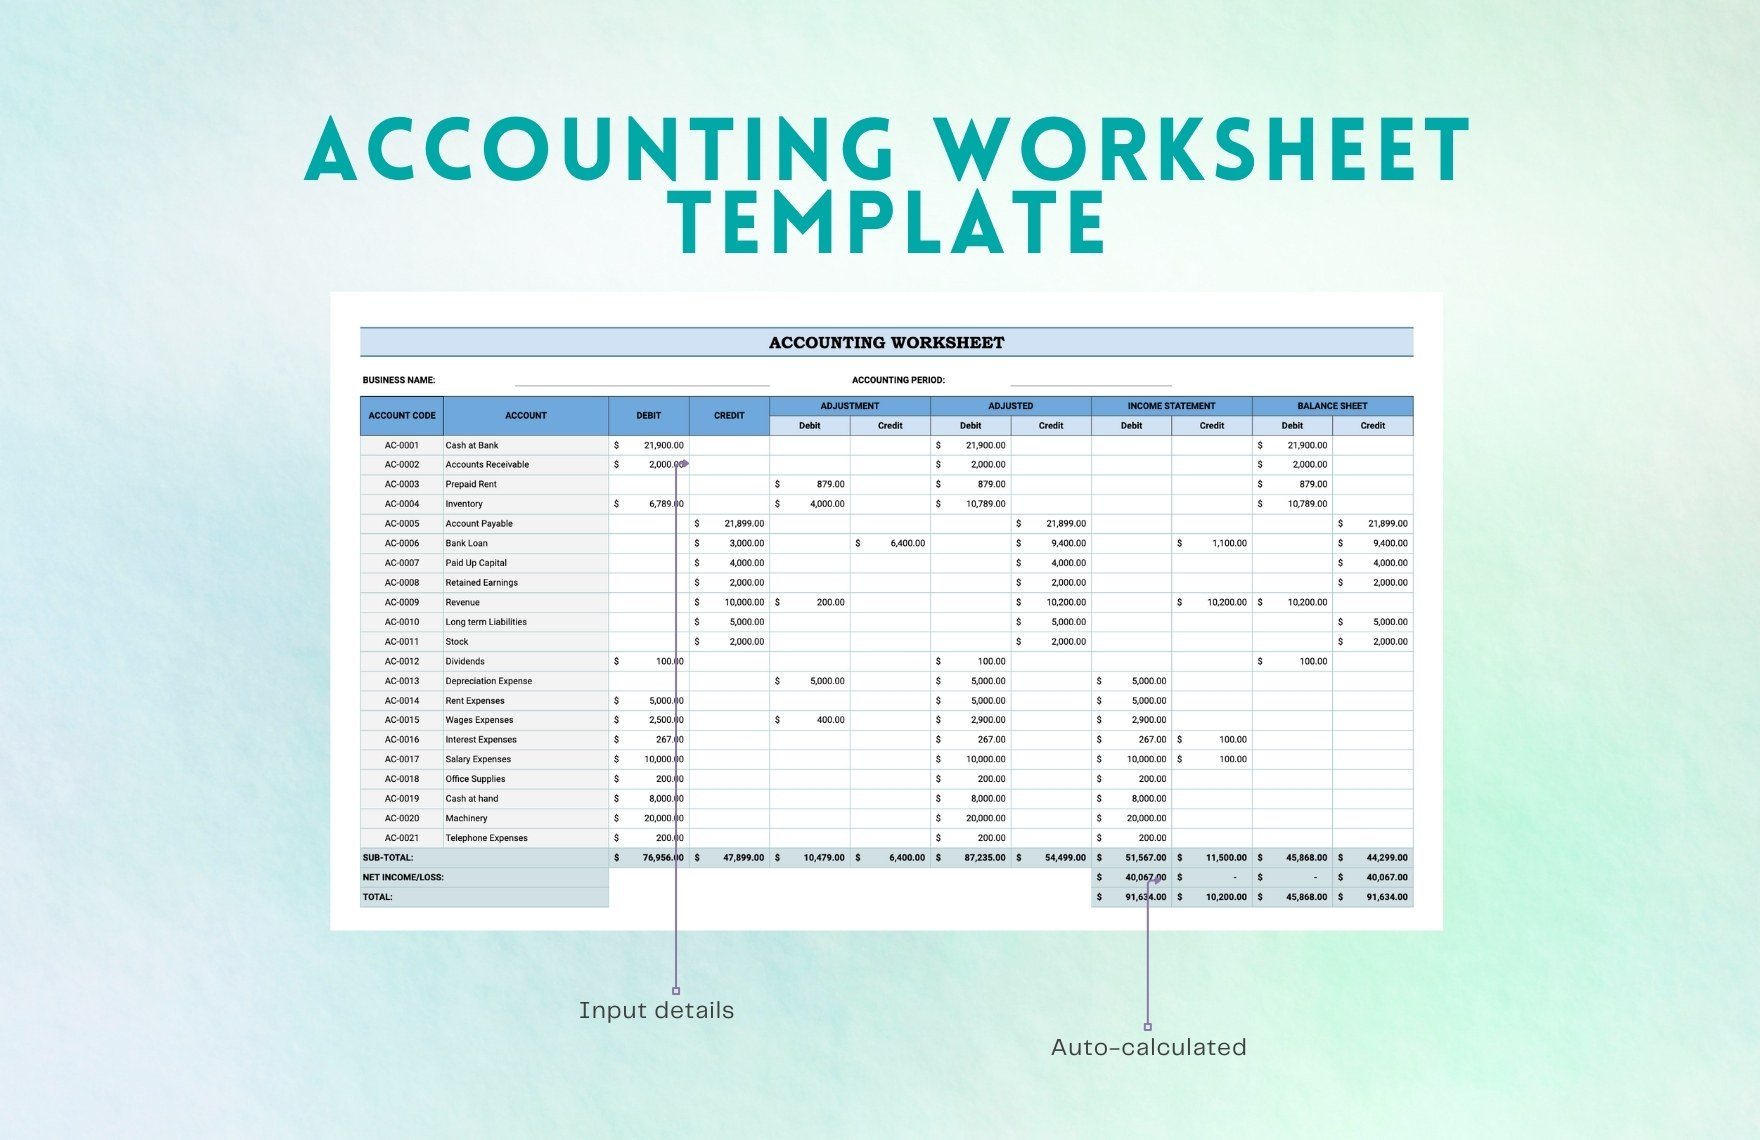
You can find basic accounting worksheet templates on Google Sheets and Excel template libraries, but most of them are designed for monthly or annual close cycles and include far more columns than you need for a weekly update. A simpler approach is to build your own from scratch using the structure I described: account name, unadjusted trial balance, adjustment description, adjustment debit, adjustment credit, adjusted trial balance, income statement debit, income statement credit, balance sheet debit, balance sheet credit. Ten columns total. That is enough for almost any small business to work through a full week in under 15 minutes once you are comfortable with the format. If you want a pre-built file to start with, look for a "trial balance worksheet" template and strip out the comparative columns and the balance sheet equation checks that are meant for annual reporting. Keep only the weekly columns. Add your own account list. That will give you a working document that matches how this process actually functions in practice rather than how it is described in textbooks.