Why Your Year-End Numbers Never Match Up Until You Standardize
I have spent twelve years reconciling accounts across three different subsidiaries, and the most common problem I see is not misunderstanding debits and credits. It is trying to force a yearly accounting worksheet to behave like a monthly one. They are fundamentally different animals.
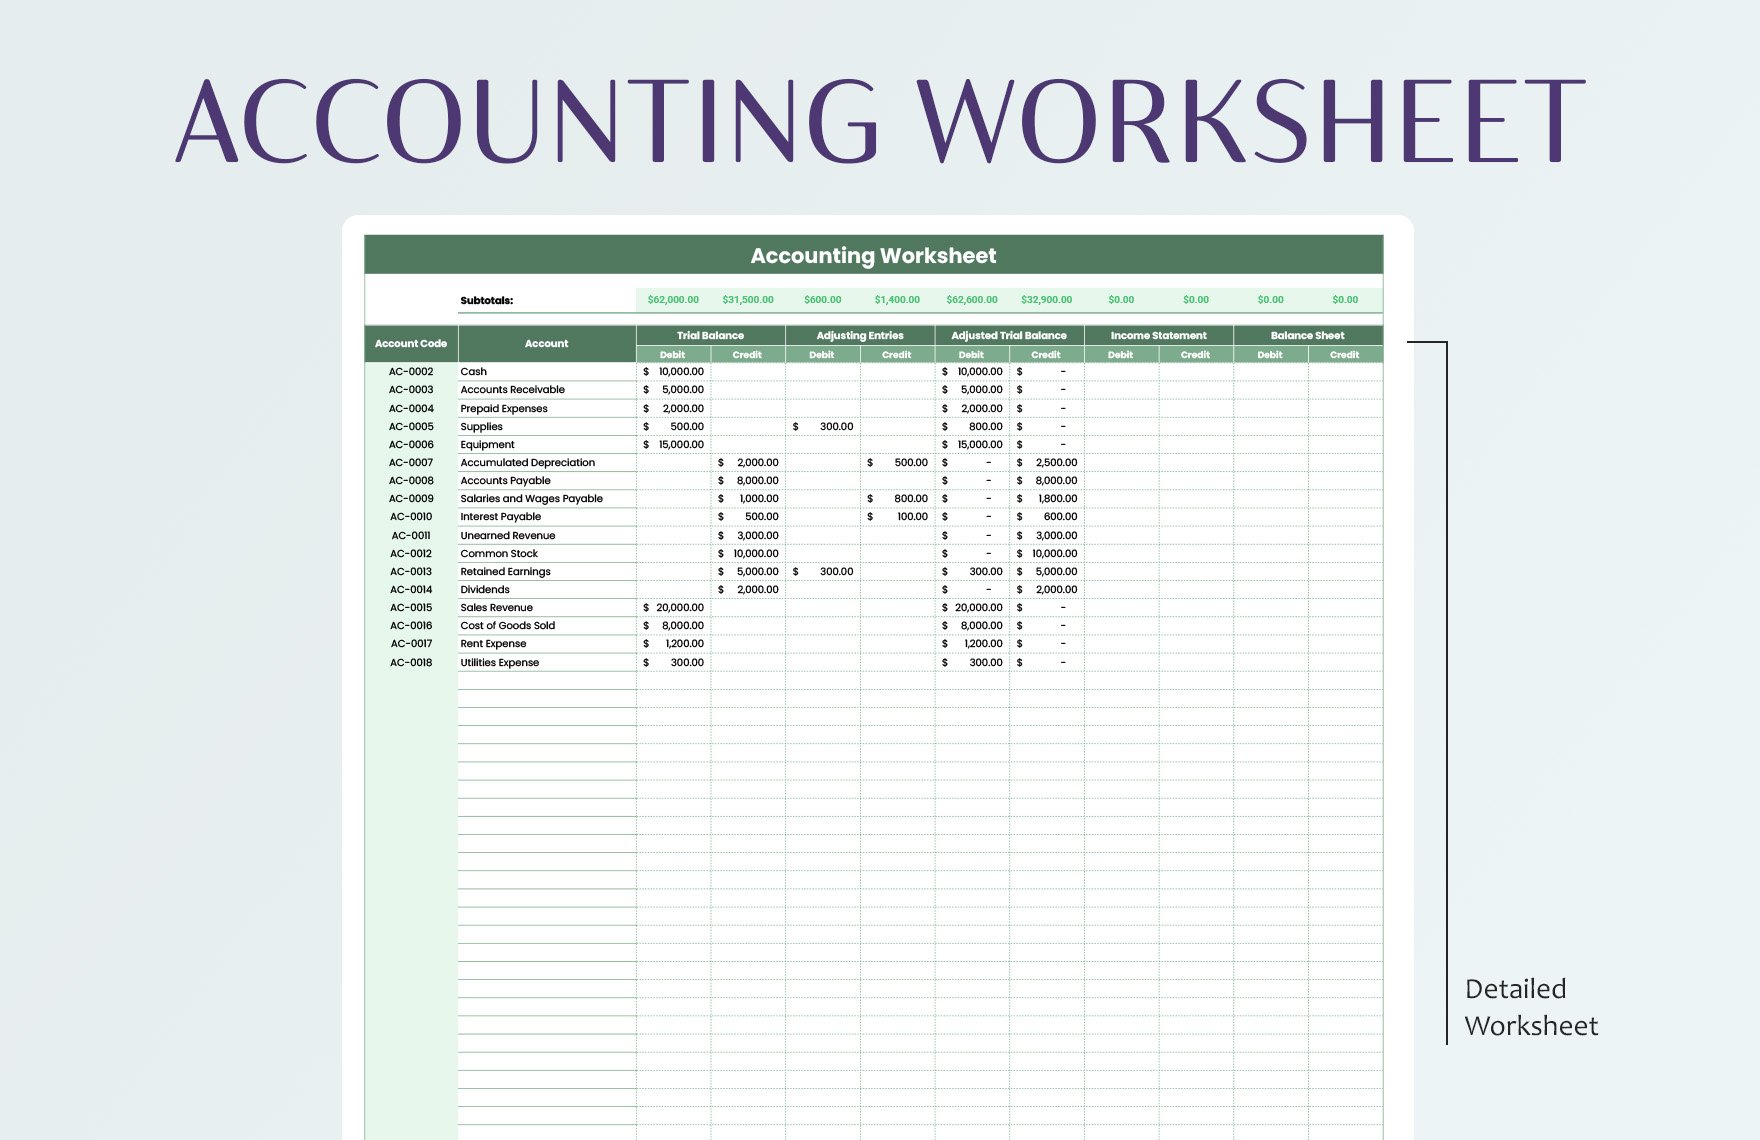
Worksheet For Accounting Yearly
A yearly accounting worksheet is essentially a structured spreadsheet that captures every adjustment, accrual, and reversal you need to make before your annual financial statements close. The format varies by industry, but the core structure is always the same: beginning balances, transactions during the period, adjusting entries, adjusted balances, and final financial statement columns.
The reason people struggle with it is that most templates online were designed for small businesses with simple operations. When you are dealing with intercompany eliminations, deferred tax calculations, or lease modifications under ASC 842, those free templates fall apart within minutes.
Here is what I learned after burning through three consultant engagements and two years of my own time trying to make a generic template work for a manufacturing company with inventory valuation issues.
The problem with pre-built templates
Most downloadable worksheets assume your chart of accounts is clean and you do not have material adjustments to make. In practice, year-end adjustments are where the real work lives. You are not just recording transactions. You are revisiting estimates, recalculating allowances, and reversing entries that were clearly wrong when you made them in March.
I once inherited a situation where the prior year's worksheet had a $47,000 accrual for warranty claims that was never reversed because nobody documented why it existed. The template column structure could not accommodate the fact that this was a two-period error, not a single-period adjustment. I had to build a completely separate schedule that tracked the original accrual, the actual claim experience, and the final catch-up adjustment. That took me six hours, and it would have been caught in five minutes if the base template had included a reversals column.
What actually works in practice
Start with the trial balance, not a blank template. Your worksheet should be built on top of the actual GL output with all accounts in their natural order. If your accounting software can export a detailed trial balance with sub-accounts and descriptions, use that. Do not manually type account numbers.
The structure I rely on has five distinct sections:
First section captures the unadjusted trial balance. This is your starting point and it should match exactly what the GL produces. Any difference here means your month-end closes were incomplete.
Second section lists every adjustment you need to make. This is where most people fail. They start with the final numbers and work backward. That approach creates errors because you lose sight of the original transaction. List each adjustment separately with the source document reference, the account affected, and whether it is an accrual, deferral, or reclassification.
Third section shows the adjusted trial balance. This is purely mathematical. If this column does not balance, something in your adjustment list is wrong. Double-entry means debits must equal credits, always. If they do not, trace back through your second section until you find the mismatch.
Fourth section maps to your financial statements. Income statement accounts go to the P&L column, balance sheet accounts go to the BS column. This mapping should be consistent year over year so you can compare changes without rebuilding the entire structure.
Fifth section is your working papers. This includes supporting schedules, senior review notes, and the final reconciliation to your audited numbers. Do not skip this. When an auditor asks where a $12,000 variance came from six months later, you need to point to a specific cell in this section, not a vague note in an email.
Common mistakes that cost you time
The biggest waste of time I see is using monthly worksheets for yearly closes. A monthly worksheet tracks running balances and current period activity. A yearly worksheet needs to show the full year impact of adjustments, especially those that span multiple periods. Depreciation changes, bad debt reserve adjustments, and inventory obsolescence all require multi-period visibility that a standard monthly template cannot provide.
Another mistake is not including the reversals column from day one. When you record an accrual in December, you expect it to reverse in January. But if you do not have a dedicated column tracking which adjustments reversed and which did not, you will end up with duplicate entries or missing items. I found this exact problem when our accrual schedule had twenty-three entries and only seven were properly reversed. The remaining sixteen sat in the GL for three years before someone noticed.
When to build versus buy
If your annual adjustments are fewer than ten and your chart of accounts does not change between years, a well-structured template might save you time. But if you have more than fifteen adjustments, multiple cost centers, or intercompany transactions, building a custom worksheet based on your actual data is faster than trying to fit your numbers into someone else's format.
The initial setup takes longer, maybe two to three hours, but once it is built, your yearly close drops from three days to six hours because you are not spending the first twelve hours troubleshooting why a template column is misaligned with your GL output.
Specific edge case that broke every template I tried
Last year we acquired a subsidiary mid-year and needed to consolidate their books into our yearly worksheet. The template assumed all entities had the same fiscal year end. This one had a different month-end, which meant their adjustment periods did not align with ours. The intercompany eliminations alone took eight hours because I had to create a separate mapping schedule that translated their December 31st balances into our November 30th reporting cycle. No standard template handled this. I ended up building a four-column layout that showed the subsidiary's raw GL, their adjusted trial balance, our consolidation adjustments, and the final eliminated balances. It took me a day to set up, but it has worked for three consecutive years since.
Practical recommendation
If you need to start somewhere, begin with your most recent trial balance and build the worksheet around it. Do not start with a blank template and try to force your data into it. The structure should serve your process, not the other way around. Include columns for source references, adjustment types, reversal status, and reviewer signatures. These small additions save hours when you are explaining variances to your controller or preparing for audit season.
The exact Worksheet For Accounting Yearly format you need depends on your complexity, but the principle remains the same: capture the journey from unadjusted to adjusted to reported, with enough detail that anyone reading it six months later can understand why each number exists.
Gallery Worksheet For Accounting Yearly
Accounting Ledger Template, Yearly Accounts and General Ledger Sheet, Money Tracker, Columnar ...
Accounting Worksheet Template Excel
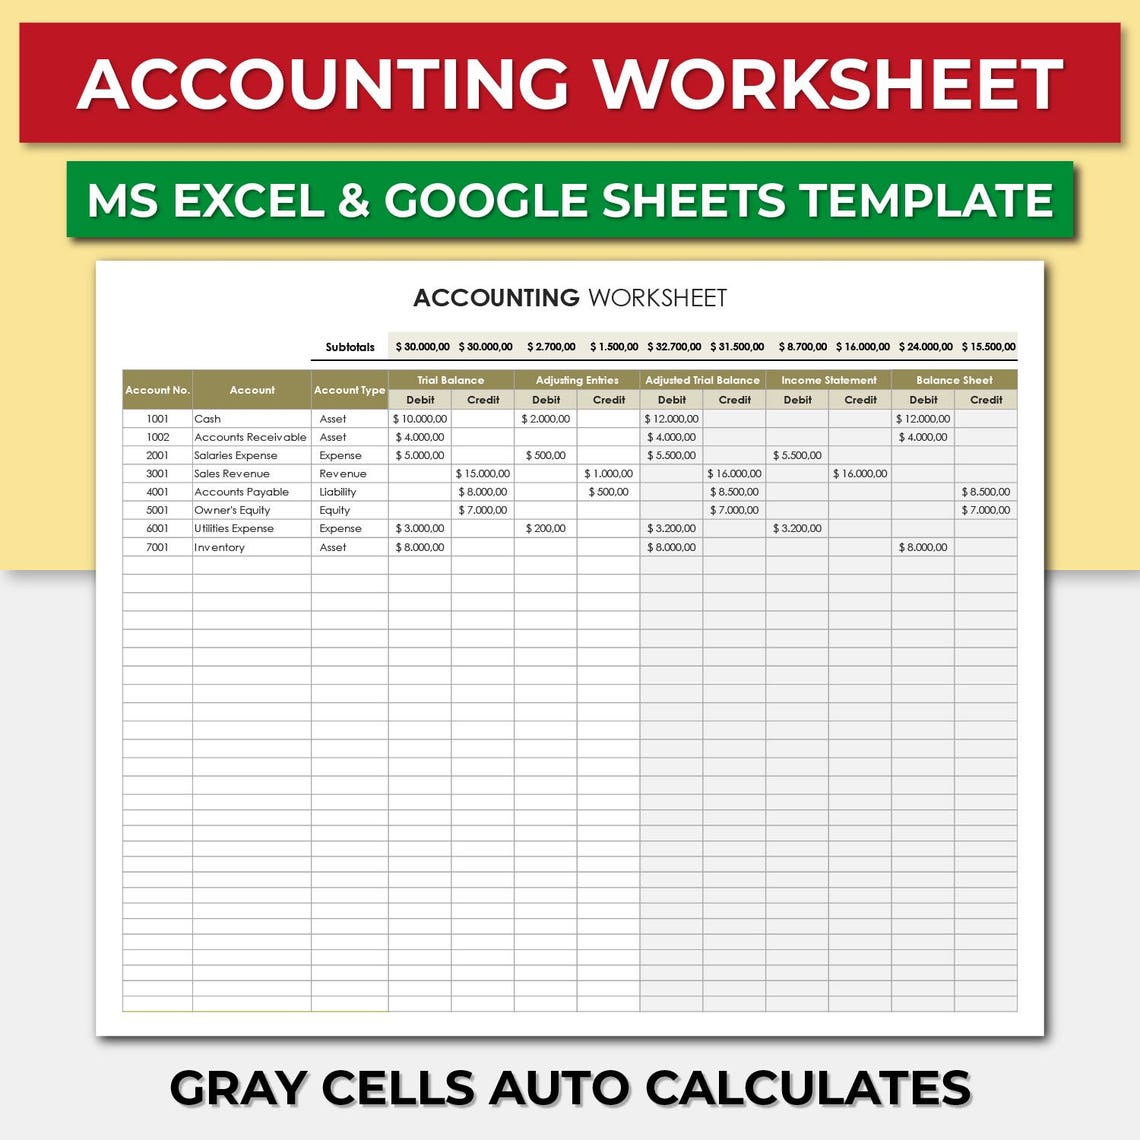
Accounting Worksheet Spreadsheet Template. Balance Sheet: Assets, Liabilities, and Equity ...
Accounting Worksheet Template Excel
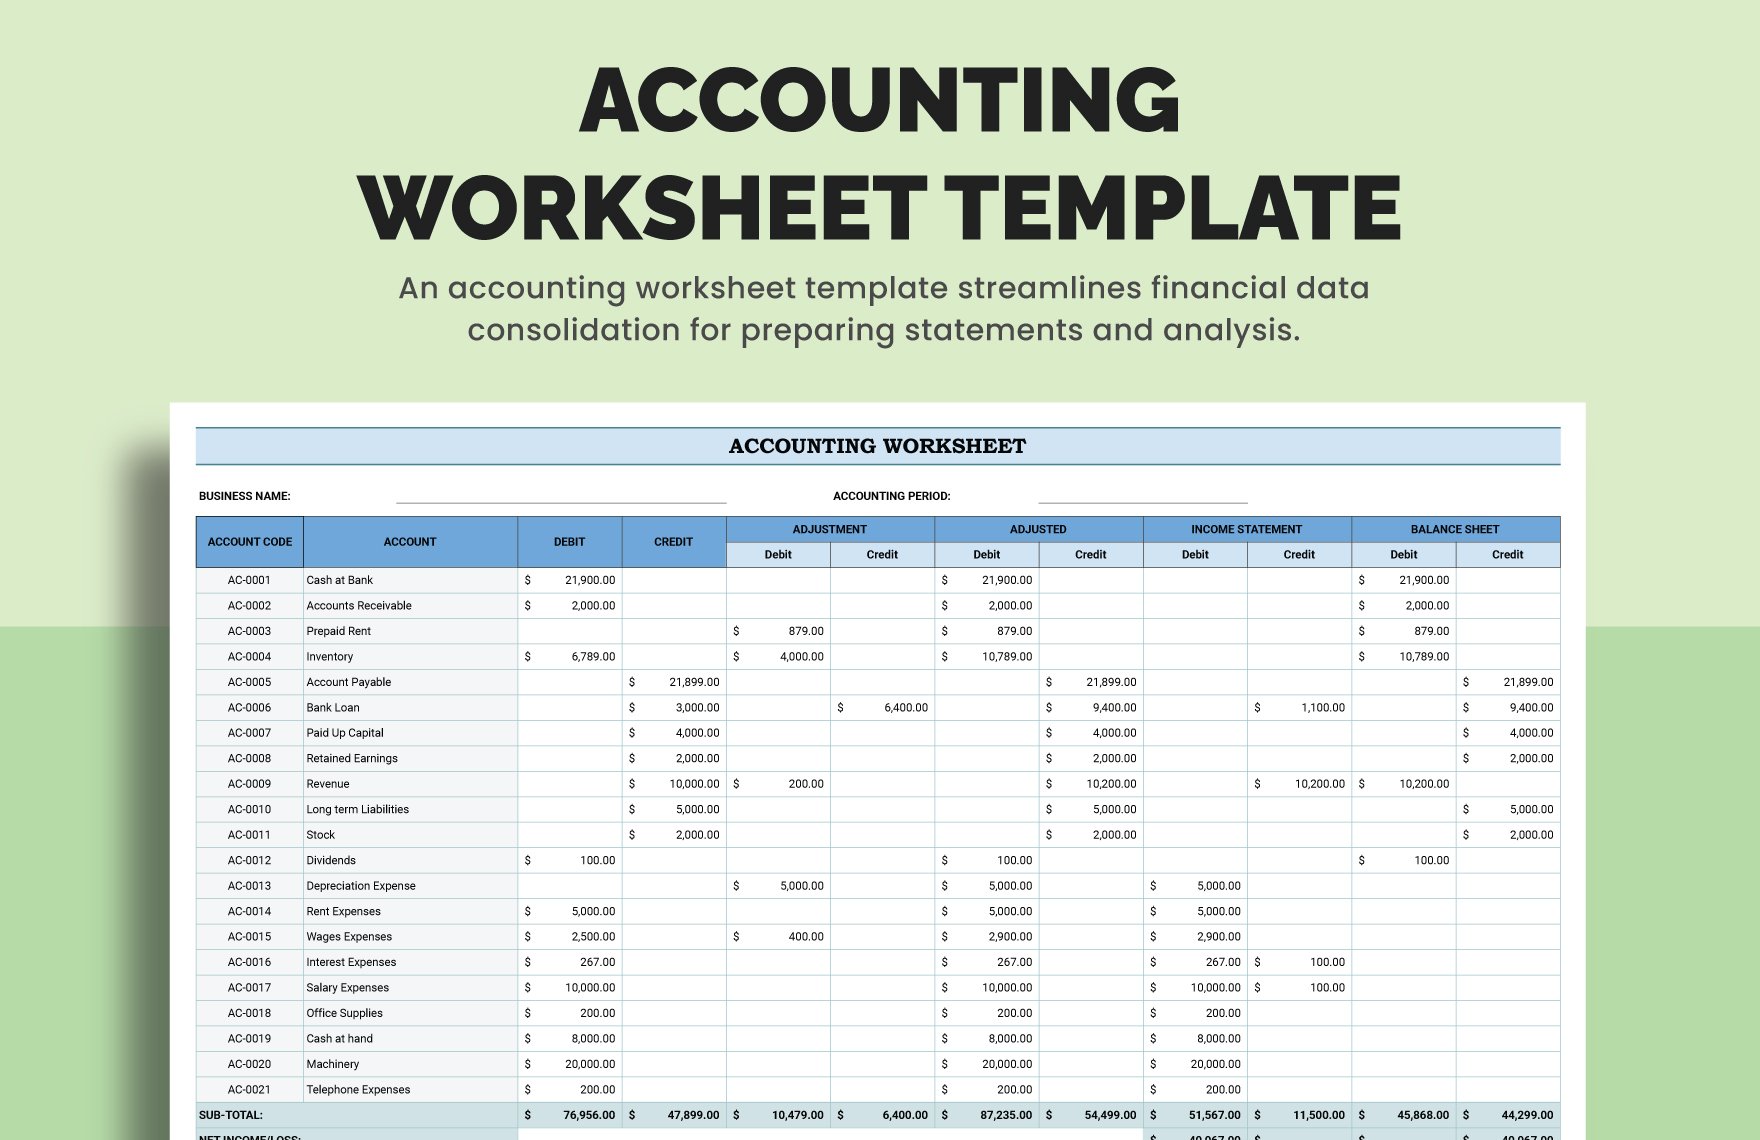
Accounting Worksheet Template in Excel, Google Sheets - Download | Template.net