Filling Out the Worksheet For Form 8812 Without Losing Your Mind
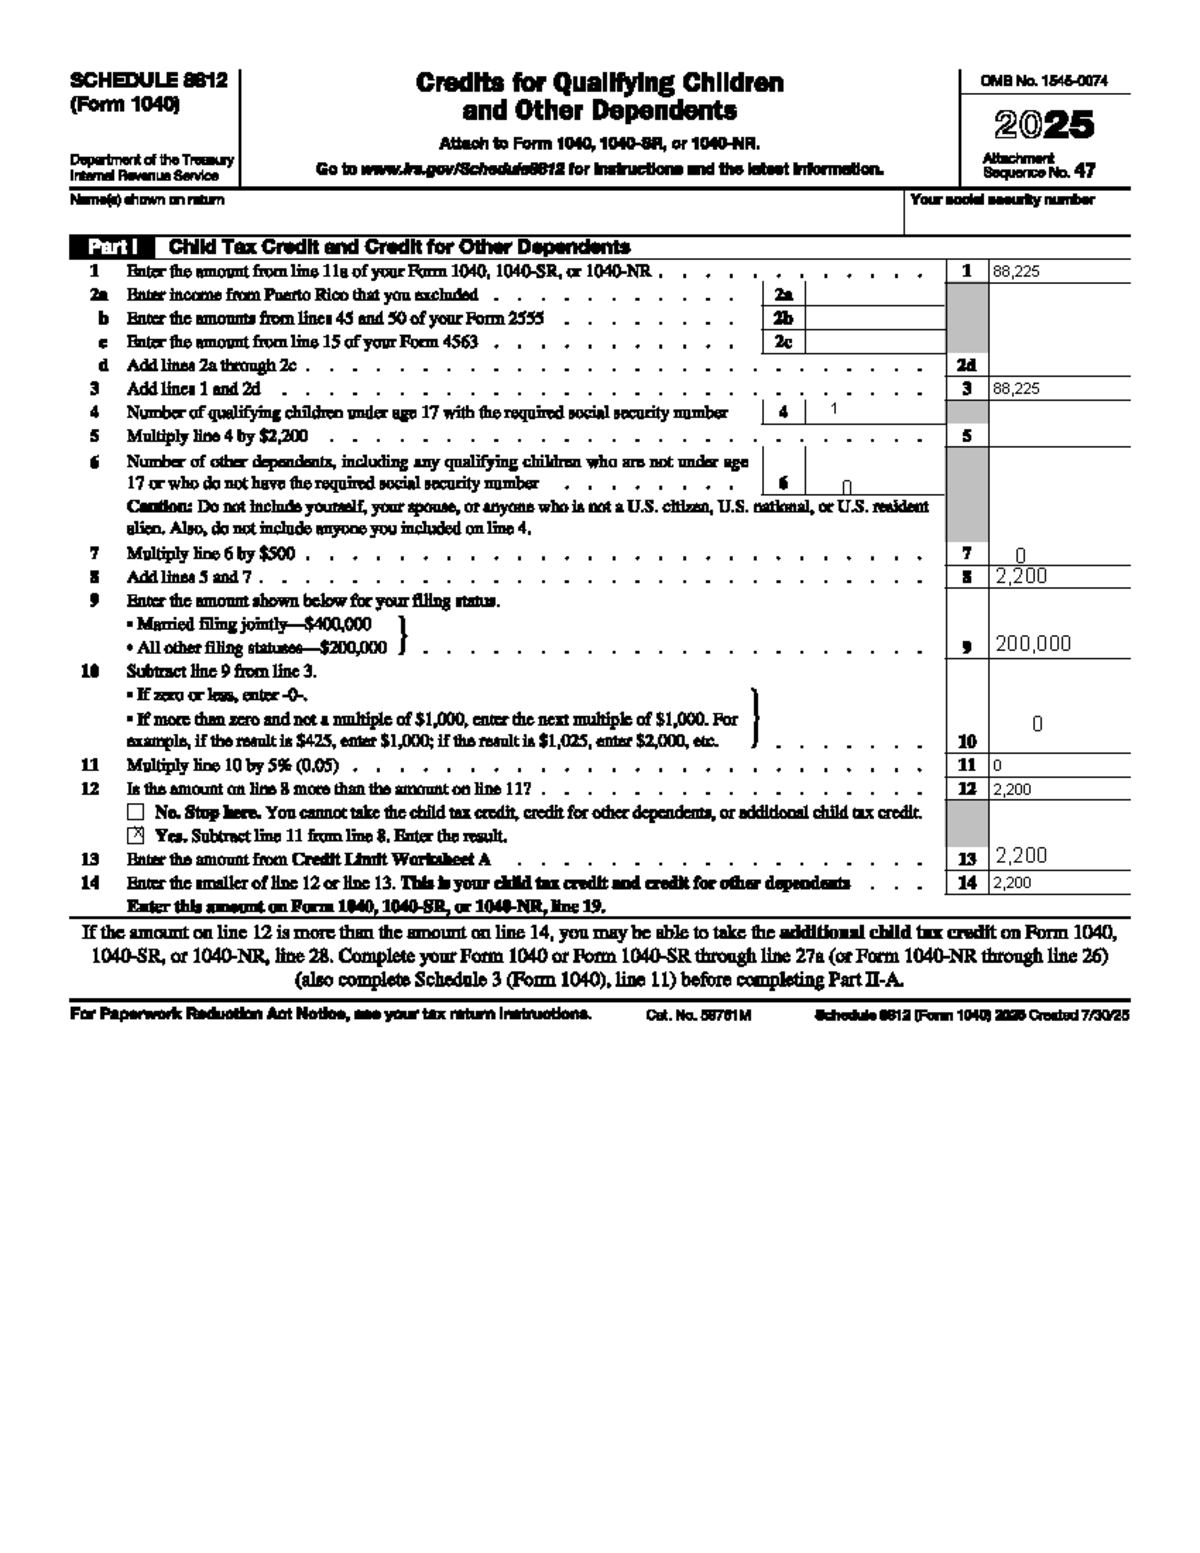
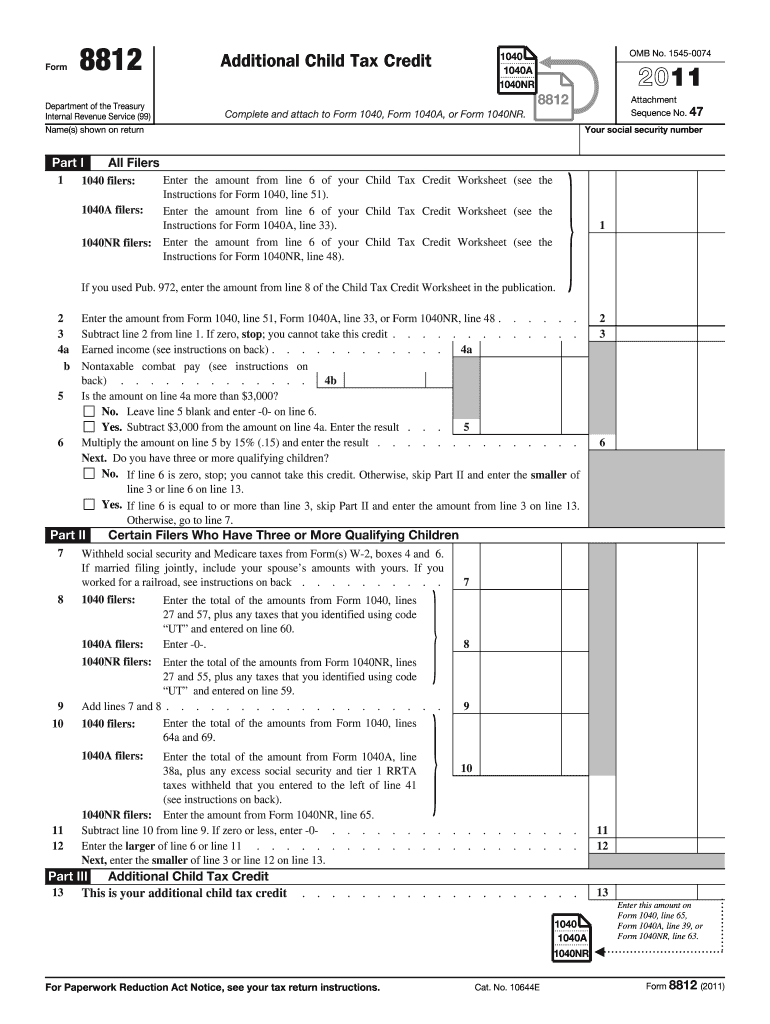
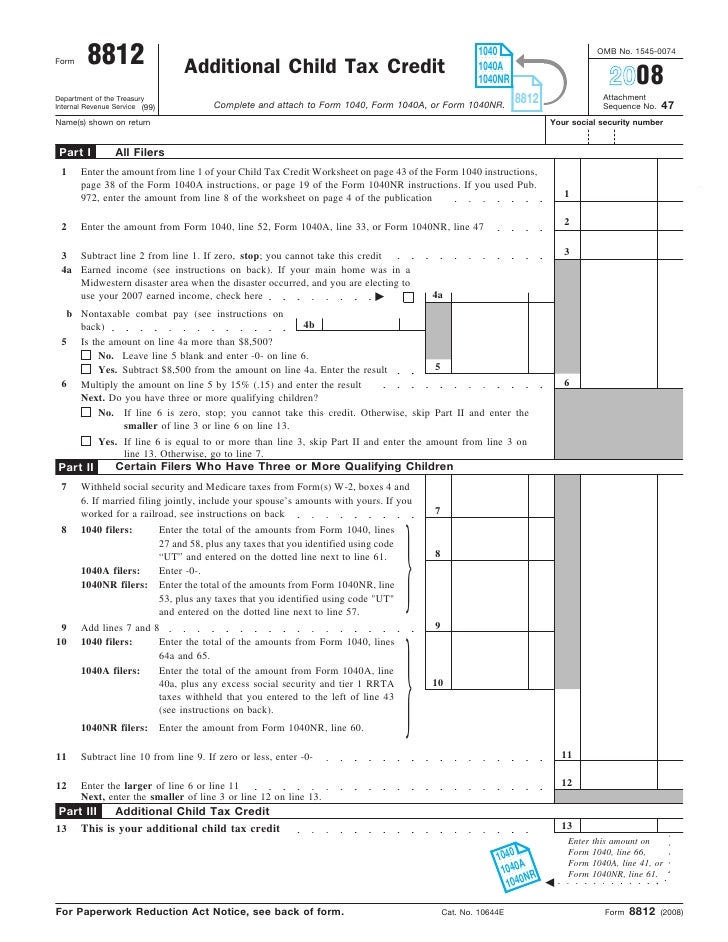
Form 8812 is the IRS form most people encounter when they're claiming either the child and dependent care credit or, historically, reconciling advance Child Tax Credit payments from 2021. The worksheet attached to it is where the actual math happens, and that is usually the part people get wrong. I have filled this out enough times across different tax seasons to know what trips people up, so here is what you actually need to know before you start entering numbers. The worksheet isn't a standalone form. It is a section built into or attached to Form 8812 that breaks down the calculation into manageable parts. Depending on which version you are using, it covers different scenarios. The current version handles the child and dependent care credit calculation. Older versions, particularly the 2021 variant, handled the reconciliation of advance monthly Child Tax Credit payments against the actual credit you qualified for on your full return. If you are working with the 2021 form, the worksheet asks you to compare what the IRS paid you throughout the year against what your actual credit should have been based on your income and filing status. If you received more than you were entitled to, you may owe money back. If you received less, you get the difference. The worksheet makes this comparison explicit line by line instead of leaving you to guess at your position.
The current child and dependent care version works differently. It guides you through determining your eligible expenses, applying the percentage based on your adjusted gross income, and arriving at the final credit amount. You generally fill out Form 2441 first if you are an employee claiming dependents care expenses, or Form 8812 directly if you are self-employed. The worksheet then translates those numbers into your actual credit.
How to Fill It Out Step by Step
Start by gathering your supporting documents before you touch the worksheet. For the current form, you need your W-2 showing dependent care benefits, any employer-sponsored care program details, receipts for care expenses, and the Social Security numbers or ITINs for every qualifying person. Without those identification numbers, the worksheet is useless because the IRS will reject the return anyway. For the 2021 reconciliation worksheet, you need your 2021 Form 1099-IR from the IRS showing total advance payments made to you, your actual 2021 tax return with the correct filing status and dependents, and any from the IRS account portal if you ever updated your information mid-year. I had a client once who missed this because the IRS had sent a notice about a change to their payment amount that they never acted on. The mismatch showed up clearly on the worksheet, but only after the original filing was already submitted. Fixing it required an amended return and took about three weeks of back and forth with the IRS correspondence center. Do not skip checking your IRS account online before you start filling anything out. On the worksheet itself, follow the sequence exactly as printed. Do not jump ahead. The lines build on each other. Line one usually captures your total eligible expenses up to the statutory limit — $3,000 for one qualifying person or $6,000 for two or more. Line two applies the income-based percentage, which ranges from 20 to 35 percent depending on your AGI. The worksheet calculates the reduction automatically if your income pushes you into a lower percentage bracket. Line three or four, depending on the version, brings in any employer-provided dependent care benefits that reduce your eligible expense pool.
Get the Full Details

If you are dealing with the 2021 advance payment reconciliation, the worksheet has a different flow. You enter your total advance payments from the 1099-IR, then calculate your actual Child Tax Credit on your return, then subtract one from the other. The result tells you whether you have a balance due or an additional refundable amount. The worksheet marks which line to follow based on whether your income falls above or below certain thresholds.
Pitfalls That Are Easy to Miss
The most common error I see is entering the wrong filing status. The credit amount and the income phaseout thresholds change significantly between single, head of household, and married filing jointly. A wrong filing status can shift your phaseout range by several thousand dollars and change your final credit by hundreds. Double-check it against your actual return before moving forward. Another frequent mistake involves the qualifying person definition. Not everyone in your household qualifies. A dependent must meet relationship, residency, and age tests. A friend's child who stays with you on weekends does not count unless they meet the dependency tests. The worksheet does not validate this for you. It assumes you know who qualifies and will just accept whatever number you type in. For the 2021 reconciliation version specifically, people often forget that modified AGI matters for the phaseout calculation, not regular AGI. The difference can be substantial if you have items like foreign earned income exclusions or employer-provided adoption benefits. Using the wrong income figure puts your phaseout in the wrong range and generates an incorrect credit amount.
There is also the issue of multiple employers. If your spouse worked for two different employers during the year and both provided dependent care benefits through separate accounts, you need to combine those benefit amounts correctly on the worksheet. I once saw someone enter only one employer's information and end up claiming a credit they were not entitled to because the benefit limit was already partially used. The IRS caught it on review and issued a correction notice months later.

Where to Get the Form and Worksheet
The official source is always irs.gov. Search for Form 8812 on that site and you will find the current version along with its instructions, which contain the worksheet. The 2021 version is archived but still accessible through the same search. Avoid third-party sites that claim to offer fillable PDFs unless you verify the document matches the IRS version exactly. I have seen versions floating around with outdated line numbers that cause confusion and incorrect calculations. If you use tax preparation software, the worksheet is typically generated automatically behind the scenes. The software handles the line-by-line logic and only surfaces the final credit amount on your return. This is convenient but worth understanding manually at least once so you can catch errors when the software gets something wrong, which it does occasionally, especially with edge cases involving multiple employers or incomplete 1099-IR data.
When You Should Absolutely File a Manual Worksheet Instead of Relying on Software
There are situations where automated tools will give you the wrong answer without warning. If your circumstances involve non-standard dependents, split custody arrangements, or employer benefits that do not appear on a standard W-2, the software may fall back to default assumptions. In those cases, working through the worksheet line by line gives you visibility into what assumption the program made and whether it is correct. Another scenario is when you have received notice from the IRS about a discrepancy. The notice will reference specific worksheet lines and numbers. Going through the worksheet manually lets you cross-reference the IRS position against your own records and identify exactly where the disagreement lies. This saves time compared to calling the IRS with a vague complaint and no documentation to back it up. The worksheet for Form 8812 is not complicated in theory, but the devil is in the details. Getting the qualifying person criteria right, using the correct income figure, and matching your documentation precisely to the worksheet lines will save you from revisions and penalties down the road. Take the time to verify each entry against your source documents before you finalize anything.