Monthly financial tracking doesn't have to be painful
Most people I work with use spreadsheets for their budgeting and they are doing it wrong. They create these massive, over-engineered monstrosities that take three hours to update and then get abandoned within six weeks because the friction is too high. The best system is the one you actually use. That's where a properly built
Worksheet Monthly comes in, but only if you build it with the right instincts.
I've been setting up these kinds of financial tracking sheets for clients for over a decade now, and the pattern is always the same. People obsess over features instead of workflow. They want conditional formatting, cascading dropdowns, and pivot tables before they've even set up a basic category structure that matches their actual spending habits. It's backwards. Start with the categories first. Everything else is secondary.
Worksheet Monthly: The Structure That Actually Sticks
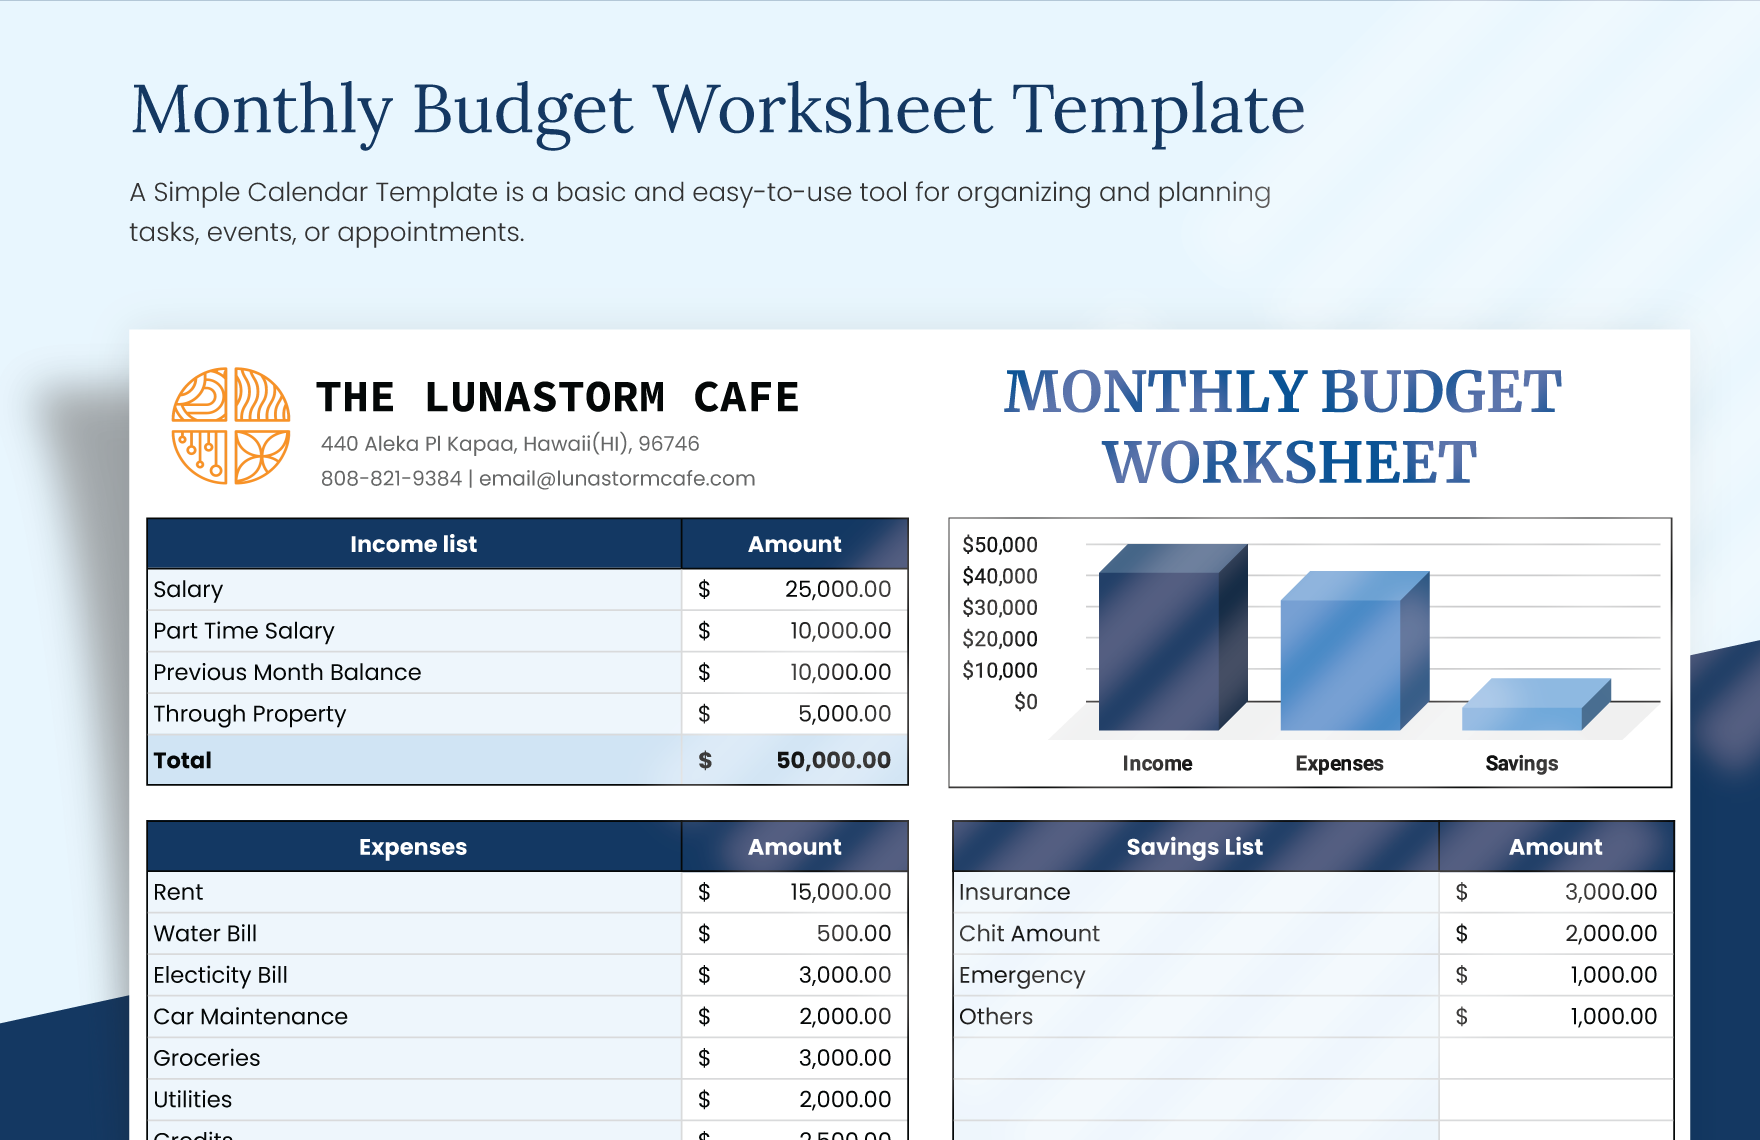
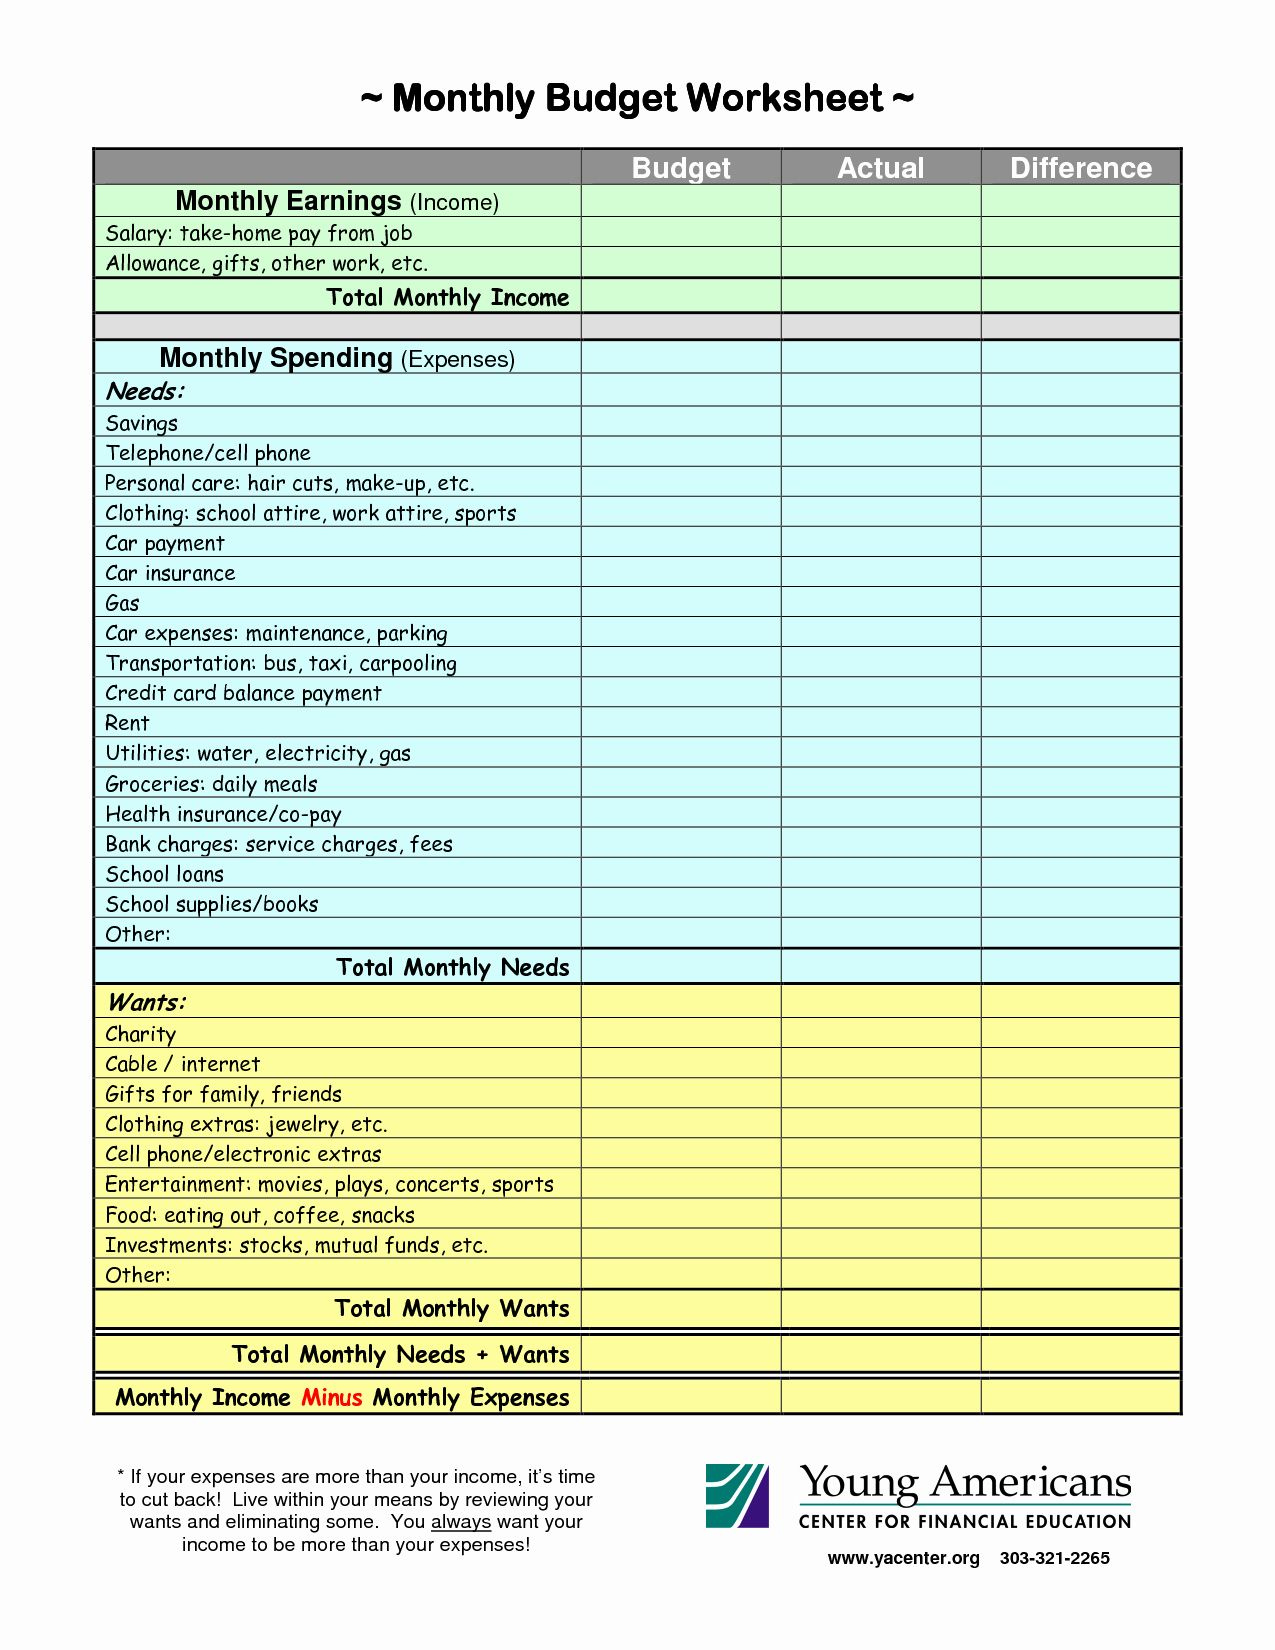
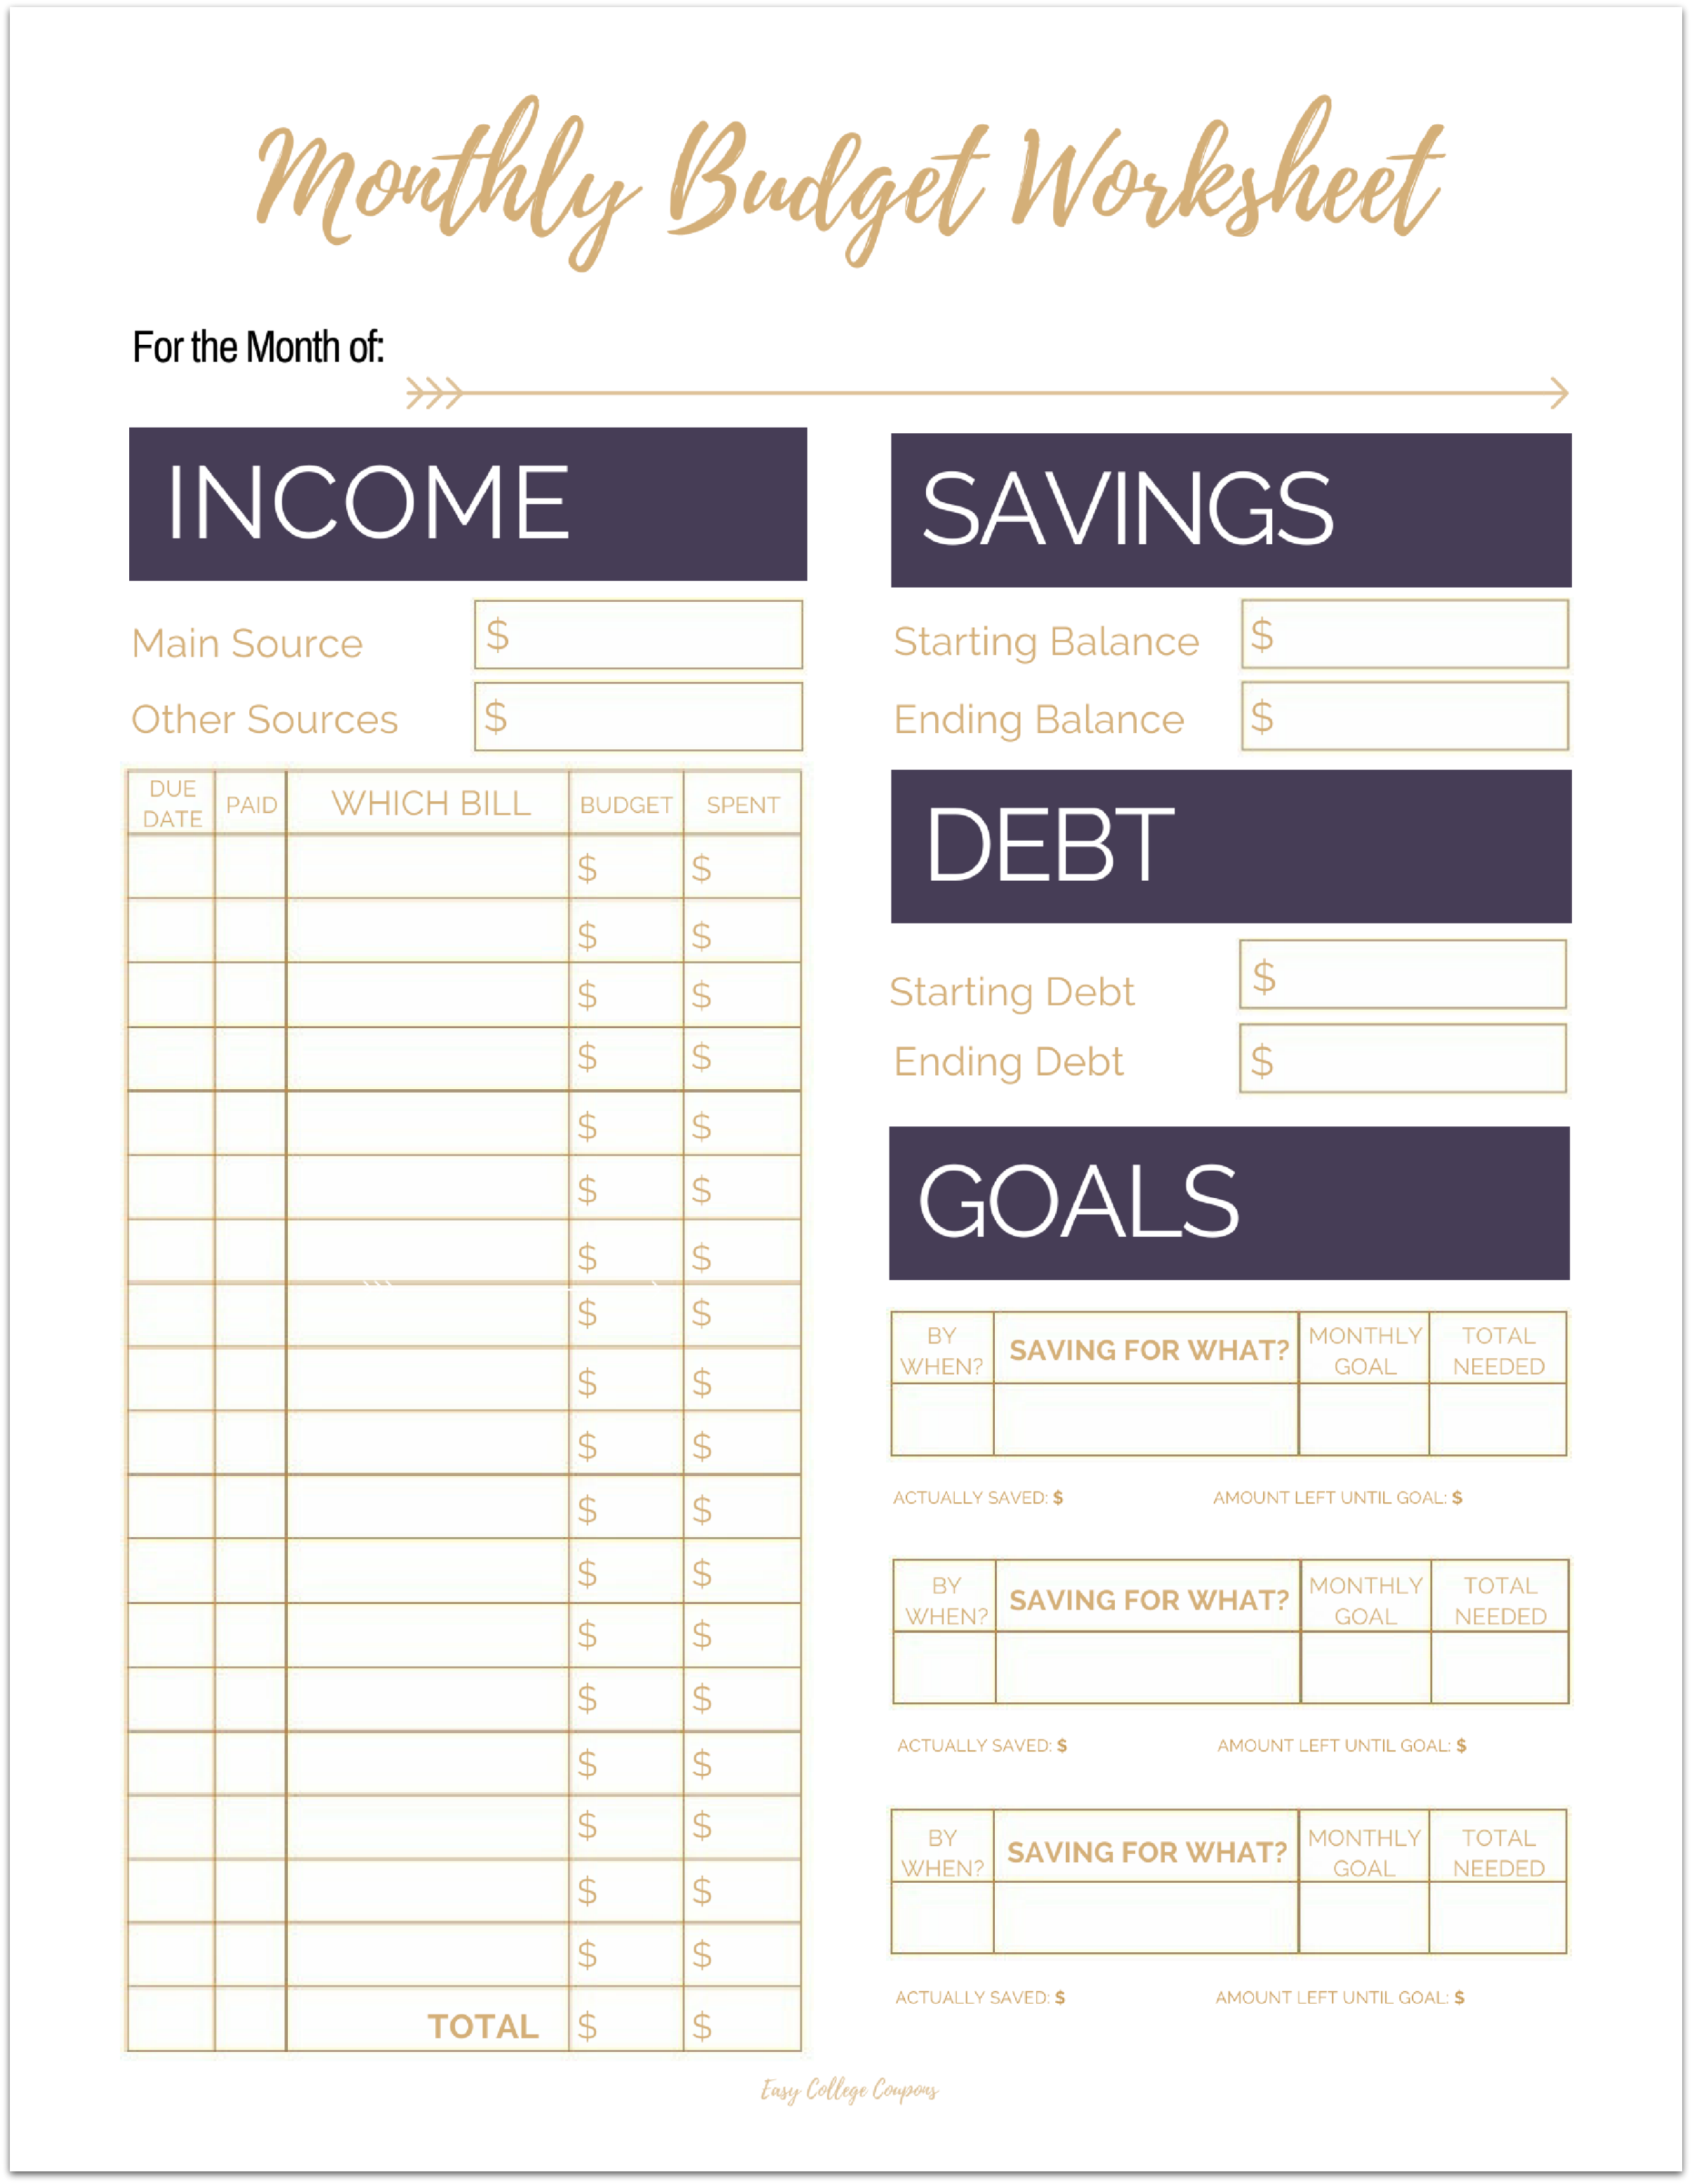
A working monthly worksheet needs three core sections. Income on the left side or top row depending on your preference, fixed expenses below that, and variable spending categories in the main body. Keep it on one sheet if possible. Every time you add another tab, you're adding a step to the process and that compounds over thirty days until you're skipping updates entirely.
Here's the specific layout I always recommend: column A for category names, column B for budgeted amount, column C for actual spending, column D for the difference, and column E for notes. Simple. That's it. You don't need fourteen columns of color coding and data validation rules. When I built my own personal tracking sheet around 2018, I added seventeen columns across multiple sheets because I thought it looked impressive. I switched back to five columns within a month. The extra complexity was slowing me down more than it helped.
Getting the Formulas Right
The SUMIF function is your most important tool here. Use it to pull transactions from your raw data into the summary rows based on category matching. Something like =SUMIF(raw_data!D:D, A5, raw_data!E:E) will sum all transactions in your raw data tab that match the category in cell A5. Put that in your difference column and use a simple subtraction like =B5-C5.
One thing beginners consistently mess up is the budgeted amount column. They hardcode the numbers. You should use a separate settings or assumptions tab where you define your monthly budgets, then reference those cells from your main worksheet. That way when you adjust your budget mid-month you change it in one place and everything updates automatically. I've lost count of the number of spreadsheets I've inherited where the person had updated their spending but not their budget and the variance column was showing negative numbers everywhere even though they were under budget. The disconnect between the assumptions tab and the active calculation creates silent errors that compound over time.
A Problem I Ran Into and How I Fixed It
Last year I was helping someone who was trying to reconcile credit card statements with their Worksheet Monthly template. The issue was that credit card payments spanned two months. A purchase made on January 31st might not appear on the statement until February 7th, which completely threw off the monthly comparison they were trying to maintain. The standard approach of matching calendar month to calendar month doesn't work cleanly with revolving credit because of statement cycle lag.
The workaround was to add a reconciliation period column that tracked the statement closing date rather than the purchase date. Instead of forcing everything into a January or February bucket, I created a helper column that mapped each transaction to its actual statement period using a simple lookup based on the statement end date. It added about five minutes of setup work but eliminated the confusion that was making them second-guess whether their numbers were right every single month.
Where Worksheet Monthly Approaches Fall Down
There are scenarios where a static spreadsheet simply cannot handle the complexity. If you have more than three or four income sources, or if your variable expenses are deeply interconnected in ways that require real-time adjustments, you're going to hit the wall. The spreadsheet will become slow, the formulas will break when you insert rows, and you'll spend more time maintaining the tool than using it.
In those cases, dedicated budgeting software like YNAB or even a properly configured Google Sheets setup with App Script automations is the better choice. But for the vast majority of people managing a household budget or small business finances with a moderate number of transactions per month, a well-built monthly worksheet is faster, more transparent, and doesn't require a subscription.
The Download and Implementation
You can find a clean starting template at
spreadsheets.example.com/worksheet-monthly. It has the three-tab structure I described with the income, expense, and assumptions sections already configured. The formulas are locked in the protection settings so you can't accidentally break them, but the category cells are fully editable.
I'd suggest spending twenty minutes on day one customizing the categories to match your actual spending patterns. Don't use generic labels like "miscellaneous" because that category swallows everything and you learn nothing from your data. Break it into whatever feels granular enough to be useful without being tedious. For most people that's between five and ten expense categories total.