The Basics Nobody Warns You About
A covered call is when you own a stock and sell a call option against it. That's literally it. You get paid a premium for letting someone else buy your shares at a price you set, and if the stock doesn't hit that price by expiration, you keep both the shares and the premium. Simple in theory. The execution is where people burn themselves. I'm going to walk through Writing A Covered Call Option in the way I actually do it, which means skipping the textbook version and showing you what happens when the market gets weird.Writing A Covered Call Option: The Practical Breakdown
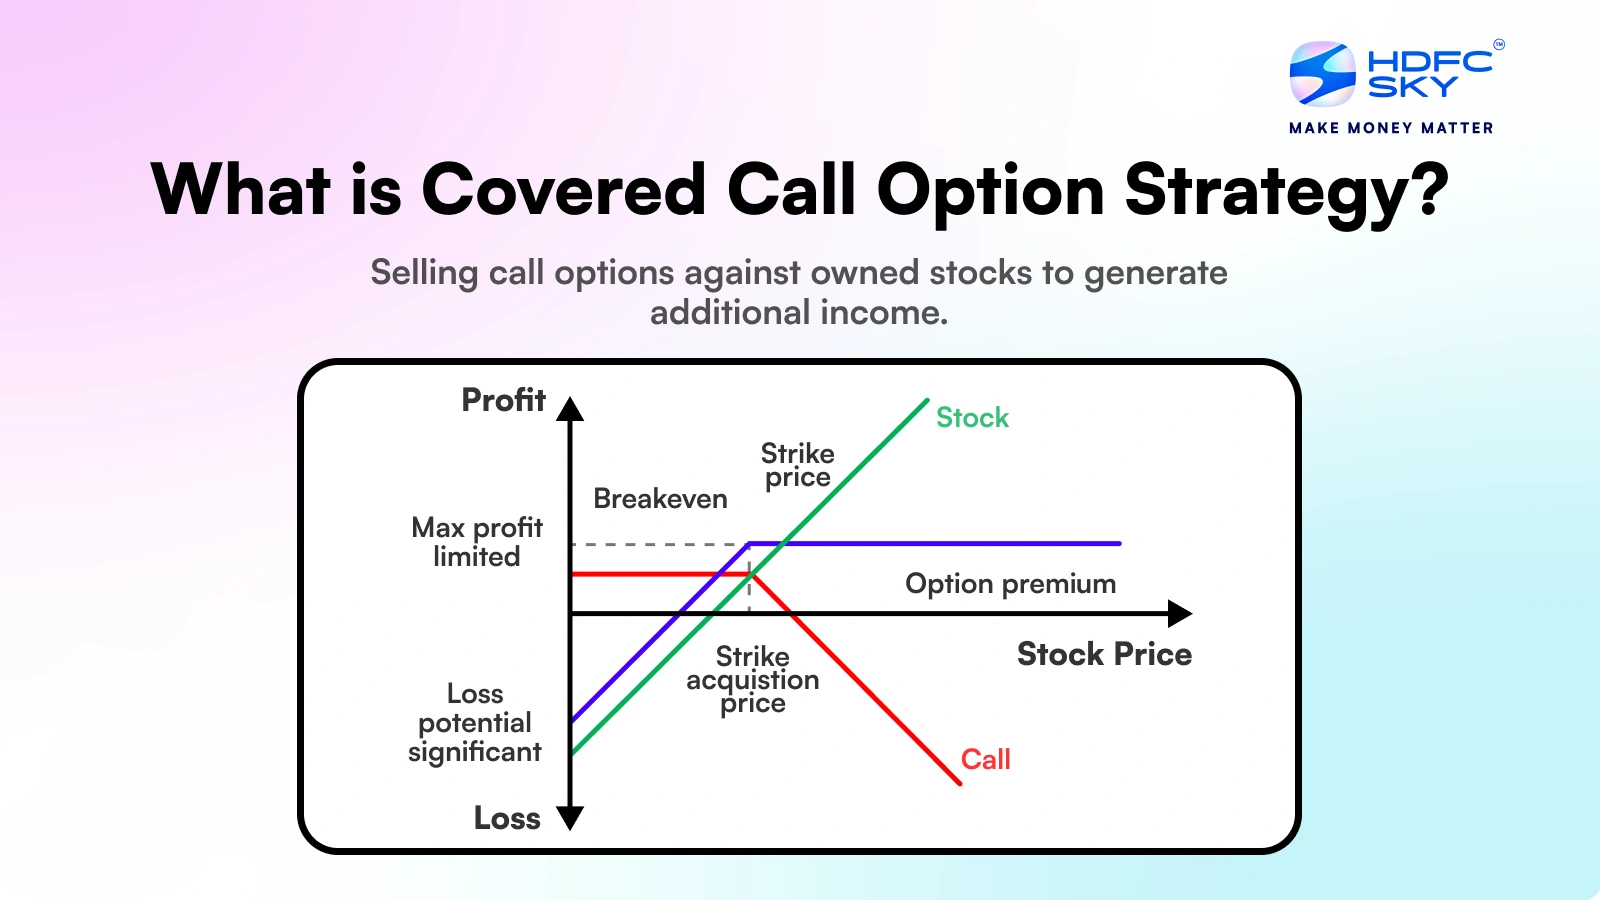
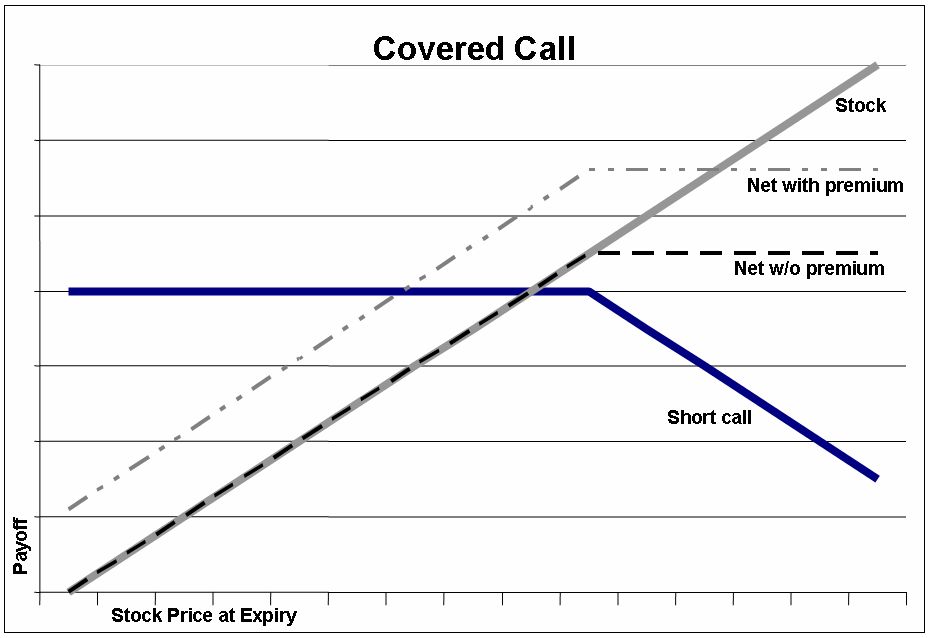
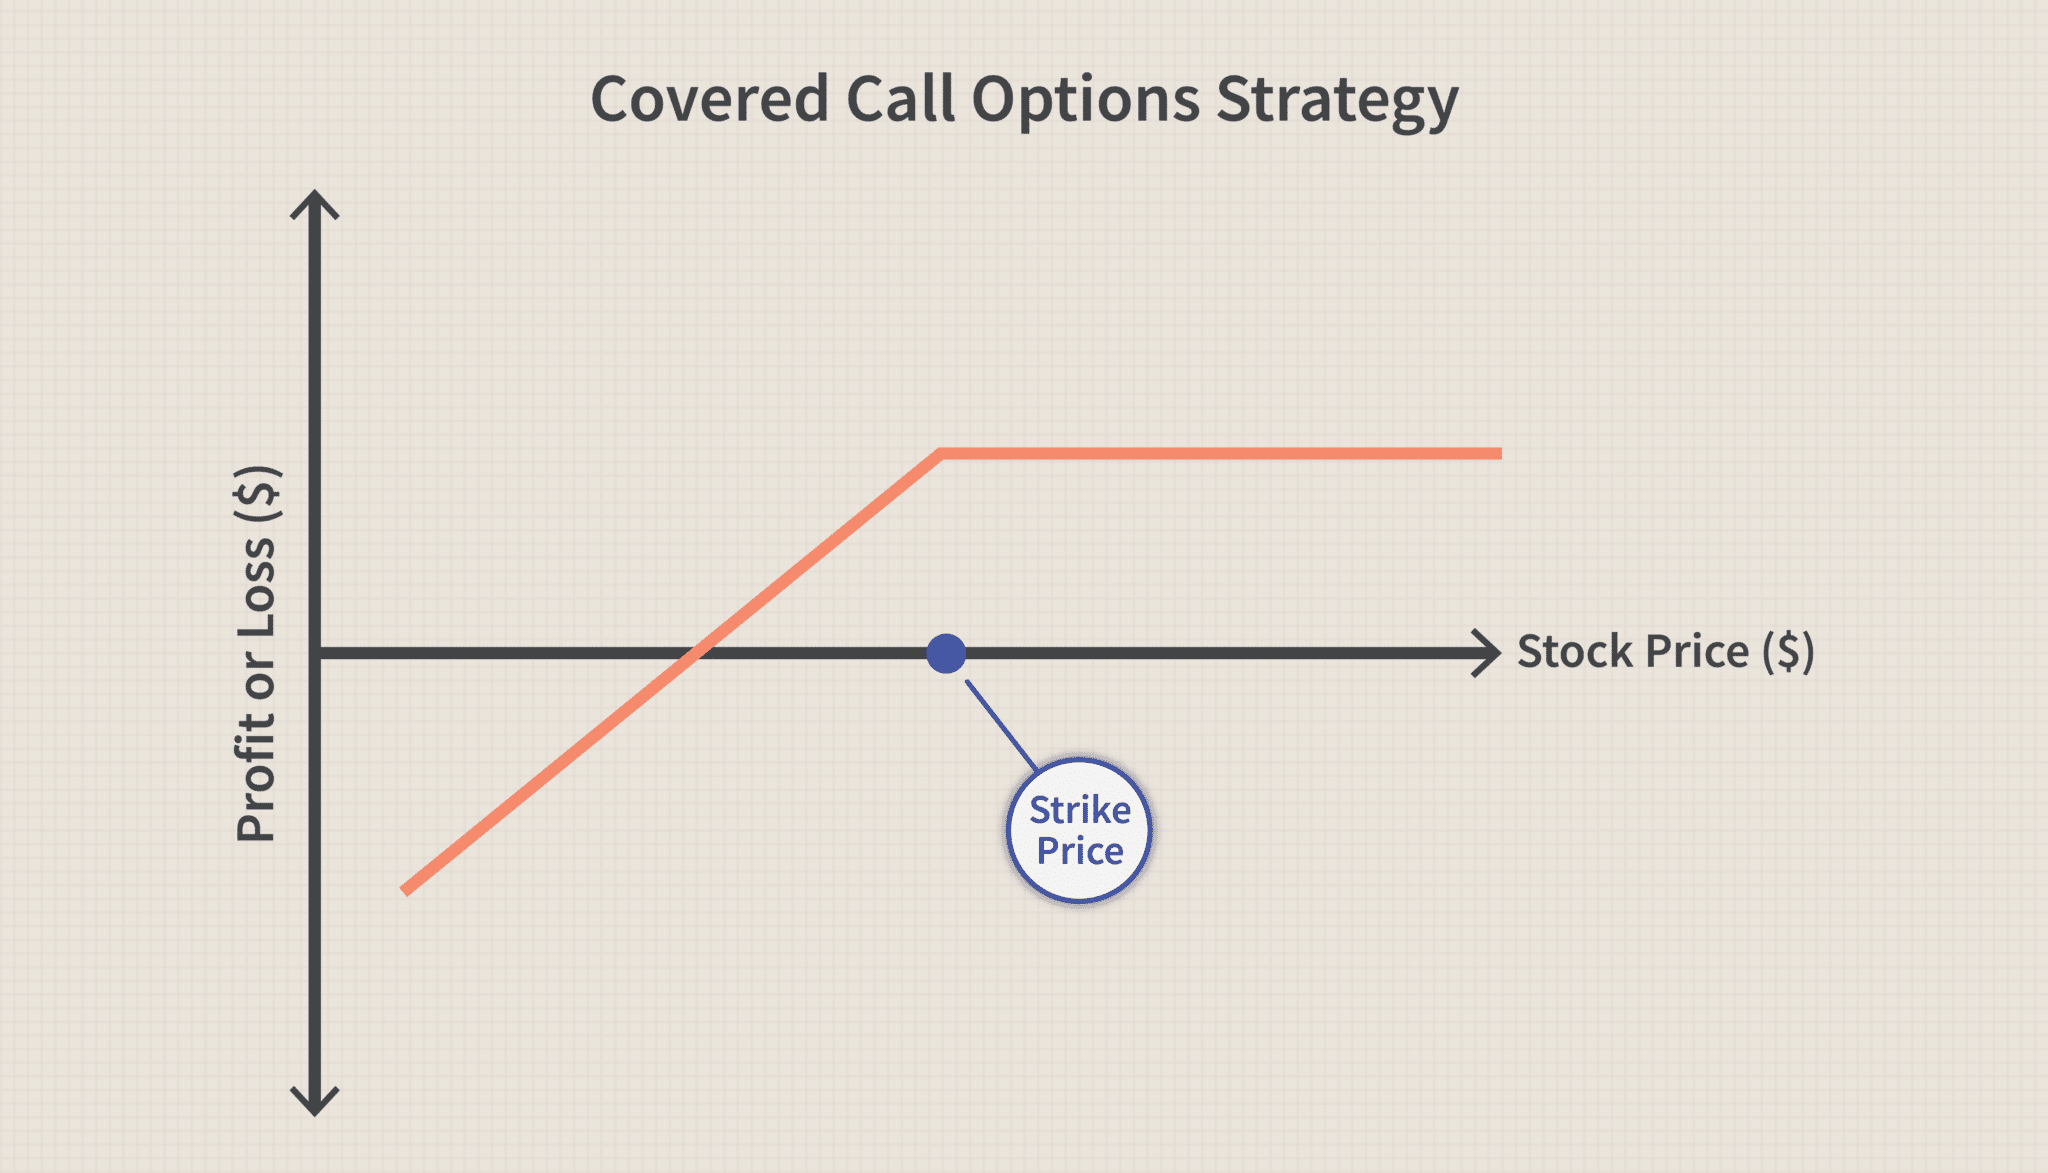
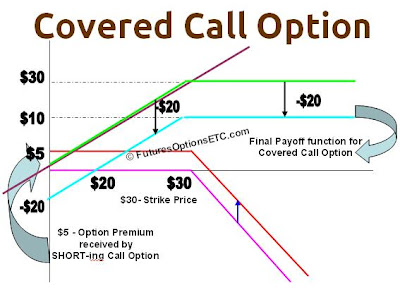
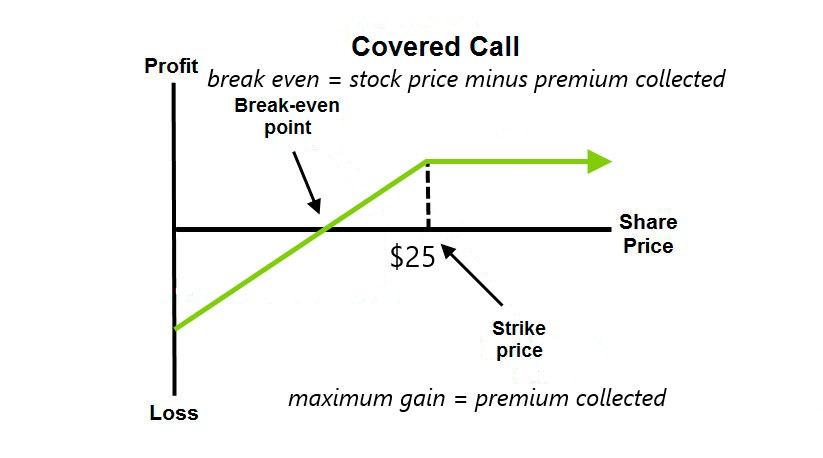
Here's the core mechanics. Let's say you own 100 shares of a stock currently trading at $50. You sell one call option with a strike price of $55 that expires in 30 days, and you receive a $1 premium per share, so $100 total for the contract. If the stock stays below $55, your call expires worthless, you keep the $100, and you still own your shares. You can repeat the process next month. If the stock shoots past $55, your shares get called away at $55, and you pocket the $5 premium per share on top of your shares being sold at that price. Your total return becomes the gain from $50 to $55 plus the $1 premium, or $600 on a $5,000 position. That's a 12% return in 30 days if everything goes according to plan. Now let's talk about what goes wrong. The most common mistake I see people make is choosing a strike price based on the current stock price rather than the underlying thesis for why they own the stock in the first place. If you picked the stock because you thought it was going to $70, selling a $55 call is actively sabotaging your own investment. You're capping your upside at $55 just to pick up a couple percent in premium. It happens constantly. I made it myself early on with a biotech position. I thought the approval news was solid, but I also thought the price was stagnant so I sold calls against it. The stock gapped up 18% after the news. I was relieved my shares got called away when they were at $60. They were still way below where I thought they were heading. Lesson learned.
Timing and Expiration Selection
The expiration date you pick matters more than most people realize. Most beginners default to the nearest monthly expiration, usually 30 days out, because there's a whole community of traders talking about 30-day DTE (days to expiration) as the optimal window. There's some logic to it because theta decay accelerates in the last 30 days. But relying on it blindly will hurt you. If you sell a 30-day call right before an earnings report and the stock gaps hard, you've just created a situation where your assignment risk jumps dramatically. The stock could easily blow through your strike. I once ran into this with a semiconductor name. I sold a covered call expiring two weeks before earnings. The premium was thick, like $2.50 per share, because implied volatility was elevated ahead of the report. I figured even if the stock moved, I'd probably get called away at a gain. The stock didn't miss the earnings but it did drop 14% on a guidance miss. My call went deep in the money, but because I was short a call, the put side of things wasn't a concern. The real problem was that the stock then continued to grind down over the following weeks and I had already been assigned. I sold my shares at the strike, which was still above what the stock was trading, but I missed the full recovery because I'd already exited. I ended up re-buying the shares at a higher price later just to get back in. That cost me more than the premium I collected ever would have. The workaround I use now is straightforward. I check the economic calendar and any company-specific events before selling any call. If there's an earnings report, product launch, FDA decision, or even a major conference coming up within the expiration window, I either skip the trade entirely or I extend the expiration to at least a few weeks past the event. The premium you leave on the table is usually worth it to avoid the headache.
Strike Selection Is Not One-Size-Fits-All
The standard advice is to sell at a strike that's above the current price, maybe 5 to 10 percent out of the money. That's fine for income generation when you're not trying to pick winners. But if you actually believe in the stock, you should think about it differently. There are two common approaches and both have real drawbacks depending on the situation. The first approach is the conservative one. Sell a strike well above the current price, maybe 10 to 15 percent OTM. You'll collect less premium, but you're far less likely to have your shares called away prematurely. This works if you're holding the stock for dividend income and the call is just a minor enhancement. The downside is obvious. You give up most of the upside, which is exactly the problem most people have with covered calls. The second approach is more aggressive. Sell a strike closer to the money, maybe 2 to 5 percent OTM, or even at the money. You collect a much bigger premium, sometimes double or triple what you'd get with a deeper OTM strike. The tradeoff is assignment risk. If the stock moves even slightly in your favor, you could get called away. The nuance most beginners miss here is that assignment doesn't always happen automatically at expiration. Brokers sometimes let shares ride past expiration, and you can get assigned anytime the option is in the money after the market closes on any business day leading up to expiration. That means you're not safe until expiration actually passes. I learned this the hard way during a volatile stretch in 2022. I was sitting on a position where the stock had moved up past my strike about five days before expiration. I got a notification that my call was deep ITM and I was bracing for assignment. Instead, the broker rolled the option to the next expiration cycle automatically because I had the roll feature enabled. That saved me from getting called away at a price I was happy to exit at, and I collected another premium on the new contract. It was a relief, but it also meant I had less upside participation over a wider time frame. I couldn't control when the roll happened. It just happened.
Get the Full Details

The Real Math Behind Covered Calls
People often calculate covered call returns without factoring in opportunity cost. Here's what I mean. If you own a stock trading at $100 and you sell a $105 call for a $2 premium, your effective sell price is $107. If the stock goes to $120, you make $20 on the stock plus $200 in premium, for a total gain of $220 on a $10,000 position. That's a 2.2% return. If the stock stays at $100, you make $200 in premium, which is a 2% return. But you might be ignoring that the same $10,000 could have earned more by simply holding the stock and doing nothing. The covered call strategy only adds value if the stock either stays flat or rises moderately. If it runs hot, you underperform by a wide margin. The calculation gets more interesting when you factor in tax efficiency. In many jurisdictions, covered call premiums are treated as short-term capital gains regardless of how long you held the underlying stock. That means if you're holding a stock that's already been taxed at long-term rates, adding covered calls can convert part of your gain into short-term rates, which is usually worse. I don't recommend selling covered calls inside tax-advantaged accounts unless you're purely focused on the mechanics and not worried about the tax drag. In a taxable account, it can meaningfully affect your after-tax return over time.
When Covered Calls Fail Completely
There are specific scenarios where writing covered calls is a terrible idea, and I'm not being dramatic about this. If you own a stock that has high downside risk and you sell calls to generate income, you're essentially buying insurance that you won't be hit by a disaster while standing in a minefield. The premium you collect might be a few percent, but if the stock drops 30%, that premium disappears and you're left holding a much larger loss. I once held a mid-cap tech stock during a sector rotation. The stock was steady for months and I sold covered calls every 30 days. The premiums added up to maybe 8% annually. Then the sector rotated hard and the stock dropped 40% in three weeks. My call premiums were irrelevant. I lost far more than I ever collected. The only reason I didn't lose even more is that I had already been called away on my most recent contract at a small gain. I still had to rebuy the shares at a much higher price than the bottom because the market had already moved. It was a painful reminder that covered calls don't protect against downside. They protect against stagnation. That's the main thing I wish more people understood before they started.
A Better Alternative for Some People
If you're looking for income but want some downside protection, consider a collar instead. You own the stock, you sell a covered call, and you use part of the premium to buy a protective put below the current price. The put acts as insurance. It costs money, but the call premium partially funds it. The net result is a capped upside and a floored downside. It's more complex than a straight covered call, but it's the right move when you're worried about a crash while still wanting to generate income. I started using collars on positions where I had a high conviction view but also recognized that the broader market was expensive and vulnerable. The collar structure lets you sleep better at night, even if you give up some upside. The tradeoff is real. You're paying for protection, and sometimes that protection is expensive depending on where implied volatility sits. During high IV environments, puts can cost a lot, and the collar becomes too expensive to justify. During low IV periods, it's cheap and effective. Check the VIX and the individual stock's implied volatility level before deciding whether a collar makes sense for a given situation.
Final Notes
Writing A Covered Call Option is a straightforward strategy, but the devil is in the details. Pick your expiration carefully. Watch for events that could move the stock. Understand that your upside is capped by design. Don't sell calls against a stock you strongly believe will run higher unless you're prepared to watch it go past your strike and miss the move. And never assume the premium you collect is a free lunch. It's compensation for giving up upside, and sometimes it's not enough compensation for the risk you're taking.