The Practical Reality of Demand Letters
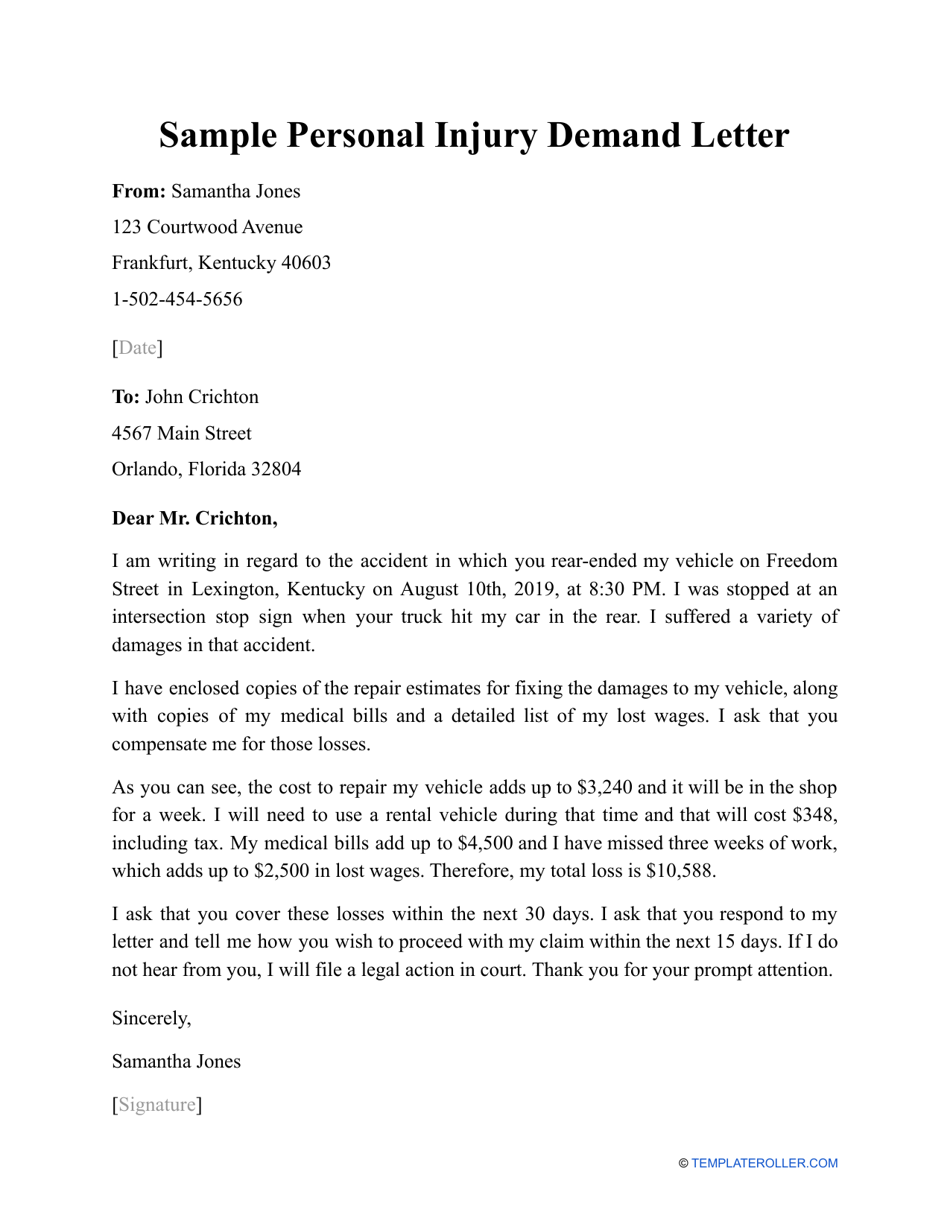
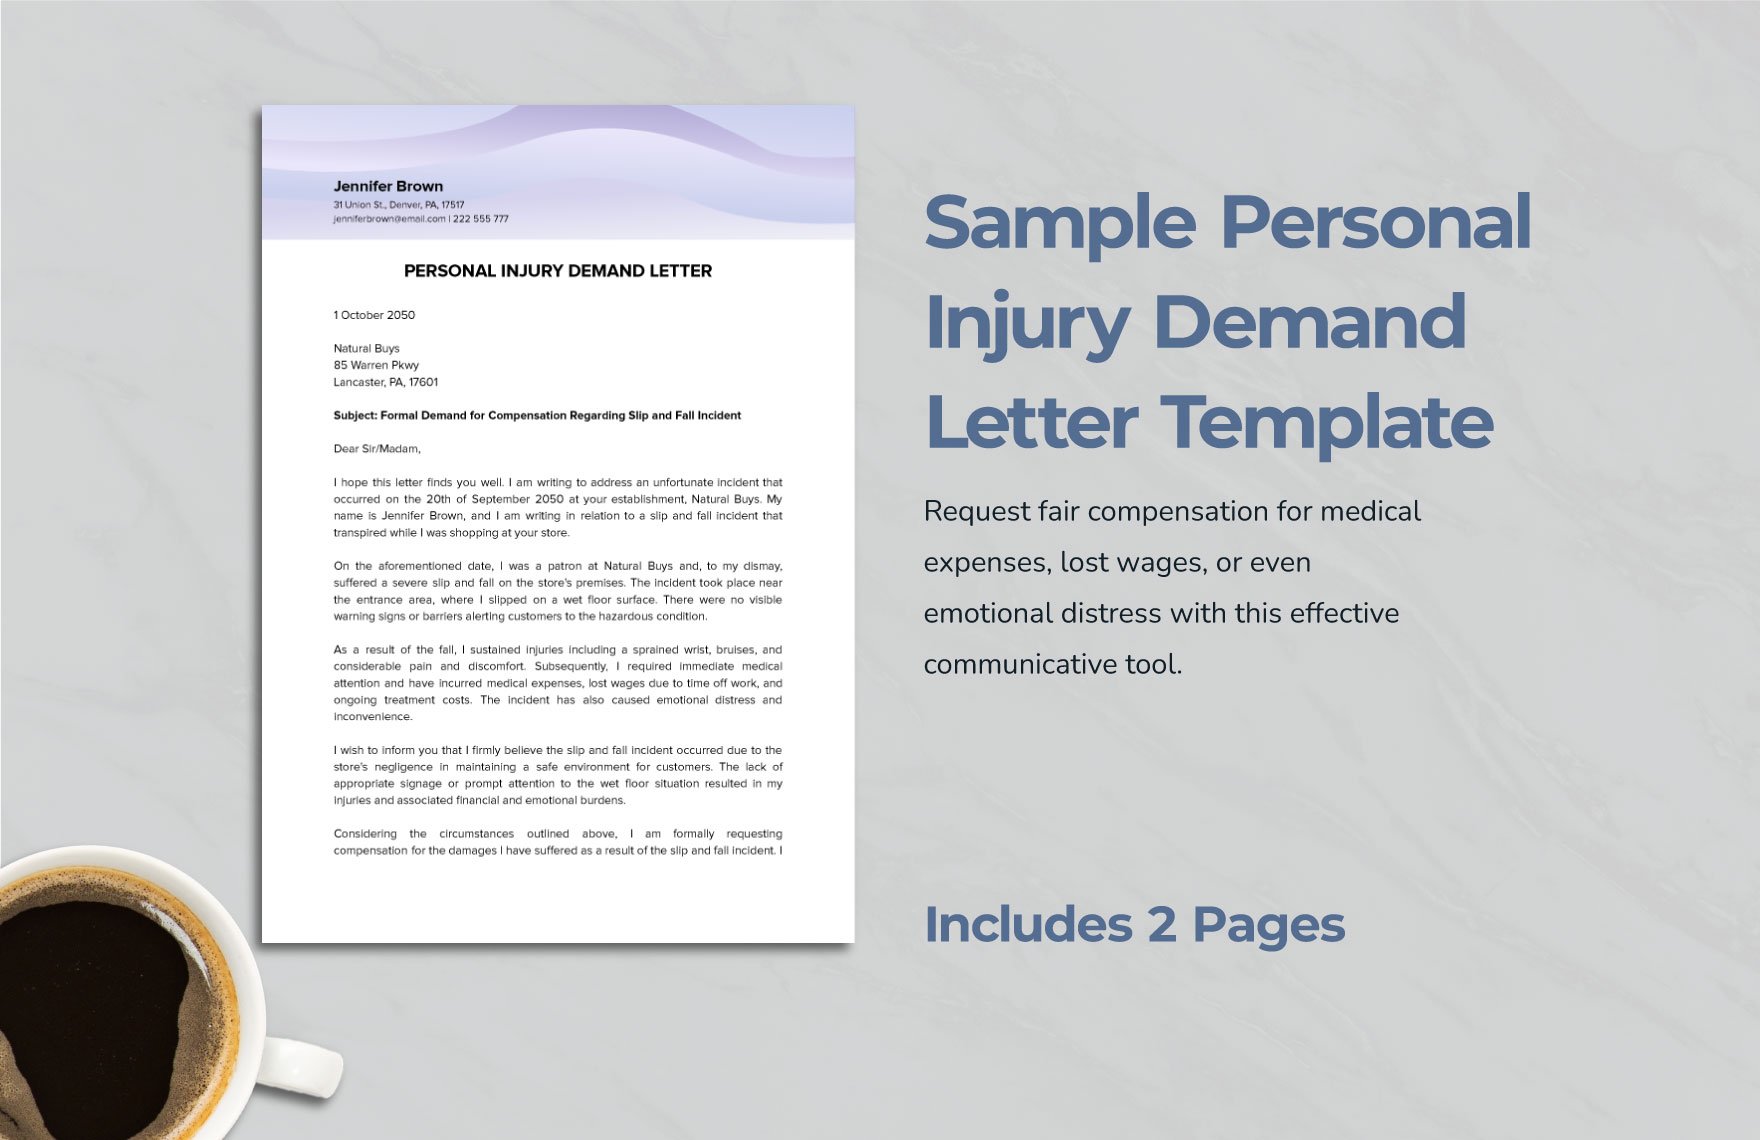
A demand letter in a personal injury case is your first formal attempt to get the other side to pay without going to court. It is not a magical document that makes insurance companies write checks on the spot. It is a strategic piece of communication that lays out your liability theory, documents your damages, and sets a specific price for resolution. Most claims settle somewhere between the demand amount and what the insurer initially offers. The gap between those two numbers depends heavily on how well you constructed the demand in the first place. I have spent years watching attorneys and claims handlers negotiate these things. The difference between a demand letter that gets a serious response and one that gets ignored usually comes down to three factors: the clarity of the liability argument, the organization of the damages schedule, and whether you included everything a claims adjuster needs to make an evaluation decision without having to call you.
Writing A Demand Letter For Personal Injury: What You Actually Need to Include
Before I explain the structure, let me share something most guides skip. When you are Writing A Demand Letter For Personal Injury, the single most important element is not the narrative at all. It is the medical lien documentation. I once had a case where the demand package was strong on liability but weak on lien resolution. The insurance company offered 40 percent less than they would have because they could not verify how much the providers were willing to accept. They used the uncertainty as leverage. Never let that happen to you. Your demand letter needs the following components arranged in this general order: 1. Header and recipient information. Include the claims adjuster's full name, title, company, claim number, and date. Verify the claim number against the policyholder's details. I have sent correct letters to the wrong claim numbers twice. It wastes weeks.
2. Representation statement. State clearly that you represent the injured party and that the purpose of the letter is to present a settlement demand. If you are the claimant representing yourself, state that explicitly. Self-represented claimants often get a lower initial offer because the insurer assumes less sophistication. That assumption can be overcome with a well-organized package. 3. Liability summary. This is where most people make mistakes. Do not write a novel. Write three to five paragraphs maximum. Include the date of the incident, the location, what the opposing party did or failed to do, and the applicable standard of care. Cite the specific traffic law or duty if you know it. Mention the police report number and whether fault was admitted. If fault is disputed, acknowledge that and lay out why your position is stronger. 4. Incident details. Reference the police or accident report by number and date. Note any citations issued. If there were witnesses, list their names and contact information. Include photographs if they are relevant and describe what they show rather than attaching them blindly. Photographs of the scene are useful. Photographs of your injuries taken three days later are more useful.
Get the Full Details
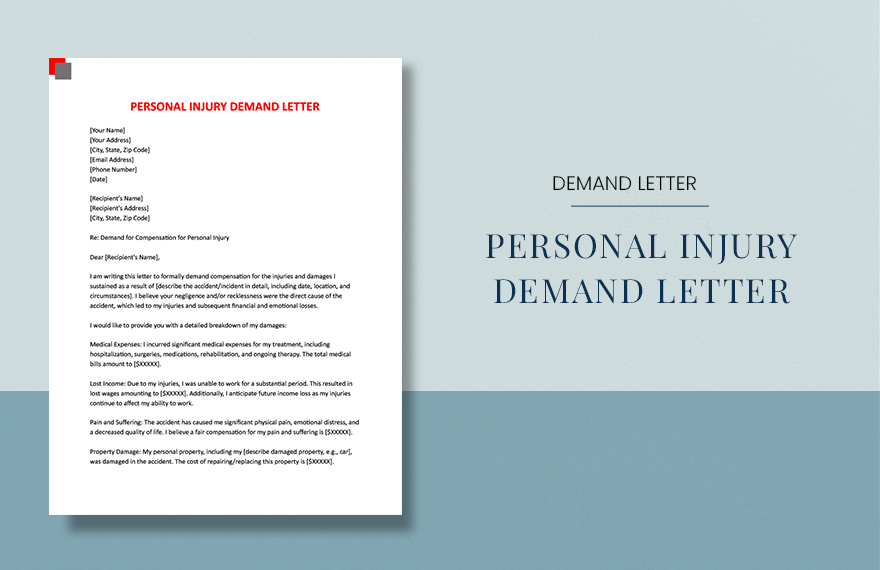
5. Injury and treatment narrative. Describe the injuries using medical terminology where appropriate but keep it readable. Include the mechanism of injury, the initial diagnosis, the treatment received, and the current status. Note any permanent impairments or prognoses. This section should be factual, not emotional. Adjectives do not increase settlement value. Specific medical facts do. 6. Damages schedule. This is the financial core. Break it into economic and non-economic categories. For economic damages, itemize every medical expense with the provider name, date of service, amount charged, and amount paid or allowed. Include prescription costs, medical equipment, travel to and from treatment, and any out-of-pocket expenses related to the injury. Attach the billing statements and explanation of benefits from insurance companies. The adjusted amounts matter more than the billed charges because adjusters will reduce everything to the allowed amount anyway.
For lost wages, include the employer name, dates missed, hourly or salary rate, and total income lost. If you are self-employed, attach tax returns and profit and loss statements. Document future lost earning capacity if the injury affects your ability to work long-term. This requires a vocational assessment or economist's report in serious cases. 7. Non-economic damages. Pain and suffering, emotional distress, loss of enjoyment of life, and physical impairment are all valid non-economic claims. Do not assign a formula to these in the letter. Let the adjuster evaluate them. However, you should provide a dollar figure for the total demand. The calculation method matters less than the justification. A common approach is to multiply economic damages by a factor between one and five, depending on severity and impact on daily life. I prefer to build the non-economic portion around specific life disruptions rather than a multiplier because it reads more convincingly.
The Settlement Calculation That Most People Get Wrong
Here is a counter-intuitive point. A higher demand does not always produce a higher settlement. I have seen demand letters asking for three million dollars on a case that was clearly worth six hundred thousand. The adjuster classified it as a bad-faith negotiation and anchored the counteroffer at fifty thousand. The lesson is that your demand should be credible first and ambitious second. A demand that is twenty to thirty percent above what you believe the case is worth is usually the sweet spot. Anything beyond that and you risk looking irrational. Another nuance people miss is the effect of comparative negligence. If your client was partially at fault, the insurer will reduce the offer by that percentage. Document your liability argument firmly in the letter. If the other driver ran a red light, say so. If your client was speeding, acknowledge it but explain why it was not the proximate cause. Hiding partial fault usually backfires because the adjuster will find it independently and assume the worst.

What to Attach to the Demand Package
The letter itself should be concise. Everything else goes in the attachments. Organize them in this order: Medical records including all ER reports, imaging results, physician notes, and discharge summaries. Redact any unrelated medical history. Include the treating physician's prognosis and any permanent impairment ratings. An attorney's letter on the plaintiff's behalf can be useful but is not required. Some adjusters take it more seriously when one is included. Others see it as padding. Billing records and proof of payment. Every line item should correspond to an attachment. If you reference a hospital bill of forty thousand dollars, the bill must be there. Missing documentation is the fastest way to lose leverage.
Police or accident reports. These carry weight because they are official records. If the report assigns fault to the other party, reference the specific section. Proof of lost wages. Employer verification letter, pay stubs, and tax documents where applicable. Photographs of the accident scene, vehicle damage, and visible injuries. Date-stamped images are essential. Photos without dates can be challenged as unrelated to the incident.
Receipts for out-of-pocket expenses. Transportation to medical appointments, over-the-counter medications, assistive devices, home modification costs, and any other injury-related spending.
Formatting and Delivery
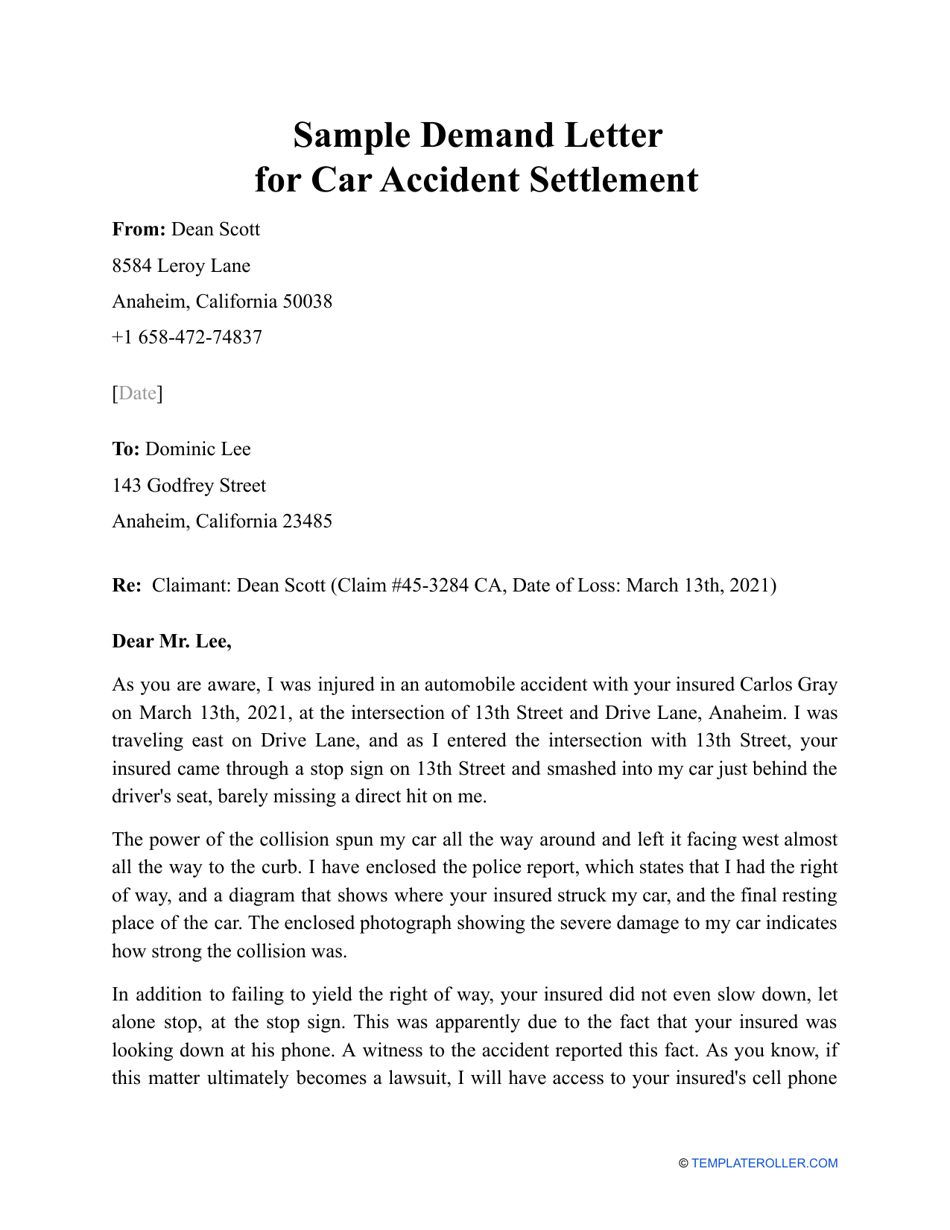
Send the demand letter via certified mail with return receipt requested and also via email if you have the adjuster's direct address. Certified mail creates a paper trail. Email gets a faster response. Use both. Reference the claim number in the subject line of the email. Keep the email brief and note that the full demand package is attached as a PDF. Structure the letter itself with clear headings and numbered paragraphs. Adjusters review hundreds of these. A cleanly formatted document is more likely to be read thoroughly. Use one-inch margins, a standard twelve-point font, and double-space the body text. Do not use legal shorthand or Latin phrases unless they are necessary. Plain language reads faster and lands better. I once spent four hours tracking down a single medical lien from a specialty clinic that had gone out of business. The records department forwarded my request to a third-party archive service, which took six weeks to respond. The workaround was filing a subpoena duces tecum directly with the county clerk. It cost about sixty dollars in fees and the records came back within ten business days. Including that lien in the demand package changed the settlement offer by nearly eighteen thousand dollars. Never skip the lien search.
Common Mistakes and How to Avoid Them
Asking for too much too early. As noted, excessive demands damage credibility. Start with a well-supported figure. You can always increase it during negotiation if new information emerges. Revealing trial strategy. Do not discuss expert witnesses, deposition plans, or settlement ranges you are willing to accept. The demand letter is not the place for that. Save it for actual negotiations. Missing deadlines. Every jurisdiction has a statute of limitations for personal injury claims. In most states it is two to three years from the date of injury. Filing a demand letter does not toll the statute in every state. Verify the rule in your jurisdiction. I had a client whose statute expired because the letter was sent on the last day and never received until the next business day. The case was dismissed.
Ignoring subrogation. If your client's health insurance paid for treatment, they have a subrogation interest. Document how that will be resolved. Some insurers agree to reduce their lien in exchange for a quicker settlement. Others do not. Either way, address it in the demand package or the adjuster will assume the worst and reduce their offer to cover the risk. Failing to follow up. Adjusters are slow. If you do not hear back within fourteen days, call. Leave a voicemail referencing the claim number and date of submission. Follow up in writing after the call. A polite but persistent follow-up cadence usually speeds up the process without damaging the relationship.

When a Demand Letter Is Not the Right Move
There are situations where sending a demand letter is counterproductive. If liability is genuinely disputed and you have no supporting evidence beyond your client's word, the letter will likely be rejected outright and the adjuster may close the file. In those cases, investing time in evidence collection before making a demand is more productive. If the damages are minimal, say under five thousand dollars in medical expenses with no lasting impairment, the cost of assembling a formal demand package may exceed the potential recovery. A simple written demand with supporting bills is sufficient in low-value cases. Do not spend three weeks preparing a package for a three-thousand-dollar claim. If the insurance policy limits are very low relative to the damages, sending a demand letter that clearly exceeds those limits will not produce a better outcome. The insurer cannot pay beyond the policy cap unless your client has separate coverage or personal assets. In those scenarios, consider whether a pre-litigation settlement discussion or a direct conversation with the adjuster might be more efficient than a formal demand.
The demand letter is a tool, not a ritual. Use it when it advances your position. Skip it when it does not. The goal is resolution, not paperwork.
A Final Note on Expectations
Most personal injury claims settle between the first demand and the first counteroffer. Some take multiple rounds. A small percentage go to trial. The demand letter starts the process and sets the tone for everything that follows. Write it like you expect the adjuster to read it carefully, because some will. Most will not. Prepare for both outcomes.