What you actually need to know about year-end payroll
Most people think year-end payroll is just about generating W-2s and filing them on time. It's more than that. It's about reconciling every quarter's filings, handling supplemental wages, dealing with retroactive adjustments from open periods, and making sure your withholding tables match what the IRS actually wants for the tax year you're closing out. Miss any of those pieces and you'll be chasing corrections in February instead of sleeping. The first thing to do is pull your quarterly payroll tax deposits and reconcile them against what you actually filed on Form 941. I've seen this go sideways because someone ran a correction batch mid-year that changed taxable wages but didn't trigger a deposit reconciliation. The result was a $4,000 underpayment that showed up as an interest charge, not a penalty. The fix was manual: pull the deposit history for every quarter, cross-reference to the 941, and flag any difference greater than zero. Don't trust the system to auto-reconcile that for you unless you've explicitly tested it. Once your quarterly deposits are clean, run the year-end payroll audit. This isn't the same as running a report and calling it done. You need to verify Gross-to-Net for every employee at least once, check that benefit deductions haven't rolled over incorrectly into the new year, and confirm that any bonus or commission paid in December but earned in November sits in the correct tax year. The last one trips people up constantly because some systems will push December supplemental payments into January if they weren't processed before the cutoff date. That moves the income to the wrong W-2 box and the wrong 941 quarter. I've had to reprocess three employees manually because the automated cutoff was set to December 28th and two bonuses went through on the 29th without anyone noticing.
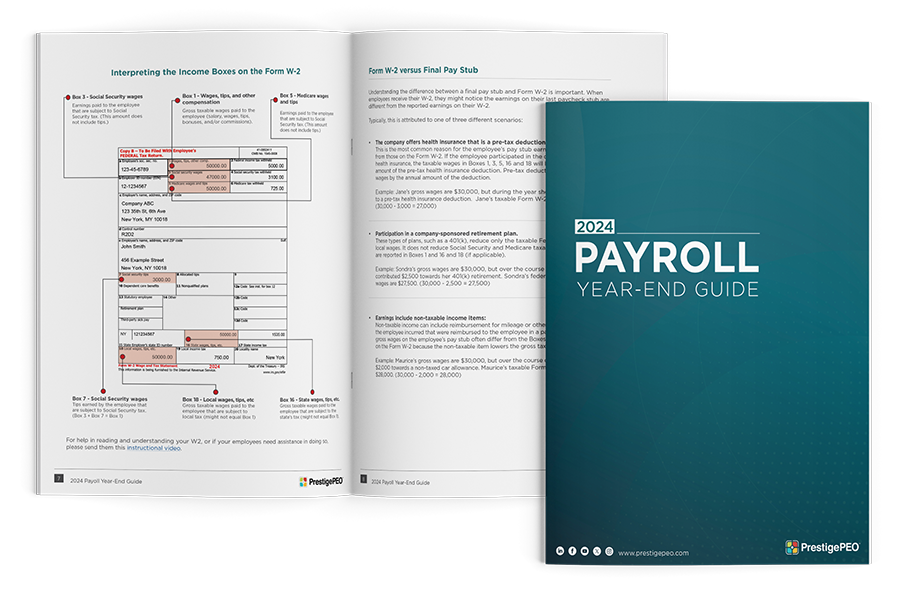
After the audit comes the W-2 generation phase. Here's where most small operations get complacent. Generate the W-2s, then immediately run a sample verification on at least ten percent of your employees. Check Social Security wages against actual YTD totals, verify Medicare wages and tips aren't duplicated, and make sure retirement plan contributions show in Box 2. I've caught cases where the system pulled the prior year's 401(k) elective deferral amount into the current year because the plan year didn't align with the calendar year. That error would have propagated to every W-2 for plan participants if I hadn't caught it during the sample run. The next step is state-level compliance, which most people treat as an afterthought. If you have employees in multi-state work arrangements, you need to calculate state withholdings by work location, not just by office of record. I had a remote employee whose W-2 showed only the home state because the system defaulted to the registered address. She worked from three different states over the course of the year. The fix was to pull her daily work logs, allocate hours by state, and file three separate state W-2c corrections. That took a Tuesday morning and cost me about two hours of manual spreadsheet work.
Processing windows and common failure points
The EIN-to-taxpayer matching phase is another area where errors accumulate. Before you file electronically, run a TPS (Taxpayer Processing System) match check on every employee's SSN. A mismatch here means your returns get rejected, and each rejection resets your filing window. I had one client who submitted 200 W-2s, got 14 rejections due to name-SNP mismatches, and had to resubmit twice more before January 31st. The lesson is simple: validate all SSNs against IRS records before you even attempt electronic filing. Supplemental wages deserve their own section because they don't follow the same withholding logic as regular pay. If you pay bonuses, severance, or commissions, those go through a different calculation path. Some systems default to aggregate method withholding, which pulls the supplement into the regular pay bracket and produces an incorrect tax amount. The faster method is correct for most supplemental payments and should be the default unless you have a legitimate reason to use aggregate. Running both methods side by side and comparing the results takes about 30 minutes for a company of 50 people and catches most errors before they hit the W-2. One counter-intuitive thing about year-end processing is that the highest-risk employees aren't always the ones making the most money. They're the ones with the most changes during the year. A person who got a raise in March, started a new benefit in June, had a dependent change in September, and received a bonus in November has eight data points where something could have gone wrong. Each of those changes should trigger an automatic recalculation of YTD withholdings. If your system doesn't do that, you need to flag those employees manually and re-run their calculations after each change event.
Get the Full Details
Software limitations and when it falls apart
Let me be blunt about the tools most people rely on. ADP, Gusto, Paychex, and similar platforms handle the standard case well. They fail when you have union negotiated pay rules that vary by seniority tier and department simultaneously, or when you operate in industries with complex fringe benefit calculations like construction or healthcare. I've seen ADP miss applicable large employer status for a company with 280 employees across four states because the system only looked at headcount in the primary state. Gusto handles multi-state well for standard W-2s but completely breaks down on workers' compensation reporting across jurisdictions. If your situation involves anything outside the standard hourly or salary employee model, you need a backup method that doesn't rely on the platform's built-in reporting. The most reliable workaround I've found is maintaining a parallel spreadsheet that tracks YTD gross, YTD federal withholding, YTD state withholding, and YTD FICA for every employee regardless of what the software says. Run this spreadsheet every Friday during Q4. By the time December hits, you already know if anything looks wrong. It takes about 15 minutes per week for a 100-person company if you've automated the pull from your payroll export. It saved me from filing three incorrect W-2s last year because the spreadsheet flagged a $12,000 discrepancy in one employee's YTD Medicare wages before we ever generated the forms. Another limitation people overlook: most payroll systems don't properly handle prior year adjustments once you've closed the year. If you discover in January that a December payment was posted to the wrong tax year, some systems will let you reverse it, but the reversal won't adjust the original W-2. You'll end up filing a W-2c anyway, which is fine, but you lose the ability to correct it through the system's normal amendment process. The workaround is to run a test year-end close on a sandbox environment before you actually close the books. I always run the year-end close process on a copy of the data first and verify that corrections remain editable. If the system locks everything on close, you need to either find a workaround or accept that you'll be filing manual corrections all spring.
What happens after you file
Filing isn't the end. You need to retain all supporting documentation for at least four years after the filing date. That includes your quarterly deposit confirmations, W-2c corrections, employee wage detail reports, and the reconciliation spreadsheets I mentioned. I've been audited twice in the last five years and in both cases the auditor asked for deposit history going back three years. Having it organized by quarter and matched to the 941 filing made each audit take about 45 minutes instead of three days of hunting through email threads. If you need a reference document to keep on hand, the IRS publishes Publication 15A, Employer's Supplemental Tax Guide, and Publication 15, Circular E, which covers everything from deposit schedules to annual filing requirements. They're free, they're updated annually, and they're more accurate than anything any software vendor will tell you. The IRS website is where you should get your answers, not the help center of whatever payroll system you're using.
Quick reference for the process
Here's the order that actually works in practice. Reconcile quarterly deposits to 941s first. Then run the YTD audit. Generate W-2s. Sample-verify the W-2s. Check state filings. Run the TPS match. File electronically. Retain documentation. Do it in that order and you'll rarely have issues. Do it in any other order and you'll spend February fixing mistakes you could have caught in January.