Working With Historical 1-Month LIBOR Data
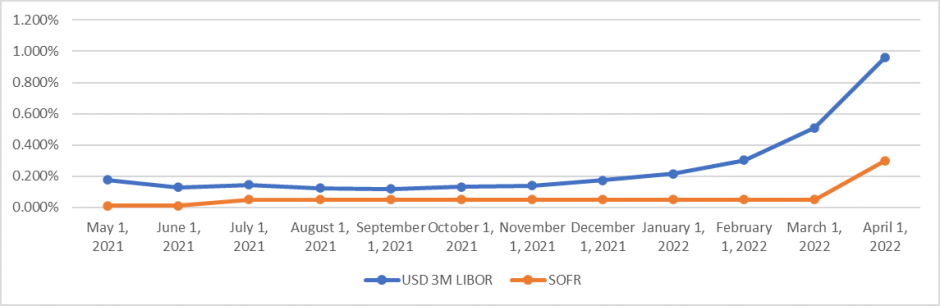
LIBOR was the most widely used short-term reference rate in the world for decades before it was phased out. The 1-month tenor in particular was embedded in everything from floating-rate bonds to commercial loan agreements. Now that the benchmark has been discontinued, people still need that historical data for contract adjustments, financial modeling, litigation support, and general reference. The rates themselves are publicly available, but the way they've been archived and the quirks you'll run into aren't obvious unless you've actually spent time with them. The 1-month LIBOR rate in 2022 moved significantly due to Federal Reserve policy shifts and broader monetary tightening. At the start of the year, the rate was sitting around 0.16% to 0.18%. It climbed gradually through Q1, accelerating sharply by March and continuing upward through the rest of the year. By December, the 1-month rate had reached approximately 4.2% to 4.3%, depending on the specific publication date within the month. Here are some representative figures to orient yourself:
January: approximately 0.15% to 0.18% March: approximately 0.80% to 0.90% June: approximately 2.55% to 2.70%
September: approximately 3.95% to 4.05% December: approximately 4.20% to 4.35% Those numbers are approximations based on the published benchmark rates. The actual value on any given date depends on the exact publication time and whether you're looking at the fixing for that specific day or the rate used for settlement on a roll-over date. LIBOR was published daily by the British Bankers' Association and later by ICE Benchmark Administration, so the data trail is well-documented.
Get the Full Details

Most people trying to reconstruct this data end up going straight to the Federal Reserve's H.15 statistical release. That's the official U.S. source and it carries authority you can rely on in a legal or compliance context. The Fed publishes a complete historical table going back decades, and the 1-month LIBOR series is labeled as the "London Interbank Offered Rate (LIBOR): 1-Month" series. The data is free, the format is clean, and you won't have to pay for a Bloomberg terminal just to look up a number. If you need the data in bulk — say, for a full-year dataset to import into Excel or a database — the Federal Reserve doesn't offer a direct CSV download from that page. What most people do is copy the table into a spreadsheet manually or use a tool like the Fed's data transformation utility if one's available through their website. Alternatively, you can grab the data from the ICE Benchmark Administration website, which maintains a dedicated historical LIBOR archive now that the benchmark has been discontinued. Another common source is Refinitiv's archive, but that typically requires a subscription. For a one-off lookup or even a full-year pull, the Fed is the most straightforward route. I've seen people waste half a day trying to scrape Refinitiv when the same data is sitting on fred.stlouisfed.org, completely free and searchable by code series ID.
The H.15 series ID for 1-month LIBOR is DPCSLMLI188S. If you know that string, you can go directly to the data page and pull the entire history without navigating through menus or figuring out export formats. You can also plug that series ID into the FRED API if you're building something programmatically. The API returns JSON, and the request is straightforward. It takes about 30 seconds to set up a Python script that pulls the full dataset and writes it to a CSV file, assuming you already have basic scripting knowledge. Here's the thing nobody warns you about when you're first dealing with historical LIBOR data: the rates you find online aren't always consistent across sources, and the reasons aren't always obvious. The Federal Reserve and ICE sometimes publish slightly different values for the same date. This happens because of late fixes, corrections, and the fact that multiple methodologies were used over the years. The difference is usually in the third or fourth decimal place, but if you're doing back-testing on a financial instrument or calculating settlement amounts for a contract that references LIBOR, even a basis point or two matters. I ran into this exact problem when I was compiling a full 12-month dataset for a client who needed to reconcile payment obligations under an old floating-rate note. The numbers from two different sources didn't match for about six dates in the spring of 2022. It turned out that one of those dates had a late submission from a contributing bank, and ICE published a revised rate while the Fed had already locked in the original fixing. The fix was to use the ICE Historical LIBOR archive as the primary source and cross-reference with the Fed for any dates where the values diverged. When they diverged, I flagged the discrepancy and used the ICE value since that's what the underlying contracts would have actually referenced at the time of fixing.
Another nuance worth noting is that the 1-month LIBOR rate is not always the same as the rate you'd use for a specific transaction date. LIBOR fixings happen around 11 a.m. London time on each business day, but the rate that applies to a loan or derivative depends on the contract's payment or roll-over date, not necessarily the fixing date closest to it. People routinely make the mistake of grabbing the rate for the wrong day. I've seen entire financial models come back with inflated or deflated projections because someone matched the payment date to the nearest calendar day instead of the actual referenced fixing date. It's a small error in isolation, but it compounds quickly when you're dealing with millions in notional amounts. The other thing that trips people up is the gap in data coverage. The Fed's H.15 table stops publishing new LIBOR values now that the benchmark has been discontinued. That's fine for historical research, but if you're trying to build a living system that pulls rates automatically, you'll hit a wall. The last official LIBOR fixings for most currencies and tenors occurred at the end of 2021 or early 2022, depending on the currency. The 1-month USD LIBOR was among the last to persist, with the final fixing published in June 2023 for most banks. After that, the benchmark was formally discontinued and replaced by alternative reference rates like SOFR. If you're working with a dataset that needs to extend beyond the LIBOR discontinuation date, you'll need to handle the transition explicitly. Some contracts have fallback language that switches to SOFR plus a spread adjustment. Others don't, and that creates ambiguity. The Secured Overnight Financing Rate is the standard replacement, but it's an overnight rate, not a 1-month forward-looking rate. The gap between how LIBOR was constructed and how SOFR works is significant enough that people building automated systems can't just swap one for the other without adjusting the calculation engine.

For a pure historical exercise — meaning you just need the numbers and nothing more — the process is straightforward. Download the data from FRED, verify a few dates against the ICE archive to catch any discrepancies, and import it into whatever spreadsheet or database you're using. The whole thing usually takes me about 15 minutes once I know what I'm looking for. The bottleneck isn't finding the data; it's making sure the dates align with your dataset's requirements and flagging any anomalies before you start calculating anything. A few more things to keep in mind. The 1-month LIBOR rate is quoted on a simple interest basis using a 360-day year convention. If you're converting it to an effective annual rate or comparing it to other benchmarks, don't skip that step. Treating a LIBOR rate as a straight annual percentage is a common mistake that leads to material pricing differences over time. Also, the historical data doesn't include the 2020 negative interest rate episode for USD LIBOR because the Fed kept USD LIBOR positive during that period. That's worth noting if you're comparing across currencies — EUR and JPY LIBOR did go negative in 2020, but USD 1-month did not. If your work involves litigation, regulatory examination, or any situation where the accuracy of the historical rate matters, I'd recommend keeping a copy of the official publication at the time of each fixing. Screenshots or PDFs from the ICE or Fed archive are useful because they provide an audit trail. A spreadsheet downloaded from FRED is fine for most purposes, but it doesn't carry the same weight if someone questions where the numbers came from later.
The data itself is freely available and the historical record for 2022 is complete and well-documented. The main challenge isn't access; it's making sure you're using the right version of the data and applying the correct conventions when you work with it. Get those two things right and the rest is just a matter of routine data management.