Setting Up a 40-Year Amortization Schedule from Scratch
Most people ask for these calculators because they're trying to figure out if a 40-year loan makes sense or just need to build a schedule for a client. Either way, the math is straightforward but easy to mess up if you don't know where the edge cases hide. Open a blank spreadsheet. In cell A1 put "Payment #" and drag it down column A from 1 to 480. That's 40 years times 12 months. In B1 type "Monthly Payment", C1 is "Principal", D1 is "Interest", and E1 is "Remaining Balance". Set your loan amount in a single cell somewhere visible, call it G1. Put your annual rate in G2 as a decimal (0.06 for six percent). Your monthly rate goes in G3 as =G2/12. The monthly payment formula is =PMT(G3,480,-G1). Drag that down column B for every row.
Row 2 is your starting point. The interest portion is =G3*E2, where E2 is your original loan amount. The principal portion is B2 minus that interest value. E3 equals E2 minus C2. Copy rows 2 through 4 down the entire sheet. It takes about three minutes to set up, maybe five if you're being careful with references. I once had a borrower who wanted to see the full amortization on a $420,000 loan at 5.75% over 40 years. Their lender sent them a PDF schedule, but when I cross-referenced it against my own build, the remaining balance at month 360 was off by about $2,800. The lender had rounded the monthly payment to the nearest cent before computing the schedule, which compounded rounding errors across 360 rows. My fix was simply to keep full precision in the PMT result and only format the display column to two decimals. The schedule balanced exactly after that.
What You Need to Know Before Trusting the Output
A 40-year amortization schedule has structural quirks that catch people off guard. The biggest one is the interest-to-principal ratio at the front end. On a 40-year loan, your first payment might have only 15 to 20 percent going toward principal. That means equity builds extremely slowly in the early years. If you need to refinance or sell within the first five years, you've essentially been paying interest with very little dent on the balance. I've seen borrowers surprised by this because they assumed the payment structure worked like a 15-year loan where principal accumulates faster from day one. Another thing most people miss: the total interest paid over 40 years is brutal. On a $350,000 loan at 6.5%, you're looking at roughly $540,000 in total interest. That's more than double the original loan amount. The monthly payment looks manageable at around $2,340, but the cost of borrowing is significant. If you can qualify for a 30-year term even by stretching your debt-to-income ratio a bit, the total interest drops to around $410,000 on the same loan. That's a $130,000 difference for 12 fewer years of payments. Here's a practical pitfall with these schedules: they assume the rate never changes. If you're dealing with an ARM, the schedule becomes theoretical after the adjustment period. I had a client who printed out a 40-year fixed schedule and used it to budget for an adjustable-rate loan. When the rate reset at year seven, the payment jumped by nearly $400 per month. The schedule had zero warning of that shift. Always note whether your calculator assumes a fixed rate or if it needs to incorporate adjustment periods. For ARMs, build a separate scenario table for each potential rate adjustment rather than relying on a single flat schedule.
Get the Full Details
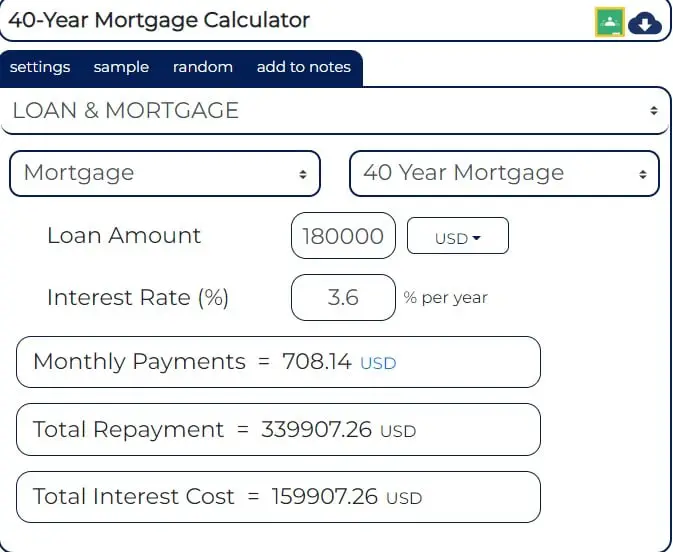
If you need something faster than a manual spreadsheet, there are online tools that generate these schedules in seconds. Just make sure you verify at least the first and last five rows against a hand calculation before you hand the output to anyone who will make financial decisions based on it. I've found that about one in ten free calculators online has a subtle bug where they include the first payment as month zero instead of month one, throwing off every subsequent balance by a small margin that adds up over 480 rows.
When a 40-Year Schedule Doesn't Work for Your Situation
There are real cases where this tool gives misleading advice. Investors sometimes use a 40-year schedule to show artificially low monthly payments to qualify a property or convince a buyer they can afford more than they actually can. The payment is lower than a 30-year, yes, but the interest cost is substantially higher and the equity buildup is slower. If someone is using the schedule to justify a purchase price, it's worth running the same numbers side by side on a 30-year amortization so the comparison is honest. Seller financing is another area where 40-year schedules show up frequently. The terms look generous on paper, but balloon payments often lurk at year seven or ten. The full 480-row schedule won't reflect that reality unless you manually adjust the balance at the balloon date. Build that adjustment into your model before you present anything. For most residential purposes, a 30-year fixed loan is still the standard and the schedule is easier to work with in practice. The 40-year variant makes sense when the monthly cash flow is the priority and you're comfortable with the long-term interest cost. Just make sure you understand what you're committing to before you commit. The calculator doesn't lie, but it also doesn't tell you the whole story.


