Parameterized nonlinear equations are the bane of simulation work
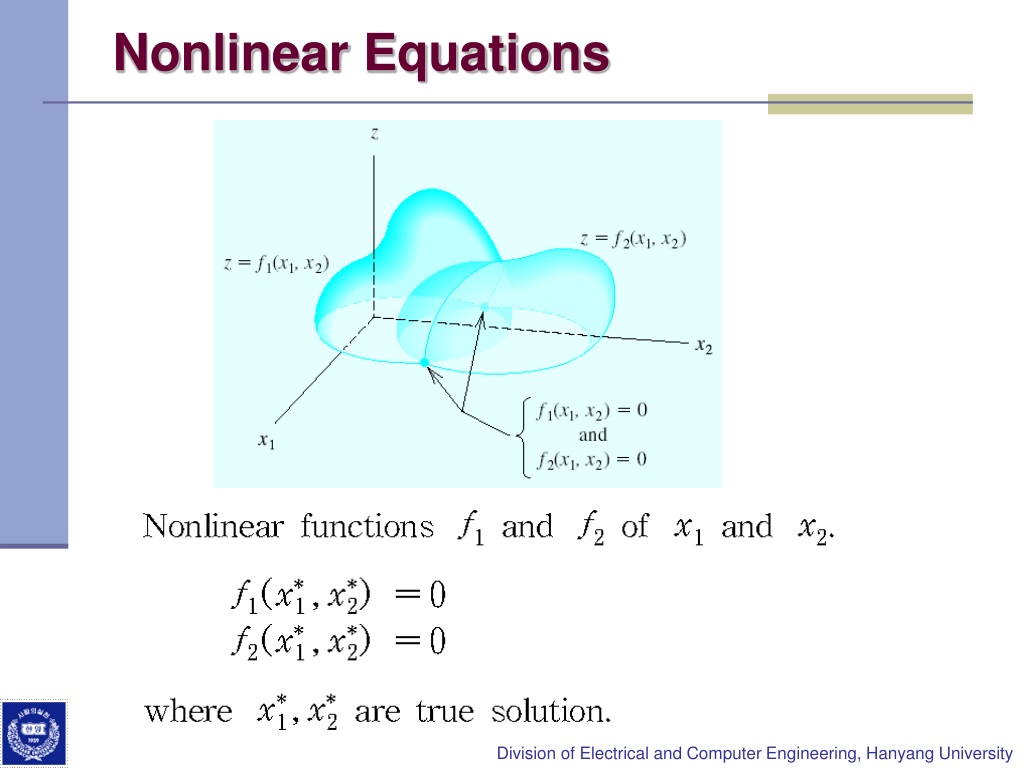
You set up a system where the variables depend on some tuning parameter — load, temperature, Reynolds number, whatever — and suddenly Newton's method stops working reliably. This isn't theoretical. I've spent years watching people try to solve these by brute force and then wonder why their solver crashes at lambda = 3.7. A parameterized nonlinear equation looks like this: F(x, ) = 0, where x lives in R and is a scalar or vector parameter. The solution set isn't a single point. It's a curve, possibly with branches, bifurcations, and folds. Most beginners treat as just another variable and apply standard root-finding. That fails at turning points because the Jacobian becomes singular. Your solver can't tell the difference between "the answer is degenerate" and "you're at a fold and need to turn." That distinction matters.
What Numerical Analysis Of Parameterized Nonlinear Equations Actually Involves
The core challenge is tracing the solution manifold as you vary the parameter. Simple iteration — fix , solve for x, increment , solve again using the previous solution as initial guess — works fine until you hit a limit point. At a turning point, dx/d goes to infinity. The predictor step overshoots, Newton's method diverges, and you spend an hour debugging a singularity that isn't actually singular. It's just a coordinate fold. Peano existence theory tells us that under mild conditions (F is C¹ and the Jacobian DxF is nonsingular at a solution), a unique smooth solution branch exists locally. But the moment DxF loses rank, you're out of luck with standard continuation. The workaround is arc-length continuation, also called pseudo-arclength continuation. Instead of stepping in , you constrain the next iterate to lie on a hyperplane perpendicular to the current tangent direction at a prescribed arc length distance. This lets you march through limit points without breaking. The algorithm runs like this. At step k, you have (x_k, _k) on the branch. Compute the tangent vector by solving the augmented linear system:
[DxF DF] [dx] [0]
[ ] [ ] = [ ]
[x^T ] [d] [1] This gives you a tangent direction (dx, d). Then your predictor step moves along this direction by the arc-length parameter s. Your corrector step projects back onto the solution manifold using a modified Newton iteration that includes the constraint equation. Repeat. I ran into this specifically when modeling a buckling problem for a thin-walled cylindrical shell under axial compression. The governing equations reduced to a system of about 400 nonlinear algebraic equations after discretization, with the pressure parameter . Standard Newton-Raphson converged for the pre-buckling path but failed catastrophically at the first critical load. The tangent stiffness matrix went numerically singular. Arc-length continuation got me through the post-buckling regime cleanly. The one change I made to the standard formulation was switching from a fixed arc-length step to an adaptive one — the step size shrank automatically near the bifurcation point and expanded in the smooth post-critical region. Saved me from either taking 10,000 tiny steps or jumping right over the interesting physics.
Get the Full Details

Discretization choices change everything
The method you pick for discretizing the underlying PDE or integral equation before solving the nonlinear system determines how hard the parameter study will be. Finite element discretizations of structural mechanics problems tend to produce sparse Jacobians that are well-suited to Newton-type methods with sparse direct solvers. Finite difference schemes on structured grids give you banded matrices but can introduce spurious numerical modes near boundary layers, which then confuse the continuation algorithm when those modes shift with the parameter. Spectral methods are another option. They give exponential convergence for smooth problems but produce dense Jacobians. For small parameter studies with low-dimensional systems, that's fine. For anything above a few hundred degrees of freedom, the memory and fill-in costs make them impractical compared to sparse approaches. I once tried a Chebyshev spectral discretization on a reaction-diffusion system with 150 modes per dimension. The Jacobian dense factorization took 40 seconds per Newton iteration. Switching to a finite-volume approach with an implicit Runge-Kutta time integrator dropped it to under two seconds. The choice between monolithic and segregated solution strategies also affects convergence. Monolithic approaches solve for all variables simultaneously, preserving the full coupling structure. Segregated approaches solve sub-systems sequentially, which reduces per-iteration cost but can introduce artificial instability at certain parameter values. For strongly coupled multiphysics problems, monolithic is usually worth the extra memory, but for weakly coupled systems the segregated route gets you results faster and is often good enough.
Initial guess quality is more important than you think
A bad initial guess doesn't just slow convergence in parameterized systems. It can send you to a completely different solution branch. This happens constantly in fluid mechanics when someone sweeps the Reynolds number upward. At Re = 5000, you get a steady solution. At Re = 10000, you expect a natural transition to a periodic wake. But if your initial guess at Re = 10000 comes from simply continuing the Re = 5000 solution, you might converge to a symmetric steady state that's actually unstable — or worse, the solver diverges entirely because the basin of attraction has shifted. The fix is mostly practical: use a homotopy continuation approach. Define a family F(x, , t) = t·F(x, ) + (1-t)·G(x) where G is a simpler system you can solve easily. Start at t = 0 and gradually increase to t = 1 while sweeping the physical parameter . This tracks a path from the known solution of G to the target solution of F. It's slower than direct continuation but far more robust, especially for problems with multipleSolution branches. The trade-off is computational cost. Homotopy methods typically require 10 to 50 times more function evaluations than pure arc-length continuation, so they're only justified when the direct path is unreliable.
Jacobian computation is where most implementations leak performance
Analytical Jacobians are ideal but rarely available for complex systems. Finite difference approximations are the default fallback, but they're expensive. Computing an n-by-n Jacobian via forward finite differences requires n plus one function evaluations. For a system with 1000 unknowns, that's 1001 extra evaluations per Newton iteration. With automatic differentiation, you get exact derivatives at roughly the cost of one function evaluation, but the implementation overhead is significant and the generated code can be memory-hungry. In practice, the middle ground is tabular differentiation or approximate Jacobians that you update infrequently. If the Jacobian doesn't change drastically between consecutive parameter values — which is usually true near a smooth portion of the solution branch — you can reuse it for several Newton iterations and only recompute when the iteration count exceeds a threshold. I've seen this cut wall-clock time by 60 to 70 percent on medium-scale problems. The risk is stagnation if the parameter varies rapidly enough to change the Jacobian structure significantly between updates. Monitoring the Newton correction norm and triggering a re-evaluation when it plateaus is a reasonable safeguard.

Validation requires more than a converged solution
A common mistake is assuming that convergence of the numerical solver means you've found the correct physical solution. For parameterized nonlinear systems, convergence just means you found a zero of F. It could be a stable equilibrium, an unstable equilibrium, a spurious numerical artifact, or a solution that satisfies the discrete equations but not the original continuous problem due to discretization error. Verification against an analytical benchmark in a limiting case is essential. Check the small-parameter asymptotics. Check the large-parameter behavior. If your numerical solution violates a conservation law or energy bound that the continuous system obeys, something is wrong regardless of residual magnitude. Sensitivity analysis provides another layer of validation. Compute the condition number of the Jacobian along the solution branch. When the condition number spikes, you're near a bifurcation or turning point, and your numerical results become unreliable regardless of the solver used. In my experience, a condition number above 10^10 for double-precision arithmetic means the solution is numerically indeterminate. You need to either reformulate the problem or accept that the branch is not computable with standard floating-point precision. Mesh or grid independence testing should accompany any parameter sweep. A solution that looks converged on one mesh may shift significantly on a finer mesh, especially near critical points where gradients steepen. Running the same parameter study on two or three successively refined discretizations and comparing the branch trajectories gives you a practical error estimate without requiring rigorous a priori convergence analysis.
Software options are limited but adequate
Auto07p is the classic standalone code for continuation and bifurcation analysis. It's been around since the late 1980s, handles ODE and PDE systems, and supports both regular path-following and bifurcation detection. The learning curve is steep — the input format is verbose and poorly documented by modern standards — but it's reliable. MATCONT is a MATLAB-based alternative with better visualization and easier setup, though it's less suited for very large-scale problems. For custom implementations, libraries like CONTPACK or the Eigenvalue solver packages embedded in PETSc give you building blocks but require significant integration work. Commercial packages like ANSYS Mechanical and COMSOL have built-in continuation capabilities for structural and multiphysics problems. These abstract away the numerical details but also restrict what you can do at bifurcation points. If you need to compute unstable branches or trace complex bifurcation diagrams, you're better off with a dedicated continuation tool or a custom script. The abstraction that makes commercial software convenient is the same thing that limits you when the physics gets interesting.
Practical Numerical Analysis Of Parameterized Nonlinear Equations Workflow
Start with a simple one-parameter problem and verify your implementation against a known analytical solution. Get the arc-length continuation working before adding complexity. Introduce the parameter sweep, monitor the Jacobian condition number at each step, and log every divergence or convergence failure. These are the points where the physics changes qualitatively, and missing them means missing the phenomena you're actually interested in. When the solver fails near a critical point, reduce the arc-length step and switch to a smaller fixed parameter increment. Don't just increase the maximum iteration count and hope for the best — that masks the underlying issue rather than resolving it. The biggest mistake people make is treating parameterized nonlinear systems like standalone root-finding problems. They're not. They're manifolds in a high-dimensional space, and your job is to map those manifolds accurately. The numerical methods exist. The tools exist. The hard part is knowing when the tools fail and what to do about it.