Why Anyone Would Even Consider a 40-Year Mortgage
The short answer is almost always: they shouldn't. But they do, and they have reasons. A 40-year mortgage term stretches your amortization schedule out further than anything you'll find at a standard lender counter. The monthly payment on a $400,000 loan at 7% comes to roughly $2,517 over 40 years. Over 30 years at the same rate, that same balance balloons to about $3,352 per month. That thousand-dollar difference matters when you are trying to qualify on a tight income or keep cash flowing for other obligations. I ran into this exact scenario a few years back. A client was approved for a $425,000 purchase at 6.875%, but their debt-to-income ratio came in at 49.3% on a 30-year amortization. The lender would not go above 50%. We dropped the term to 40 years, the payment fell to roughly $2,618, and the DTI hit 46.8%. He got the deal done. It cost him an extra $180,000 or so in total interest over the life of the loan. He knew it. He did the math himself before signing. That is the whole conversation around these products, honestly.
Using a 40 Year Mortgage Payment Calculator
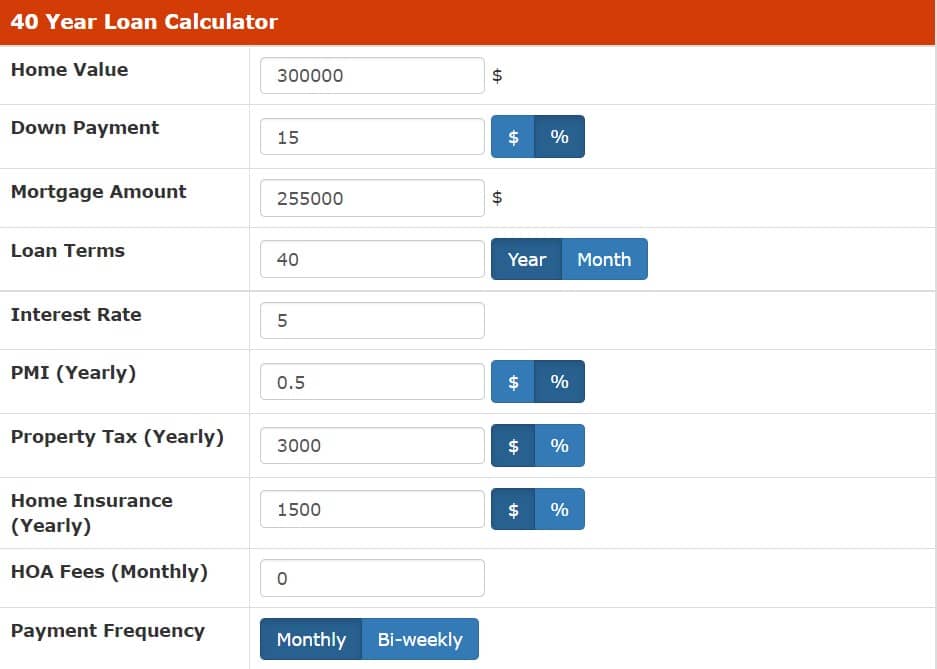
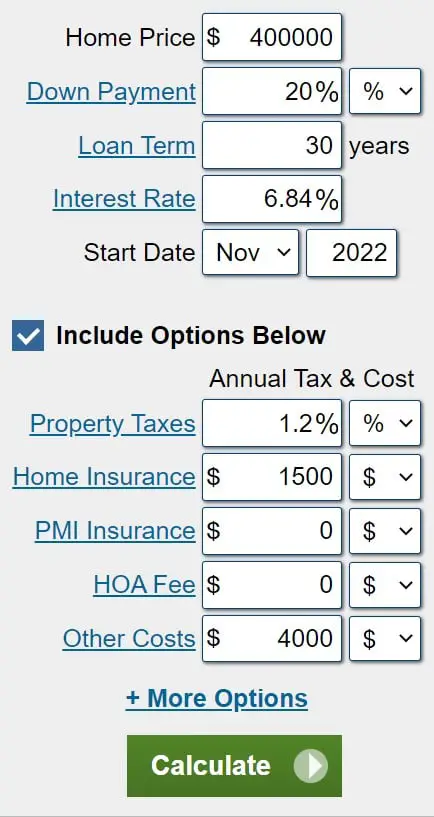
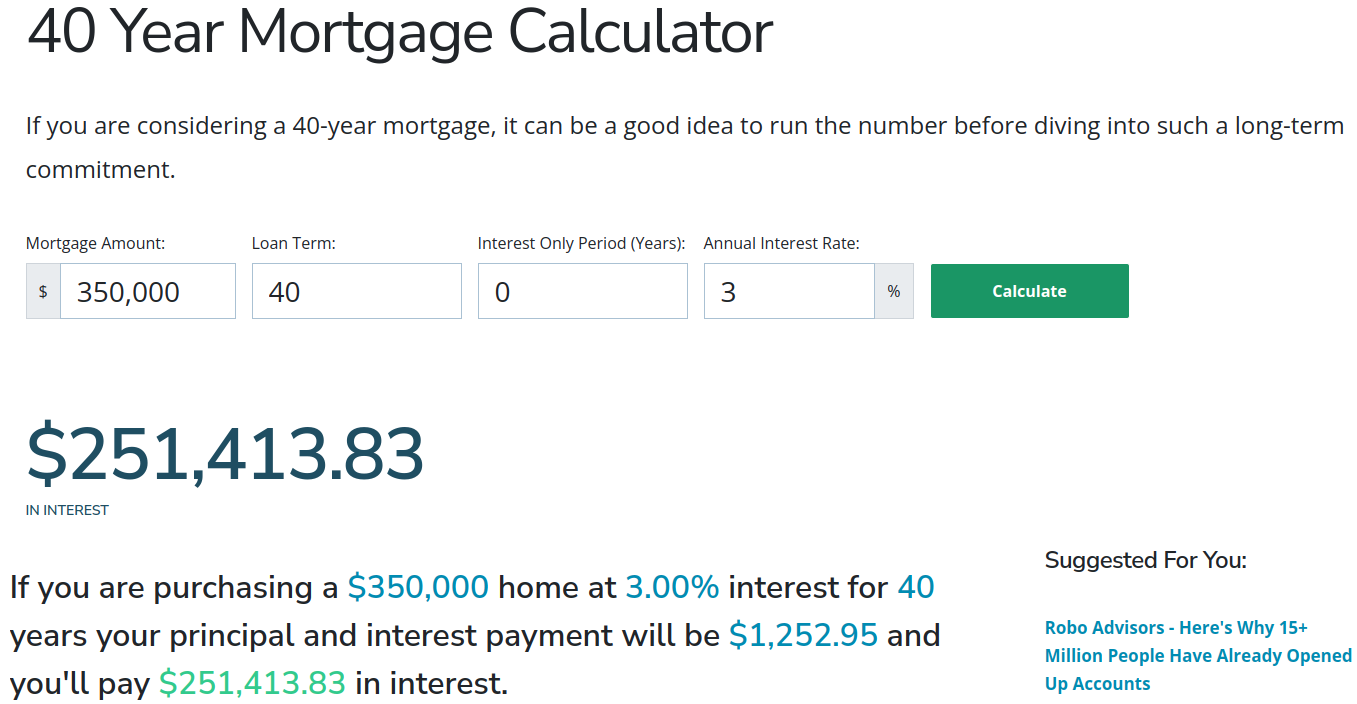
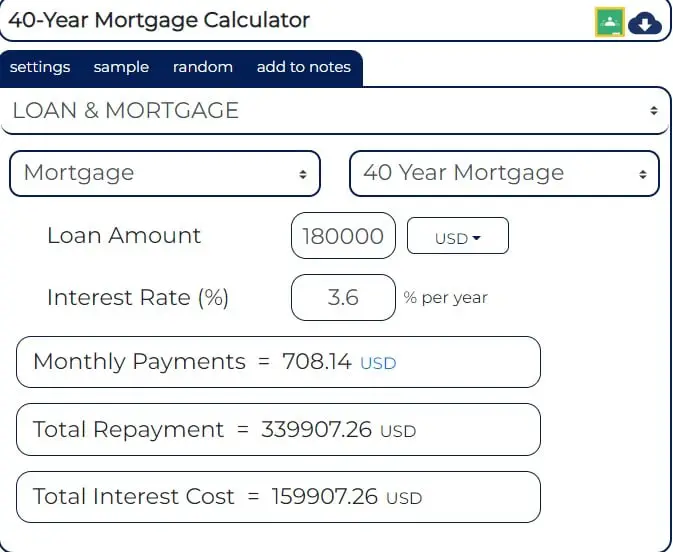
Most online calculators for this are built on the standard annuity formula, and they work fine for quick estimates. You plug in the principal, the annual rate, and the term in years. The result is your base principal-and-interest payment. Some of them also let you add property tax and insurance, which is useful for getting a full PITI figure. The ones that trip people up are the ones that silently assume a fixed rate and never let you toggle in an adjustable rate scenario, which is actually quite common for longer-tenor products. When I need something more precise than a browser widget, I use a small spreadsheet with the PMT function in Excel or Google Sheets. The formula looks like this: =PMT(rate/12, nper, -principal). For a 40-year loan, nper is 480. You enter the annual rate divided by twelve for the periodic rate. The negative sign on the principal makes the output positive, which reads cleaner. It takes about thirty seconds to set up, and once you have it, you can swap rates in seconds and compare side by side without reloading a webpage. Here is a concrete example. A $350,000 loan at 7.25% over 40 years gives a principal-and-interest payment of approximately $2,384.72. If you throw in estimated property taxes of $450 per month and homeowners insurance of $140 per month, your total PITI lands around $2,974.72. On a 30-year term at the same rate, the principal-and-interest portion jumps to about $2,389. That may look close until you multiply by 360 versus 480 payments. The total interest paid over 40 years at this rate is roughly $744,000, compared to about $510,000 over 30 years. The difference is nearly a quarter-million dollars.
What These Calculators Get Wrong Almost Every Time
Free calculators rarely account for mortgage insurance on conventional loans under 20% down. If your loan-to-value ratio sits above 80%, you are looking at PMI that runs roughly 0.5% to 1.5% of the original loan amount annually, depending on your credit profile and LTV band. On a $350,000 loan with 10% down, that could add $150 to $400 a month until you reach the cancellation threshold. Some calculators include an optional field for this. Most do not. You have to add it manually if you want a realistic number. Another thing that gets glossed over is the effect of points. Paying one point at closing lowers your rate by roughly 0.25% on many products. A 40-year loan with a 0.25% buydown might move you from 7.25% to 7.00%. The payment difference is small in absolute terms over four decades, but the break-even calculation can be misleading when the term is this long. You pay the point upfront and stay in the loan for the full term, so the math often works out in your favor. It is rare for it to work out poorly, but it depends entirely on your personal timeline and tax situation.
Get the Full Details
A Realistic Edge Case I Encountered
Working with a self-employed borrower who had strong documented income but irregular cash flow, I needed to model a 40-year loan where the payment was lower than the minimum required for debt qualification on a 30-year term. The issue was that the calculator output did not align with what the underwriter would actually approve because the underwriter uses a blended stress rate, not the advertised rate. I pulled the official rate sheet from the lender and found the stress rate was 0.5% above the note rate. Running the calculator with the stress rate instead of the stated rate changed the qualifying payment by about $120 per month. That shifted the borrower from denied to approved. It was a three-minute fix once I knew what to adjust, but the default calculator would have given the wrong answer if I had just used the advertised rate blindly. First, a 40-year mortgage is not always cheaper than you think when you factor in refinancing risk. If rates drop significantly in year five and you want to refinance into a 30-year loan, you will be locked into a new amortization schedule that starts over. Many borrowers assume they can ride the 40-year term for the full duration and then sell. That is fine if your plan includes selling in ten to fifteen years. It is not fine if you assumed you would keep it for life and then magically end up with a shorter payment. The interest you save early on vanishes quickly once you refinance and reset the clock. Second, the effective annual percentage rate on these loans can look deceptive. Lenders are required to disclose APR, which includes certain closing costs amortized over the loan term. Because a 40-year term spreads those costs thinner across more months, the APR can appear closer to the note rate than you might expect, even though the total cost of borrowing is substantially higher. Do not compare the APR of a 40-year loan to the APR of a 30-year loan and assume they are apples to apples. The numerator and denominator are different lengths. The total interest number is the honest comparison metric here.
There is also the prepayment behavior angle. A 40-year loan gives you more room to make extra payments toward principal without stretching your monthly budget. If you can swing an additional $500 per month toward principal, you can cut the effective term down substantially. I ran the numbers on a $400,000 loan at 7% with an extra $500 monthly principal payment. The loan paid off in about 28 years instead of 40, and total interest dropped from roughly $606,000 to about $385,000. That is a savings of over $220,000 while keeping the base payment manageable. The calculator still shows the full 40-year payment unless you tell it to factor in the extra principal, so most people miss this option entirely.
When This Tool Is Actually Useful
It is useful for quick side-by-side comparisons before you talk to a lender. If you want to understand the gap between a 30-year and 40-year payment on a specific loan amount, a calculator gives you the answer in seconds. It is also useful for showing borrowers the exact interest cost difference so they can decide whether the lower payment is worth the extra $150,000 to $250,000 in total interest depending on rate and term. That conversation tends to land better when you have a number in front of both people rather than just saying "it costs more." Numbers shut down vague objections faster than advice does. I keep a simple spreadsheet that does most of this automatically. It has cells for loan amount, annual rate, term in years, property tax, insurance, and PMI. You change one variable and the rest update instantly. It also calculates total interest, total cost, and the monthly payment difference between term options. Setting it up took me maybe twenty minutes the first time. Since then, I have saved hours on client consultations because I can pull up the comparison on the spot. If you are going to research this yourself, building your own version is faster than bouncing between five different websites.
Common Pitfalls to Avoid
Do not assume the payment number is fixed. Adjustable-rate products tied to longer amortizations exist, especially in investment property markets. If your calculator assumes a fully fixed rate and your loan is actually ARM-based, the number you see today could be off by several hundred dollars within a year. Check the loan product type before trusting the output. Do not forget about the impact of your credit score on the rate you actually qualify for. A 40-year loan is not standardized the way a conventional 30-year is. Availability varies by lender and region. The rates you see on aggregator sites may not reflect the rates available to you personally. Run your own calculator with your actual quoted rate, not the average listed online. The difference between 6.75% and 7.50% on a $400,000 loan over 40 years changes the monthly payment by about $115 and the total interest by over $55,000. Finally, be honest with yourself about whether you will actually keep this loan for forty years. Most people do not. If you plan to sell or refinance within ten years, the 40-year structure is mostly a qualification tool, not a long-term strategy. That is fine. Just know what you are using it for and calculate accordingly. The calculator will give you the right number either way. What matters is what you do with that number.