The Reality of Short-Term Mortgage Structures
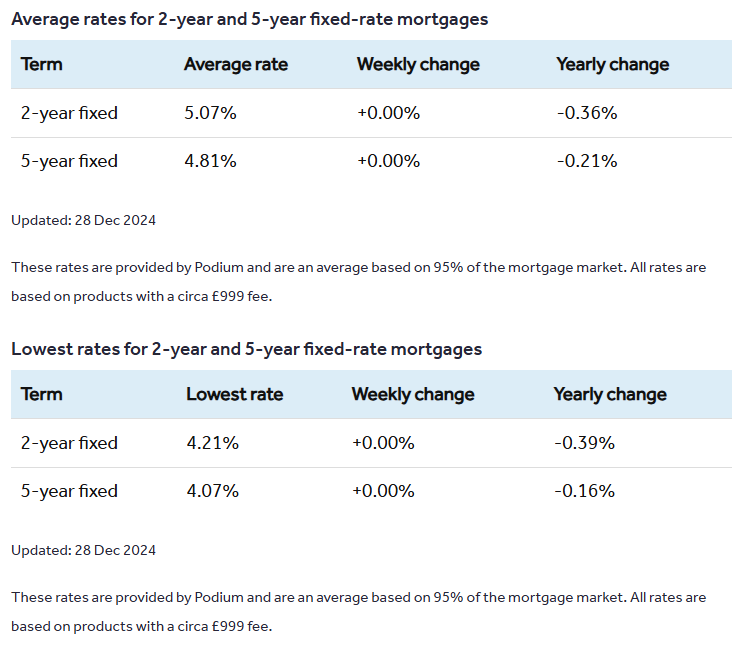
A 5 Year Mortgage Loan is a financing arrangement where the interest rate is locked for five years, after which you either refinance into a new term or move to your lender's default rate. The loan itself typically runs much longer—15, 20, or 30 years—but the pricing certainty only extends five years out. This is the standard product in Canada and several other markets where fixed-rate mortgages are sold in term increments rather than as fully amortizing single-rate commitments. I used to think people picked these based purely on rate comparisons. That's not how it actually works. The real decision comes down to your exit strategy and how you handle the renewal moment, which is where most borrowers get burned.
Navigating a 5 Year Mortgage Loan Renewal
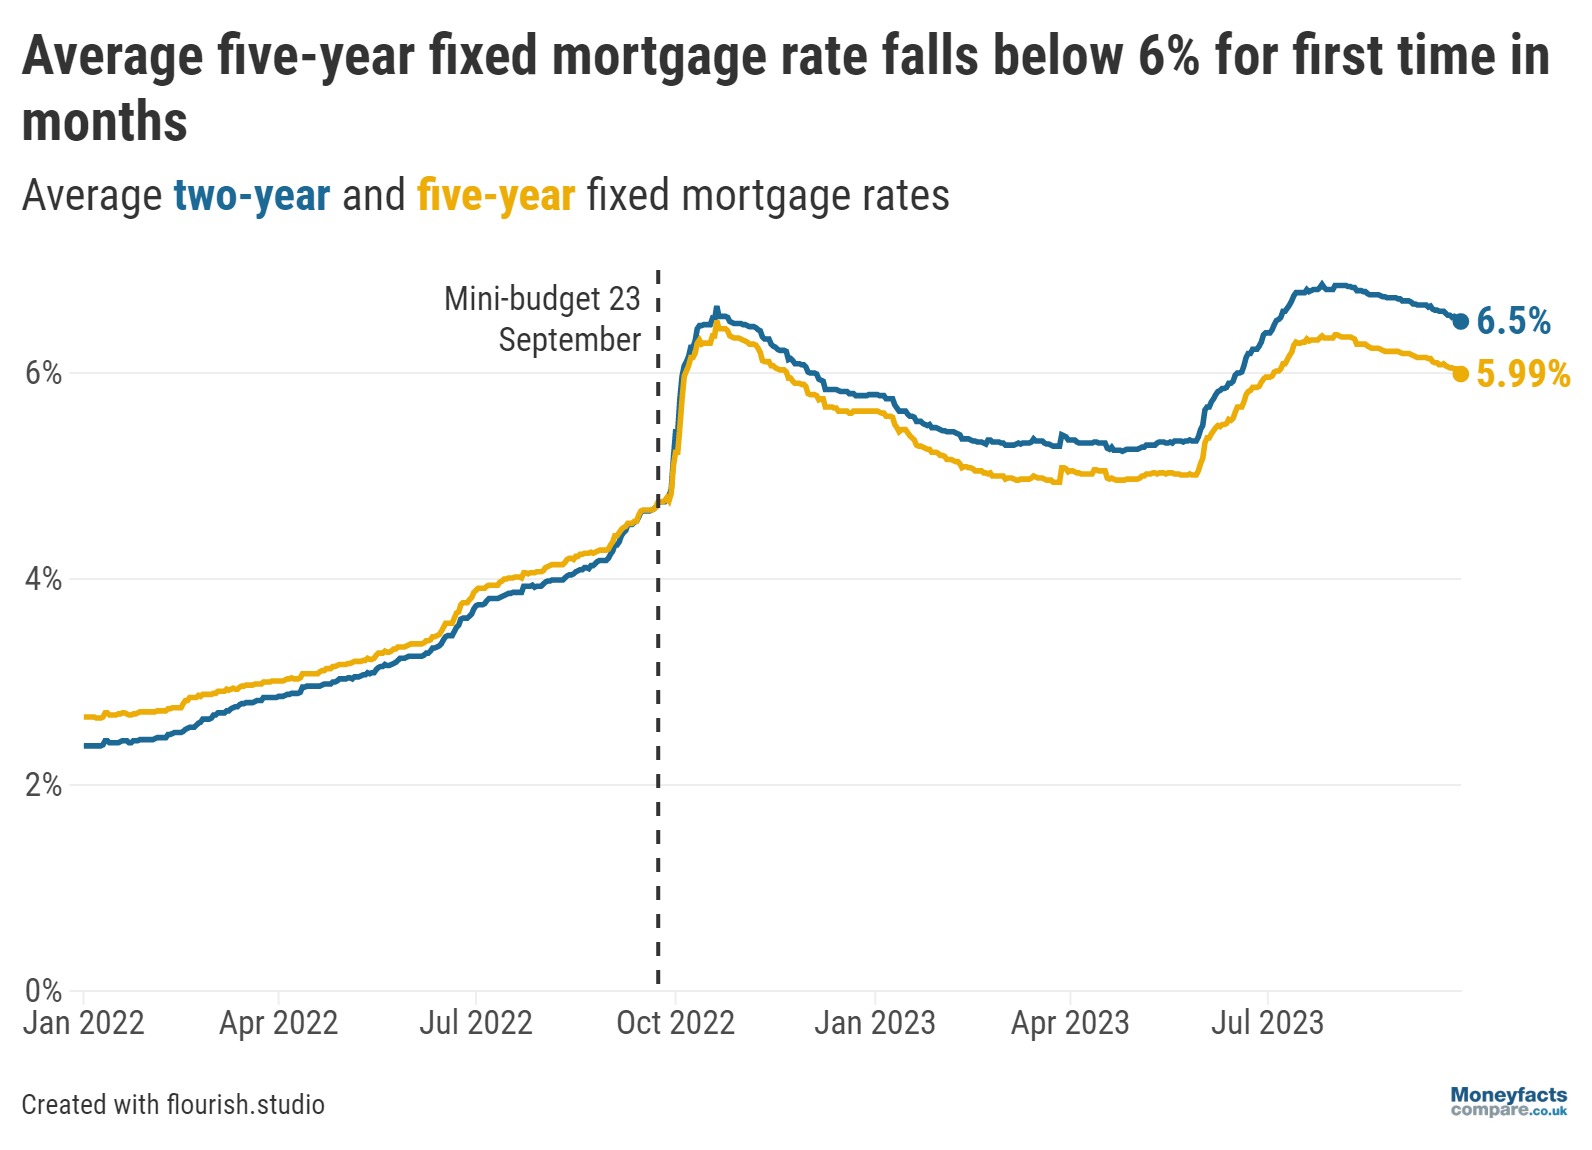
Here's what happens at renewal that nobody warns you about. Your lender sends you a renewal statement 21 days before your term ends, usually with a rate that is 1 to 2 percent above what you originally locked in. If you do nothing, you roll into that rate automatically. I've seen borrowers accept the first offer because they were tired of the process, and they ended up paying tens of thousands extra over the remaining amortization. The workaround is simple but requires action: request a renewal quote at least 60 days before your term matures, then shop it against at least two other lenders. Not all lenders will give you a competitive rate if you wait until the renewal window opens. Some will deliberately inflate the number hoping you'll just sign whatever lands on your desk. The mechanics behind this are straightforward. Your mortgage balance, current credit profile, and prevailing market rates determine your renewal offer. Lenders factor in how much equity you've built, whether your debt service ratios have changed, and what the bond market is doing that week. A rate that looks attractive on day one might be replaced by a better offer three weeks later if the yield curve shifts. That's why timing your renewal conversation matters more than most people realize.
How the Math Actually Works
Let me walk through a concrete example. Say you took out a $400,000 mortgage at 4.79% fixed for five years with a 25-year amortization. Your monthly payment would be approximately $2,337. After 60 months of payments, you'd have paid roughly $140,220 total, but only about $52,000 of that would have reduced your principal. The rest went to interest. At renewal, your remaining balance would be closer to $348,000, and your new rate would depend entirely on where the market is at that point. One thing people miss: the amortization clock doesn't reset at renewal. You continue paying down from where you left off. This means a shorter remaining amortization period could push your monthly payment up significantly if you lock in a higher rate. I worked with a client who renewed at 7.2% with only 12 years of amortization left, and their payment jumped from $2,337 to $3,891. They hadn't anticipated the jump and had to refinance into a longer term just to stay cash-flow positive. The alternative structure worth considering is a shorter term like 2 or 3 years. You give up some rate stability, but you renew more frequently when rates might be lower. In a falling rate environment, short terms win. In a rising environment, 5-year terms protect you. The problem is predicting rate direction is nearly impossible, which is why most people just pick the longest term they can afford to lock in and hope for the best.
Get the Full Details
Where This Product Fails You
A 5 Year Mortgage Loan is not ideal if you plan to sell or move within the term. Break costs can be steep. In Canada, the penalty for breaking a fixed-rate mortgage early is the greater of three months' interest or the interest rate differential (IRD). The IRD calculation is where things get ugly. It compares your rate to the current rate for a equivalent term at your lender and multiplies the difference by your remaining balance and the number of months left in your term. I had a situation last year where a borrower wanted to break a 5-year deal at year three because their house listing fell through and they needed to consolidate debt. Their balance was $380,000, their rate was 3.89%, and the lender's current 5-year rate had dropped to 4.99%. The IRD penalty came out to roughly $19,000. Three months' interest was only about $4,750. They took the lower penalty, but if rates had moved the other way, the IRD could have been brutal. This is why pre-selling your property or confirming your exit timeline before signing matters more than the quoted rate ever will. Another limitation is that lenders often restrict additional payments on fixed terms. You may be allowed to make a lump sum payment once per year up to a certain percentage of your original principal, but going beyond that can trigger penalties or require a restructuring. If you're the type of borrower who wants to flexibly throw extra money at the balance whenever you get a windfall, a flexible open mortgage or a shorter fixed term with prepayment privileges will serve you better. There's also the issue of portability. If you're moving to a new property, you can often port your existing mortgage to the new home, but the ported amount must be at least 50% of the original mortgage, and any shortfall gets blended at current market rates. I once saw a port situation where a couple moved from a $300,000 home to a $600,000 property. They ported $200,000 at their old 3.5% rate and took out the remaining $200,000 at 6.1%. The blended rate looked reasonable on paper, but their payment increased by nearly $800 a month because the new portion carried the higher rate across a full 25-year amortization while the ported portion stayed on its shortened schedule. The math works differently than most people expect when two rates run in parallel.
Practical Steps to Make This Work
Start by pulling your current mortgage statement and noting your exact maturity date, remaining balance, and any prepayment privileges you have. Write those numbers down. Then 90 days before maturity, contact your current lender and request a renewal quote in writing. Don't accept verbal promises. Next, get quotes from at least two other lenders for the same terms—same balance, same amortization remaining, same credit profile. Compare the annual percentage cost, not just the headline rate. Some lenders advertise low rates but bundle expensive fees into the deal. Look at the total cost over the remaining amortization, including any penalty for early discharge if your plans change. If your financial situation has improved since you originally signed—your credit score went up, your debt load decreased, your employment is more stable—you have leverage. Bring that evidence to the negotiation. Lenders routinely offer better rates to lower-risk borrowers even during renewal. I've watched borrowers who simply asked for a rate review at renewal get dropped half a percent without any additional documentation, just because the system allows it and the branch manager didn't feel motivated to push back. When your term ends and you're not ready to sell, refinancing into a new 5-year term at a competing lender is usually cheaper than staying with your current lender, unless they match or beat the market rate. The switching process itself typically takes 2 to 4 weeks and involves a new appraisal, credit check, and legal discharge. Budget $1,500 to $2,500 for legal and appraisal fees unless you negotiate fee waivers as part of the rate deal. Some lenders will cover your discharge costs if you bring your balance above a certain threshold.
The hardest part about managing a 5 Year Mortgage Loan over multiple terms isn't the math. It's staying aware of your renewal date and treating it as a renegotiation event rather than a passive automatic process. Set a calendar reminder for 120 days out. Then another at 60 days. Then one at 30 days. The person who remembers to shop around at the right time saves more money than the person who finds the lowest advertised rate in January. Timing beats rate shopping every time.